



"At a Glance" Local Housing STATS and News 09/14/26
September 14, 2026 · Alameda County Market Dashboard
TODAY'S LIVE INVENTORY
Behind these county totals: hundreds of homes still for sale in Fremont, Hayward, Union City, Newark and Milpitas, counted, priced and sorted every morning from the same MLS export, with a map search for the homes themselves.
30-Year Fixed: 7.17% +0.05 | 15-Year Fixed: 6.70% +0.05
Rates just hit a one year high. Mortgage News Daily has the 30-year at 7.17% and the 15-year at 6.70%, both up 0.05 from Friday and the highest readings of the past year. The 10-Year closed Friday at 4.96%, its highest close since at least January 2024, and mortgage rates follow the 10-Year.
Inflation is why. Consumer prices rose 3.4% over the past year in August, and the Fed meets Wednesday with Kalshi and Polymarket both putting a quarter-point hike at 84.5%. At Fremont’s median list price of $1,249,000, a 20% down loan is $999,200, which fits under Alameda County’s $1,249,125 high-balance conforming limit, so it is not a jumbo. At 7.17%, principal and interest run about $6,762 a month, and every eighth of a point is about $84.
Locally, supply eased. Board wide: 2,766 listings across the 15 city table, counting active and in contract together, with 195 coming soon and 311 brand new. The five city ledger carries 707 live listings across Fremont, Hayward, Milpitas, Newark and Union City, 616 already on the market and 91 coming soon, down from 720 on Friday even with 116 arriving in the past week.
Fremont holds 264 live listings, 200 active, 39 coming soon and 25 brand new, with a median on market list price of $1,249,000 at $824 a square foot and a typical active listing 27 days out. Behind it: Hayward 178, Milpitas 123, Newark 85 and Union City 57. Across all five cities the median is $1,099,450 at $696 a square foot, 267 homes are under a million, and 160 have been sitting 60 days or longer.
Buyers in contract should talk to their lender about locking before Wednesday’s Fed decision. For sellers, 160 homes past the 60 day mark says price for a 7% market, not a 6% one.
S&P 500: 7,656.98 +0.86% | Dow: 52,573.29 +0.98% | Nasdaq: 26,333.04 +0.96%
Friday snapped a four day losing streak, all three indexes up close to 1%. Monday is giving a little back: at 11:19 AM PT the S&P was down 0.28%, the Dow 0.26% and the Nasdaq 0.13%.
Dell was Friday’s star, up 11.98% to a record $567.29 after RBC Capital Markets started coverage at outperform with a $640 target, pointing to the AI server business.
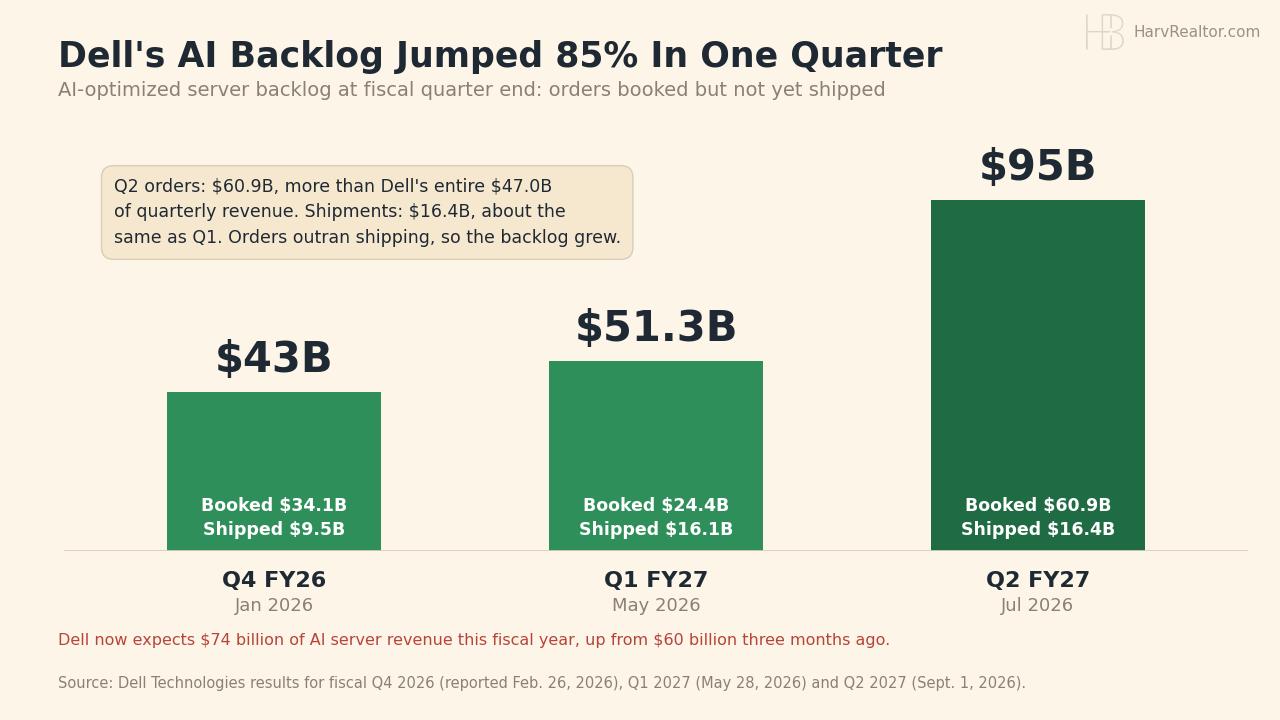
The chart making the rounds is right on the numbers. Dell’s AI server backlog went from $43 billion in January to $51.3 billion in May to $95 billion at the end of July. Nearly doubled is a stretch; it rose 85% in a quarter. Our version adds the why: Dell booked $60.9 billion of AI server orders, more than its entire $47.0 billion of revenue, while shipping $16.4 billion, about the same as the quarter before, and it raised its AI server forecast for the year to $74 billion from $60 billion.
Oracle went the other way. A filing Friday showed Larry Ellison planned to sell up to 50 million shares, about $7.5 billion; on Saturday he canceled the plan, and Oracle says none were sold. The stock fell 1.74% Friday and was down about 4.5% Monday.
10-Year Treasury: 4.96% +0.01 | Gold: $4,408.90 +1.16% | Silver: $65.19 +1.72% | Brent: $104.61 -2.81%
Inflation is the story. Consumer prices rose 0.4% in August and 3.4% over the past year. Energy did most of the damage: the energy index is up 16.3% in a year, gasoline 27.4% and fuel oil 52%. Strip out food and energy and core prices are up 2.4%, the lowest reading this year.
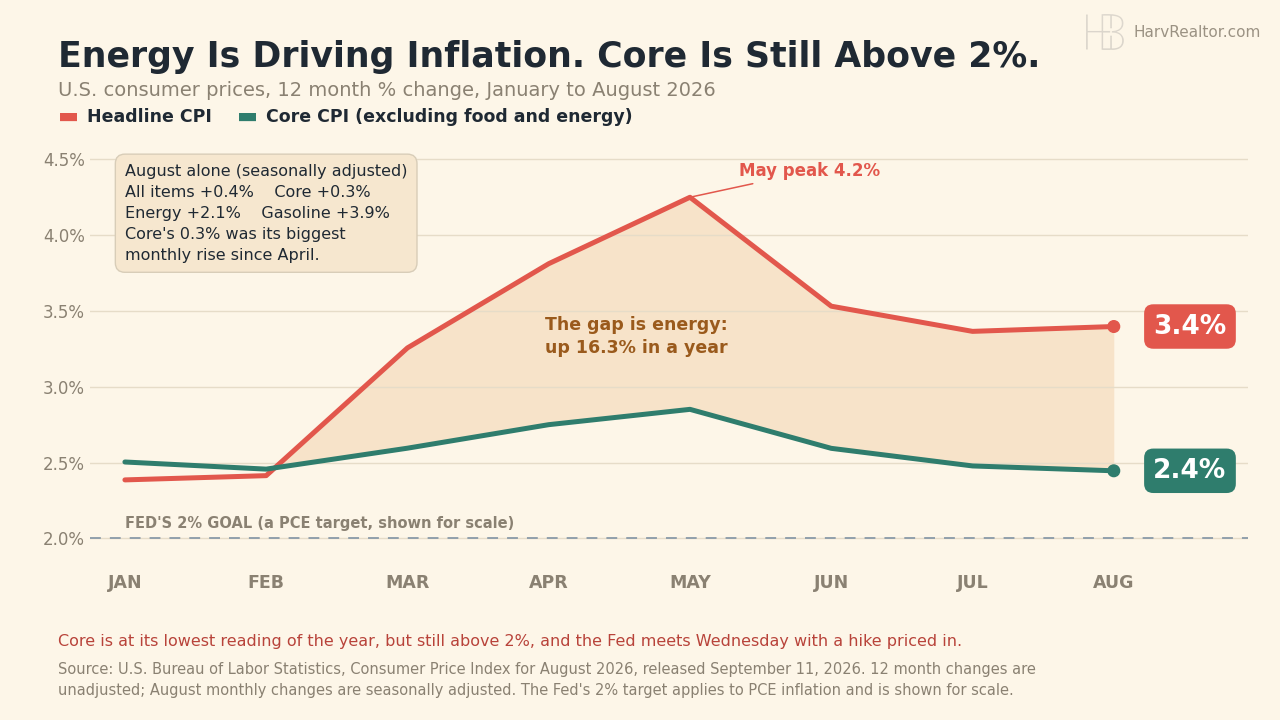
The chart making the rounds matches BLS on all sixteen points. Its headline is right about the year: the gap between the lines is energy. It leaves out the month. Core rose 0.3% in August, its biggest monthly gain since April, and at 2.4% it is still above the Fed’s 2% goal (a goal set for a different gauge, PCE, so read it as a yardstick). That is why markets expect a hike Wednesday, not a cut.
Oil eased, metals bounced. Brent settled at $104.61 Friday, down 2.8% after Thursday’s jump to $107.63, and was trading near $105.66 Monday. At Friday’s 1:00 PM PT print gold rose 1.2% to $4,408.90 and silver 1.7% to $65.19; both were lower again Monday morning.
A note on today’s newsletter numbers: its stock, CPI and fuel oil figures check out. It had the 10-Year at 4.97% against Treasury’s 4.96%, gold down 0.51% where the same time prints show a 1.16% gain, and Brent up 2.66% at $107.39 where the settlement was $104.61, down 2.81%. Its mortgage rates were Friday’s, its 90% Fed odds run above the 84.5% prediction markets show, and silver was left out again.
Bitcoin: $78,858 +1.96% | Ethereum: $2,531.21 +0.97% | XRP: $1.44 +6.05%
Live quotes pulled at 11:17 AM PT with 24 hour changes. All three are higher, and XRP leads, up about 6%.
The Senate holds a procedural vote on the Clarity Act Tuesday at 11:15 AM PT. The bill would decide which regulator oversees which coins and exchanges, and it needs 60 votes, so even with every Republican it needs at least seven Democrats or independents. Meanwhile Italy’s UniCredit, with more than 20 million customers, is picking a technology partner to hold and trade digital assets for its clients, Bloomberg reported Friday.
Sources
- Mortgage News Daily (30 and 15 year fixed, September 14)
- Alameda County 2026 conforming loan limits (high-balance limit $1,249,125)
- U.S. Treasury daily yield curve (10 year, September 11)
- U.S. Bureau of Labor Statistics (Consumer Price Index for August 2026, released September 11)
- Dell Technologies Q2 fiscal 2027 results, Q1 fiscal 2027 and Q4 fiscal 2026
- CNBC (RBC on Dell) and DELL daily closes
- CNBC (Larry Ellison and Oracle)
- DeFi Rate (Kalshi and Polymarket Fed odds, 10:48 AM PT September 14)
- ICE Brent front month (settlement, September 11)
- COMEX gold and silver front month (1:00 PM PT prints, September 10 and 11)
- PYMNTS (Clarity Act vote) and CryptoPotato (UniCredit)
- CoinGecko (Bitcoin, Ethereum and XRP, live at 11:17 AM PT September 14)
- REALTY EXPERTS® Live Inventory (five city ledger, September 14)
Disclaimer: The market data, rates, and information provided are for informational purposes only and should not be considered financial advice. Always verify rates and data with your lender or financial advisor before making any decisions.