



"At a Glance" Local Housing STATS and News 09/11/26
September 11, 2026 · Alameda County Market Dashboard
TODAY'S LIVE INVENTORY
Behind these county totals: hundreds of homes still for sale in Fremont, Hayward, Union City, Newark and Milpitas, counted, priced and sorted every morning from the same MLS export, with a map search for the homes themselves.
30-Year Fixed: 7.07% unchanged | 15-Year Fixed: 6.62% unchanged
Rates are holding at 7%, for now. Mortgage News Daily still has the 30-year at 7.07% and the 15-year at 6.62%, Thursday’s readings and the highest in at least a year. Friday’s numbers post around 1 PM PT, and the setup is not friendly: the 10-Year jumped 0.12 on Thursday to 4.95%, its highest close since at least January 2024, and mortgage rates follow the 10-Year.
The Fed is the reason. Wholesale prices ran hot, and traders now put 85.6% odds on a quarter-point hike next Wednesday, per CME FedWatch. The Fed does not set mortgage rates, but it keeps the pressure on the bond yields that do. At Fremont’s median list price of $1,249,000, a 20% down loan is $999,200, which is jumbo; at MND’s jumbo 30-year of 7.20%, principal and interest run about $6,782 a month, and every eighth of a point is about $85 more.
Locally, supply jumped. Board wide: 2,760 listings across the 15 city table, counting active and in contract together, with 187 coming soon and 255 brand new. The five city ledger carries 720 live listings across Fremont, Hayward, Milpitas, Newark and Union City, 631 already on the market and 89 coming soon, up from 696 yesterday with 115 arriving in the past week.
Fremont holds 272 live listings, 206 active, 37 coming soon and 29 brand new, with a median on market list price of $1,249,000 at $825 a square foot and a typical active listing 25 days out. Behind it: Hayward 183, Milpitas 123, Newark 88 and Union City 54. Across all five cities the median is $1,098,888 at $698 a square foot, 278 homes are under a million, and 156 have been sitting 60 days or longer.
Buyers have more to choose from; the pressure is on the payment, not the selection. Buyers in contract should talk to their lender about locking before Wednesday’s Fed decision. For sellers, 156 homes past the 60 day mark says price for a 7% market.
S&P 500: 7,591.70 -0.58% | Dow: 52,064.10 -0.60% | Nasdaq: 26,081.72 -0.65%
Twenty-five years ago today, nearly 3,000 people lost their lives in the September 11 attacks. We remember them, their families, and the first responders.
Thursday made it four losing sessions in a row, each index down about six tenths of a percent. Friday opened with a bounce: at 9:02 AM PT the S&P was up 1.08%, the Dow 1.04% and the Nasdaq 1.24%.
Taiwan Semiconductor had the record of the day. TSMC’s August revenue came in at NT$514.8 billion, up 53.3% from a year ago and 10.1% above July, its fourth straight monthly gain and its first month above NT$500 billion. That is about US$16.1 billion at August’s average exchange rate of 32.0 Taiwan dollars per dollar; the newsletter’s $16.4 billion assumes a stronger Taiwan dollar. AI chip demand is the whole story.
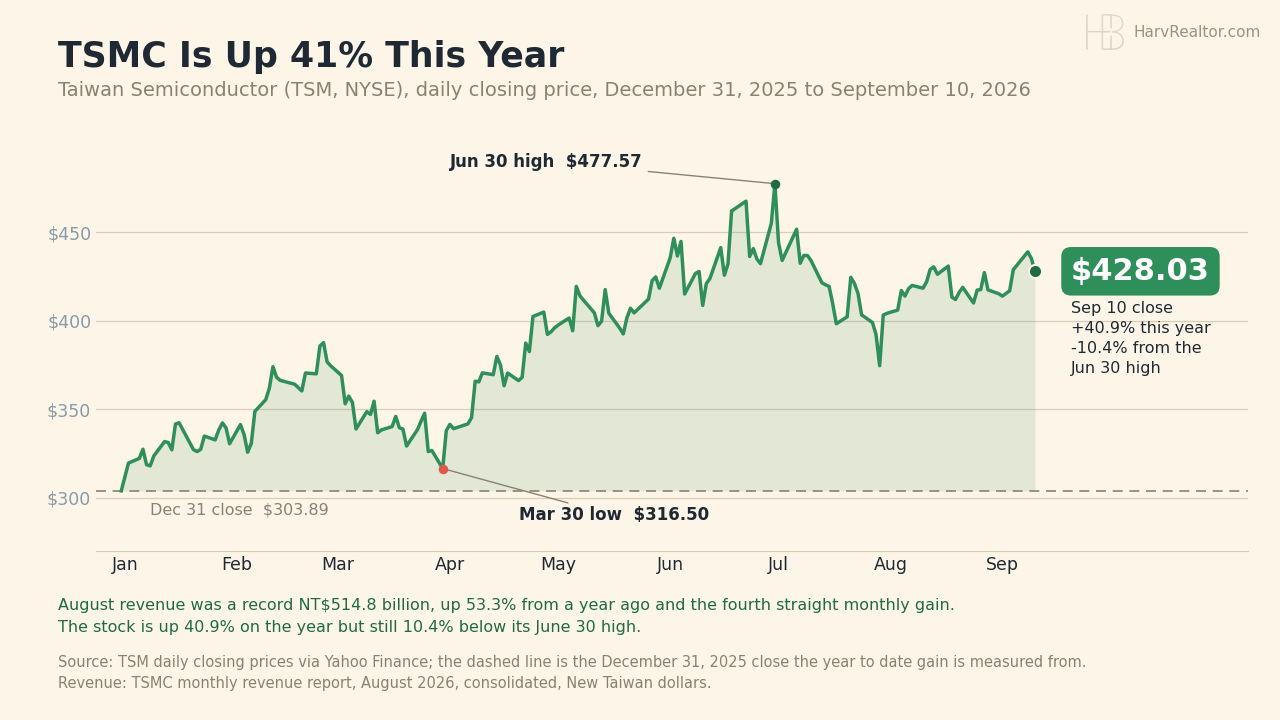
The chart making the rounds checks out to the cent. TSM closed Thursday at $428.03, up 40.9% from its December 31 close of $303.89. Our version adds the two things the original leaves out: the baseline that 41% is measured from, and the fact that the stock is still 10.4% below its June 30 high of $477.57. The shares were up about 1.6% Friday morning.
10-Year Treasury: 4.95% +0.12 | Gold: $4,358.50 -1.99% | Silver: $64.09 -5.65% | Brent: $107.63 +6.34%
Wholesale prices are the story. The Producer Price Index rose 0.4% in August and 5.4% over the past year. Energy drove the month: final demand energy rose 4.2%, diesel jumped 24.1%, and BLS says energy accounted for over three fourths of the rise in goods prices.
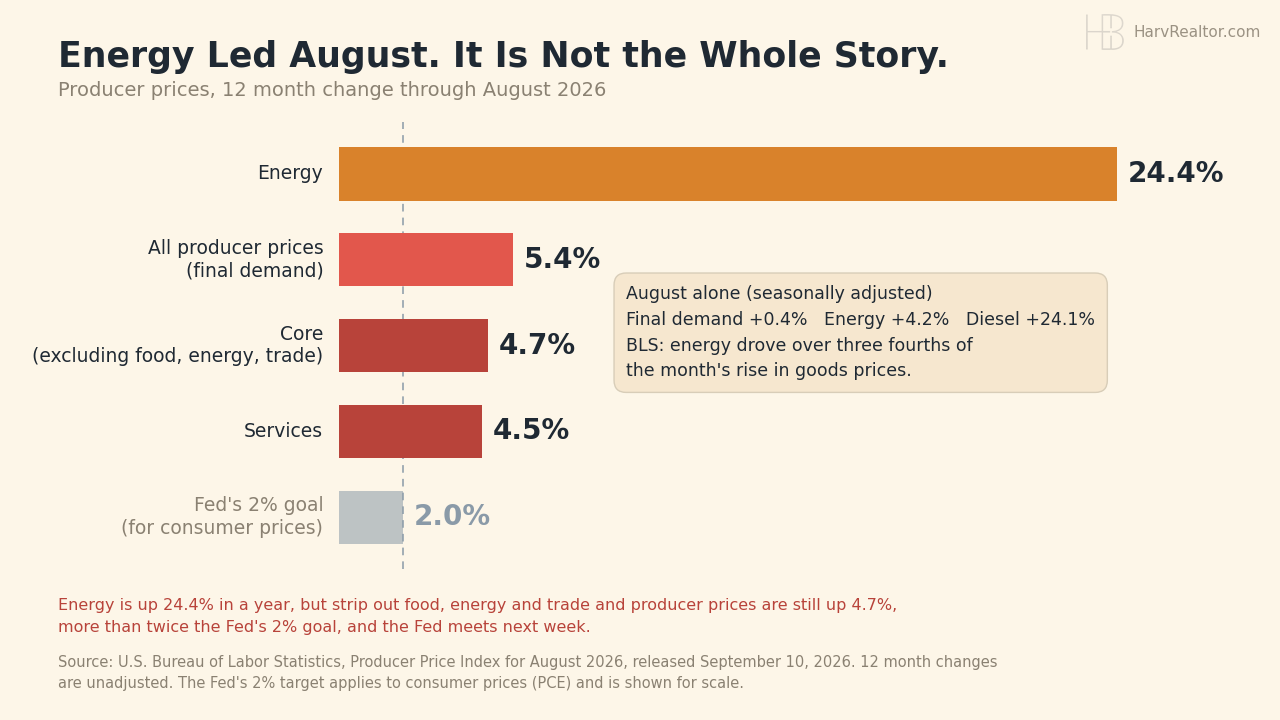
The chart making the rounds is right on the numbers. Its headline, energy did the heavy lifting, is true of August and less true of the year: take out food, energy and trade and producer prices are still up 4.7%, and services 4.5%, both more than twice the Fed’s 2% goal (a goal for consumer prices, so read it as a yardstick). That is why markets moved toward a hike: CME FedWatch puts the odds of a quarter-point increase next Wednesday at 85.6%, up from 48.4% on August 11.
Oil kept climbing, metals did not. Brent settled at $107.63 on Thursday, up 6.3% and its highest settlement since May 19, as Iran said it was ready for a wider conflict after the U.S. destroyed five of its tankers; it eased to about $104.74 Friday morning. At Thursday’s 1:00 PM PT print gold fell 2.0% to $4,358.50 and silver 5.6% to $64.09, and both were bouncing Friday morning.
A note on today’s newsletter numbers: its stock, rate and PPI figures check out, including diesel’s 24% jump. It had the 10-Year at 4.96% against Treasury’s 4.95%, gold down 2.29% where the same time prints show 1.99%, and Brent at $108.63 against the $107.63 settlement. Silver was left out again.
Bitcoin: $77,702 +0.63% | Ethereum: $2,559.75 +4.82% | XRP: $1.37 +1.28%
Live quotes pulled at 9:00 AM PT with 24 hour changes. All three are higher with Friday’s bounce, and Ether leads, up almost 5%.
Nasdaq’s venture arm is putting $100 million into Payward, the parent of the Kraken exchange, at a $21 billion valuation, to distribute tokenized versions of Nasdaq-listed stocks with a launch planned for 2027. And on Tuesday the Senate holds a procedural vote on the Clarity Act, which would decide which regulator oversees which coins and exchanges; it needs 60 votes, which means it needs some Democrats.
Sources
- Mortgage News Daily (30 and 15 year fixed and 30 year jumbo, September 10)
- U.S. Treasury daily yield curve (10 year, September 10)
- U.S. Bureau of Labor Statistics (Producer Price Index for August 2026, released September 10)
- TSMC monthly revenue and August 2026 revenue report
- TSM daily closes (December 31, 2025 to September 10, 2026)
- 24/7 Wall St. (CME FedWatch odds, September 11)
- ICE Brent front month (settlement, September 10) and Bloomberg (Iran and oil)
- COMEX gold and silver front month (1:00 PM PT prints, September 9 and 10)
- CNBC (Nasdaq and Payward) and Yahoo Finance (Clarity Act vote)
- CoinGecko (Bitcoin, Ethereum and XRP, live at 9:00 AM PT September 11)
- REALTY EXPERTS® Live Inventory (five city ledger, September 11)
Disclaimer: The market data, rates, and information provided are for informational purposes only and should not be considered financial advice. Always verify rates and data with your lender or financial advisor before making any decisions.