



"At a Glance" Local Housing STATS and News 08/26/26
August 26, 2026 · Alameda County Market Dashboard
TODAY'S LIVE INVENTORY
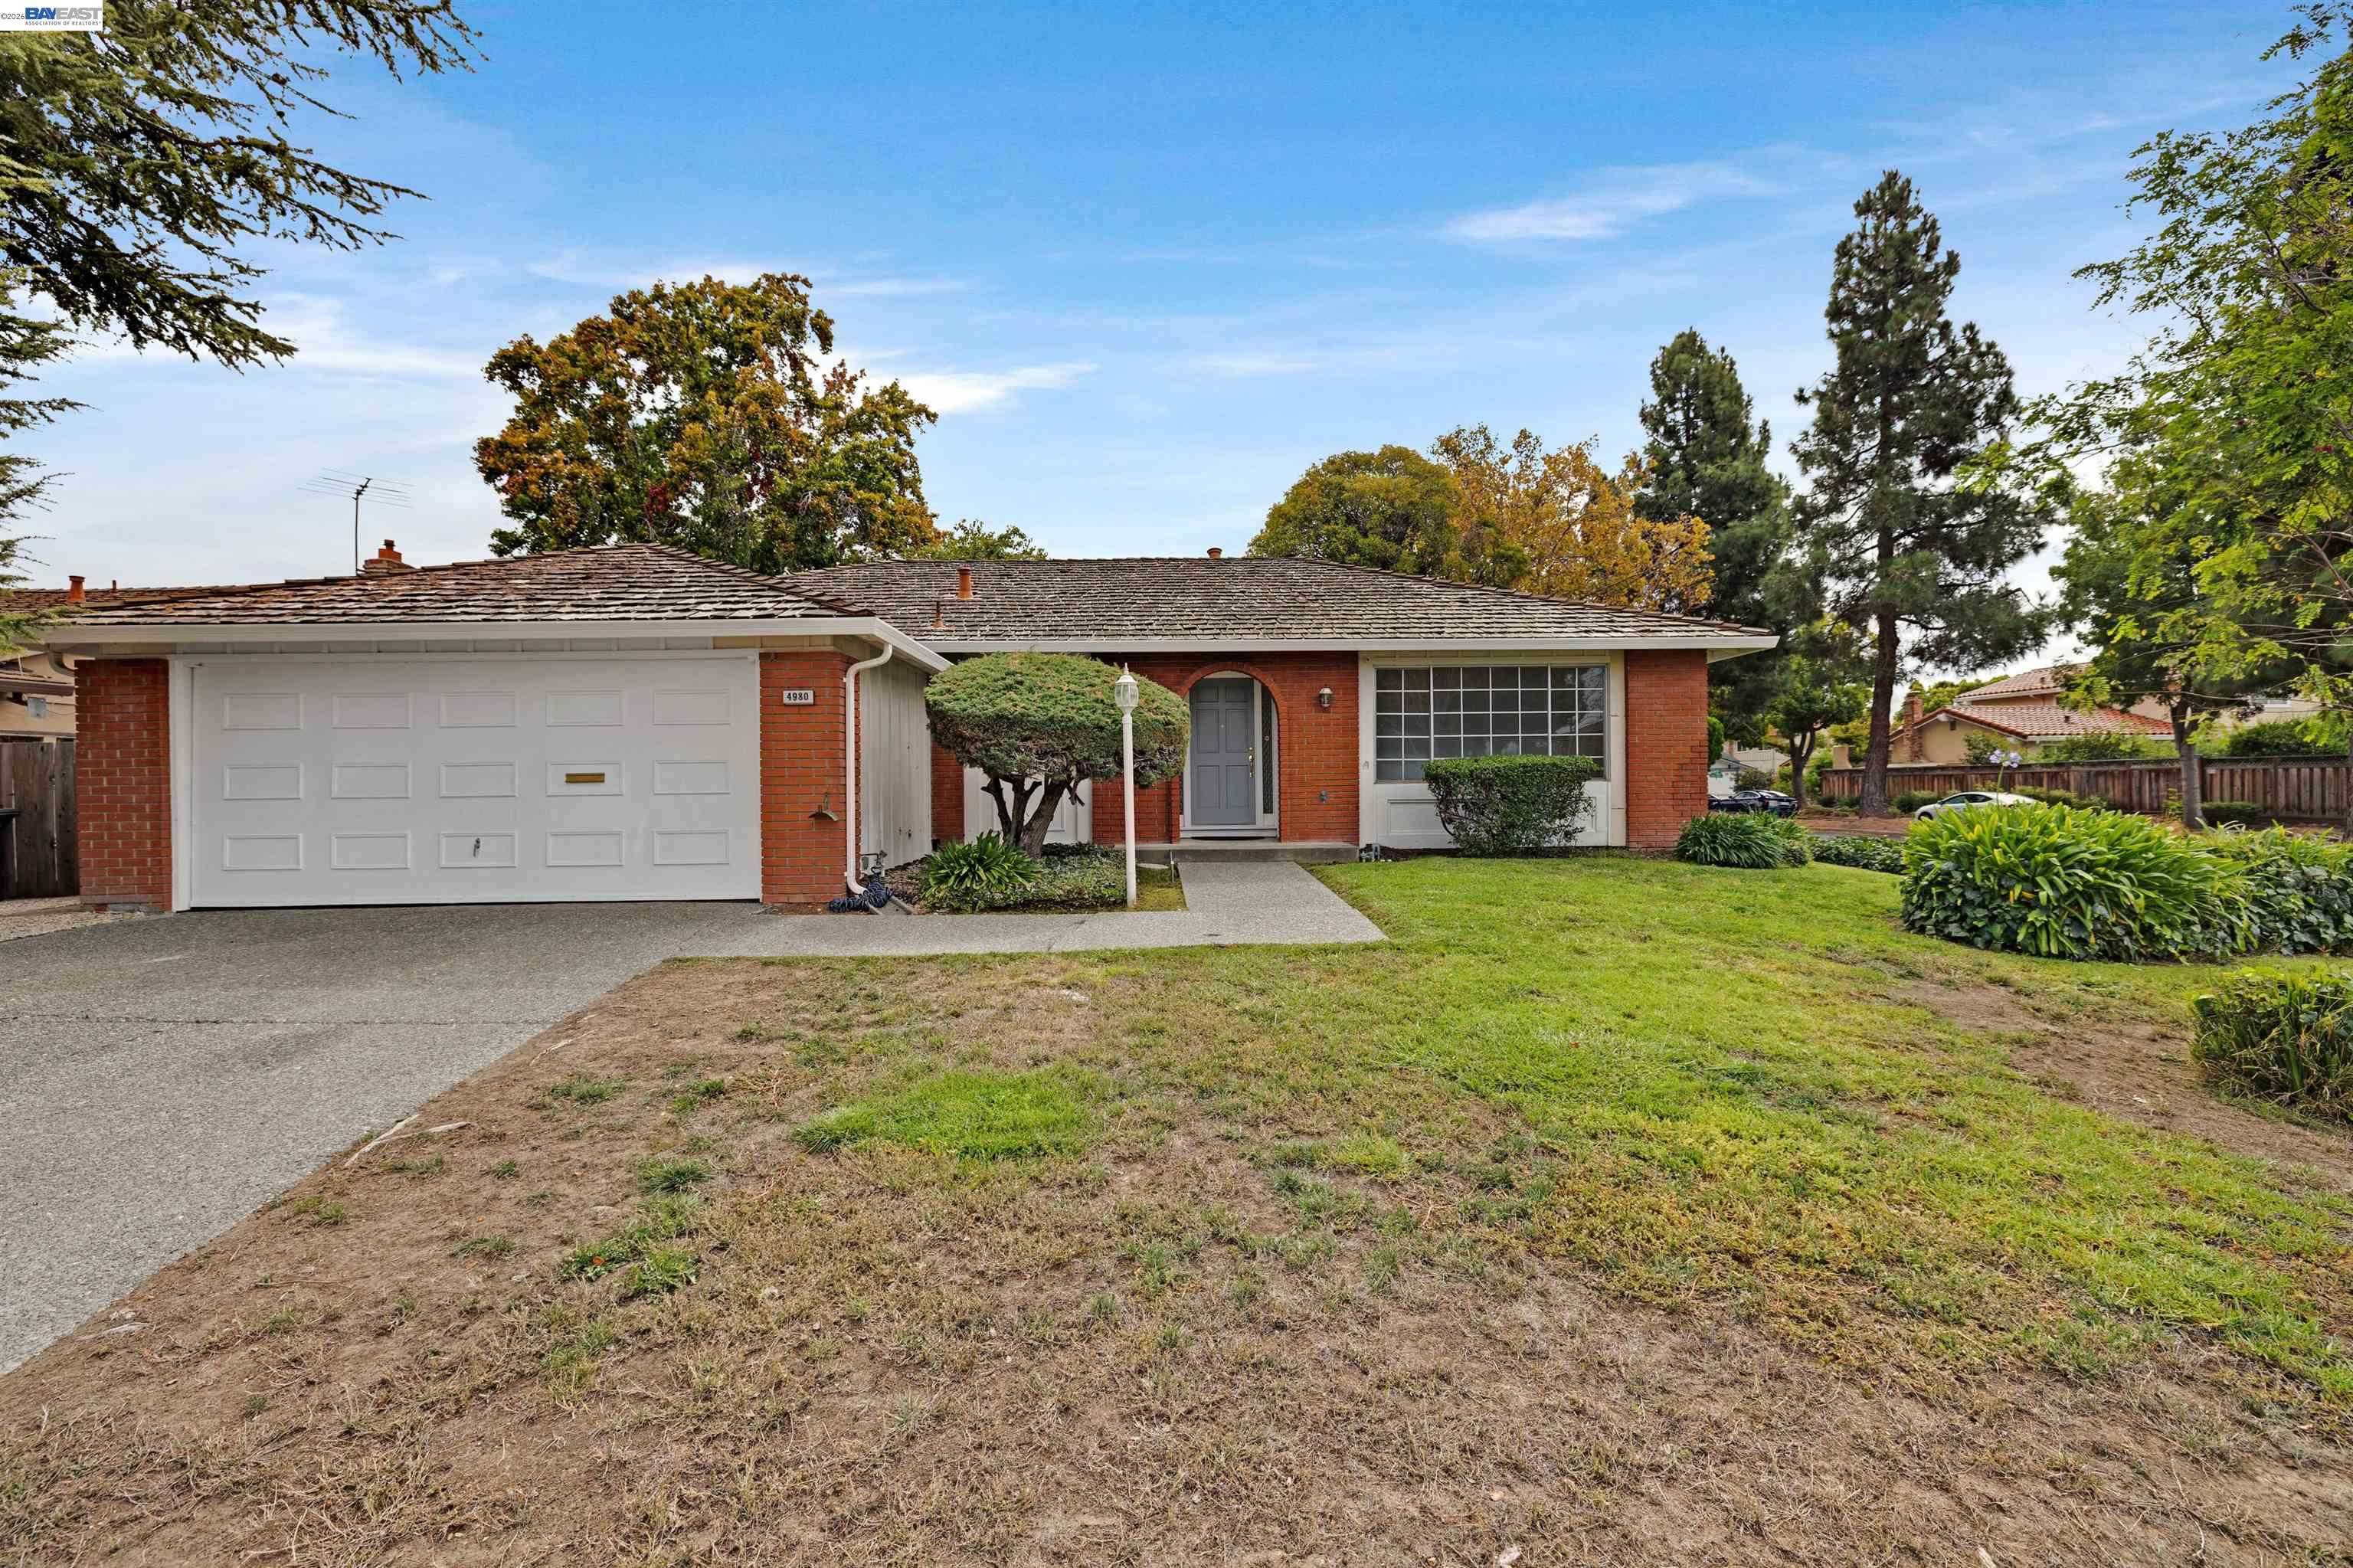
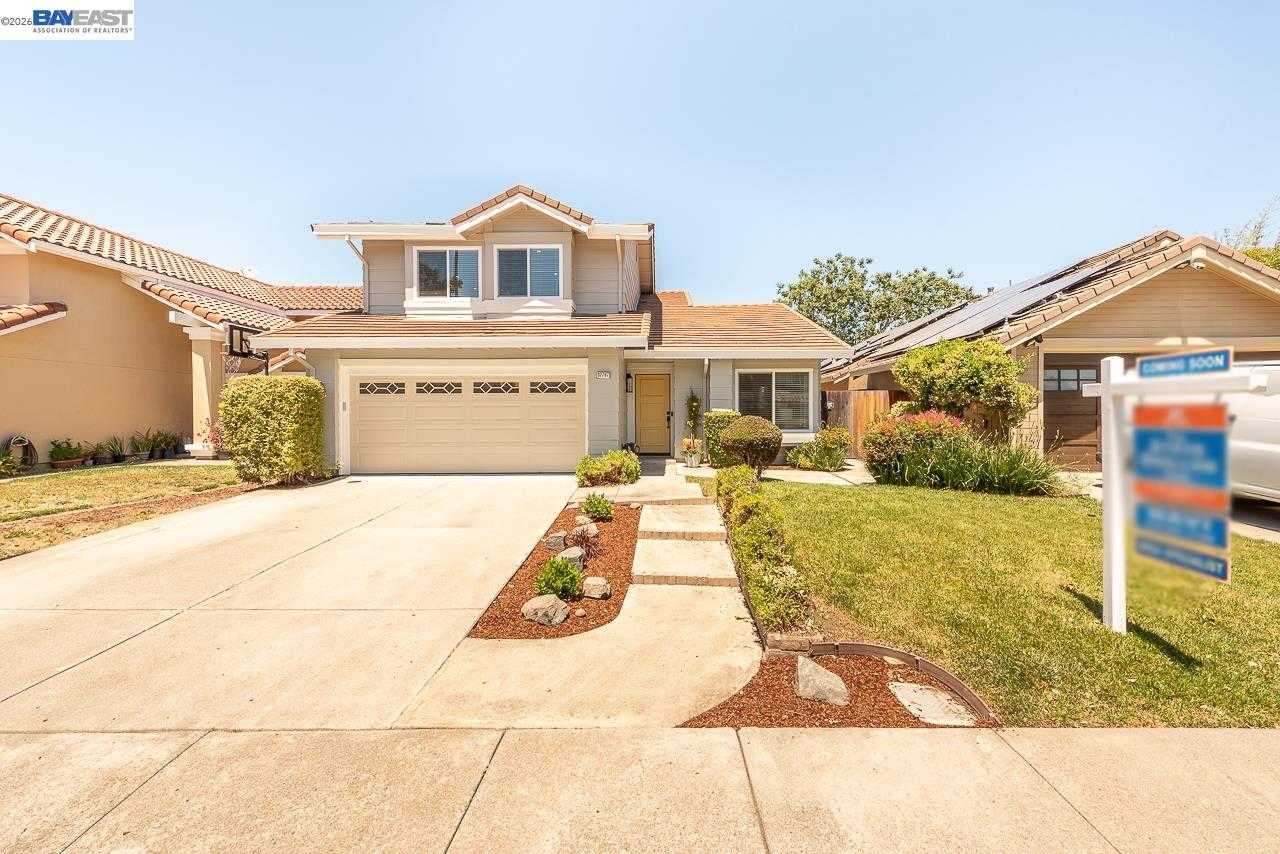
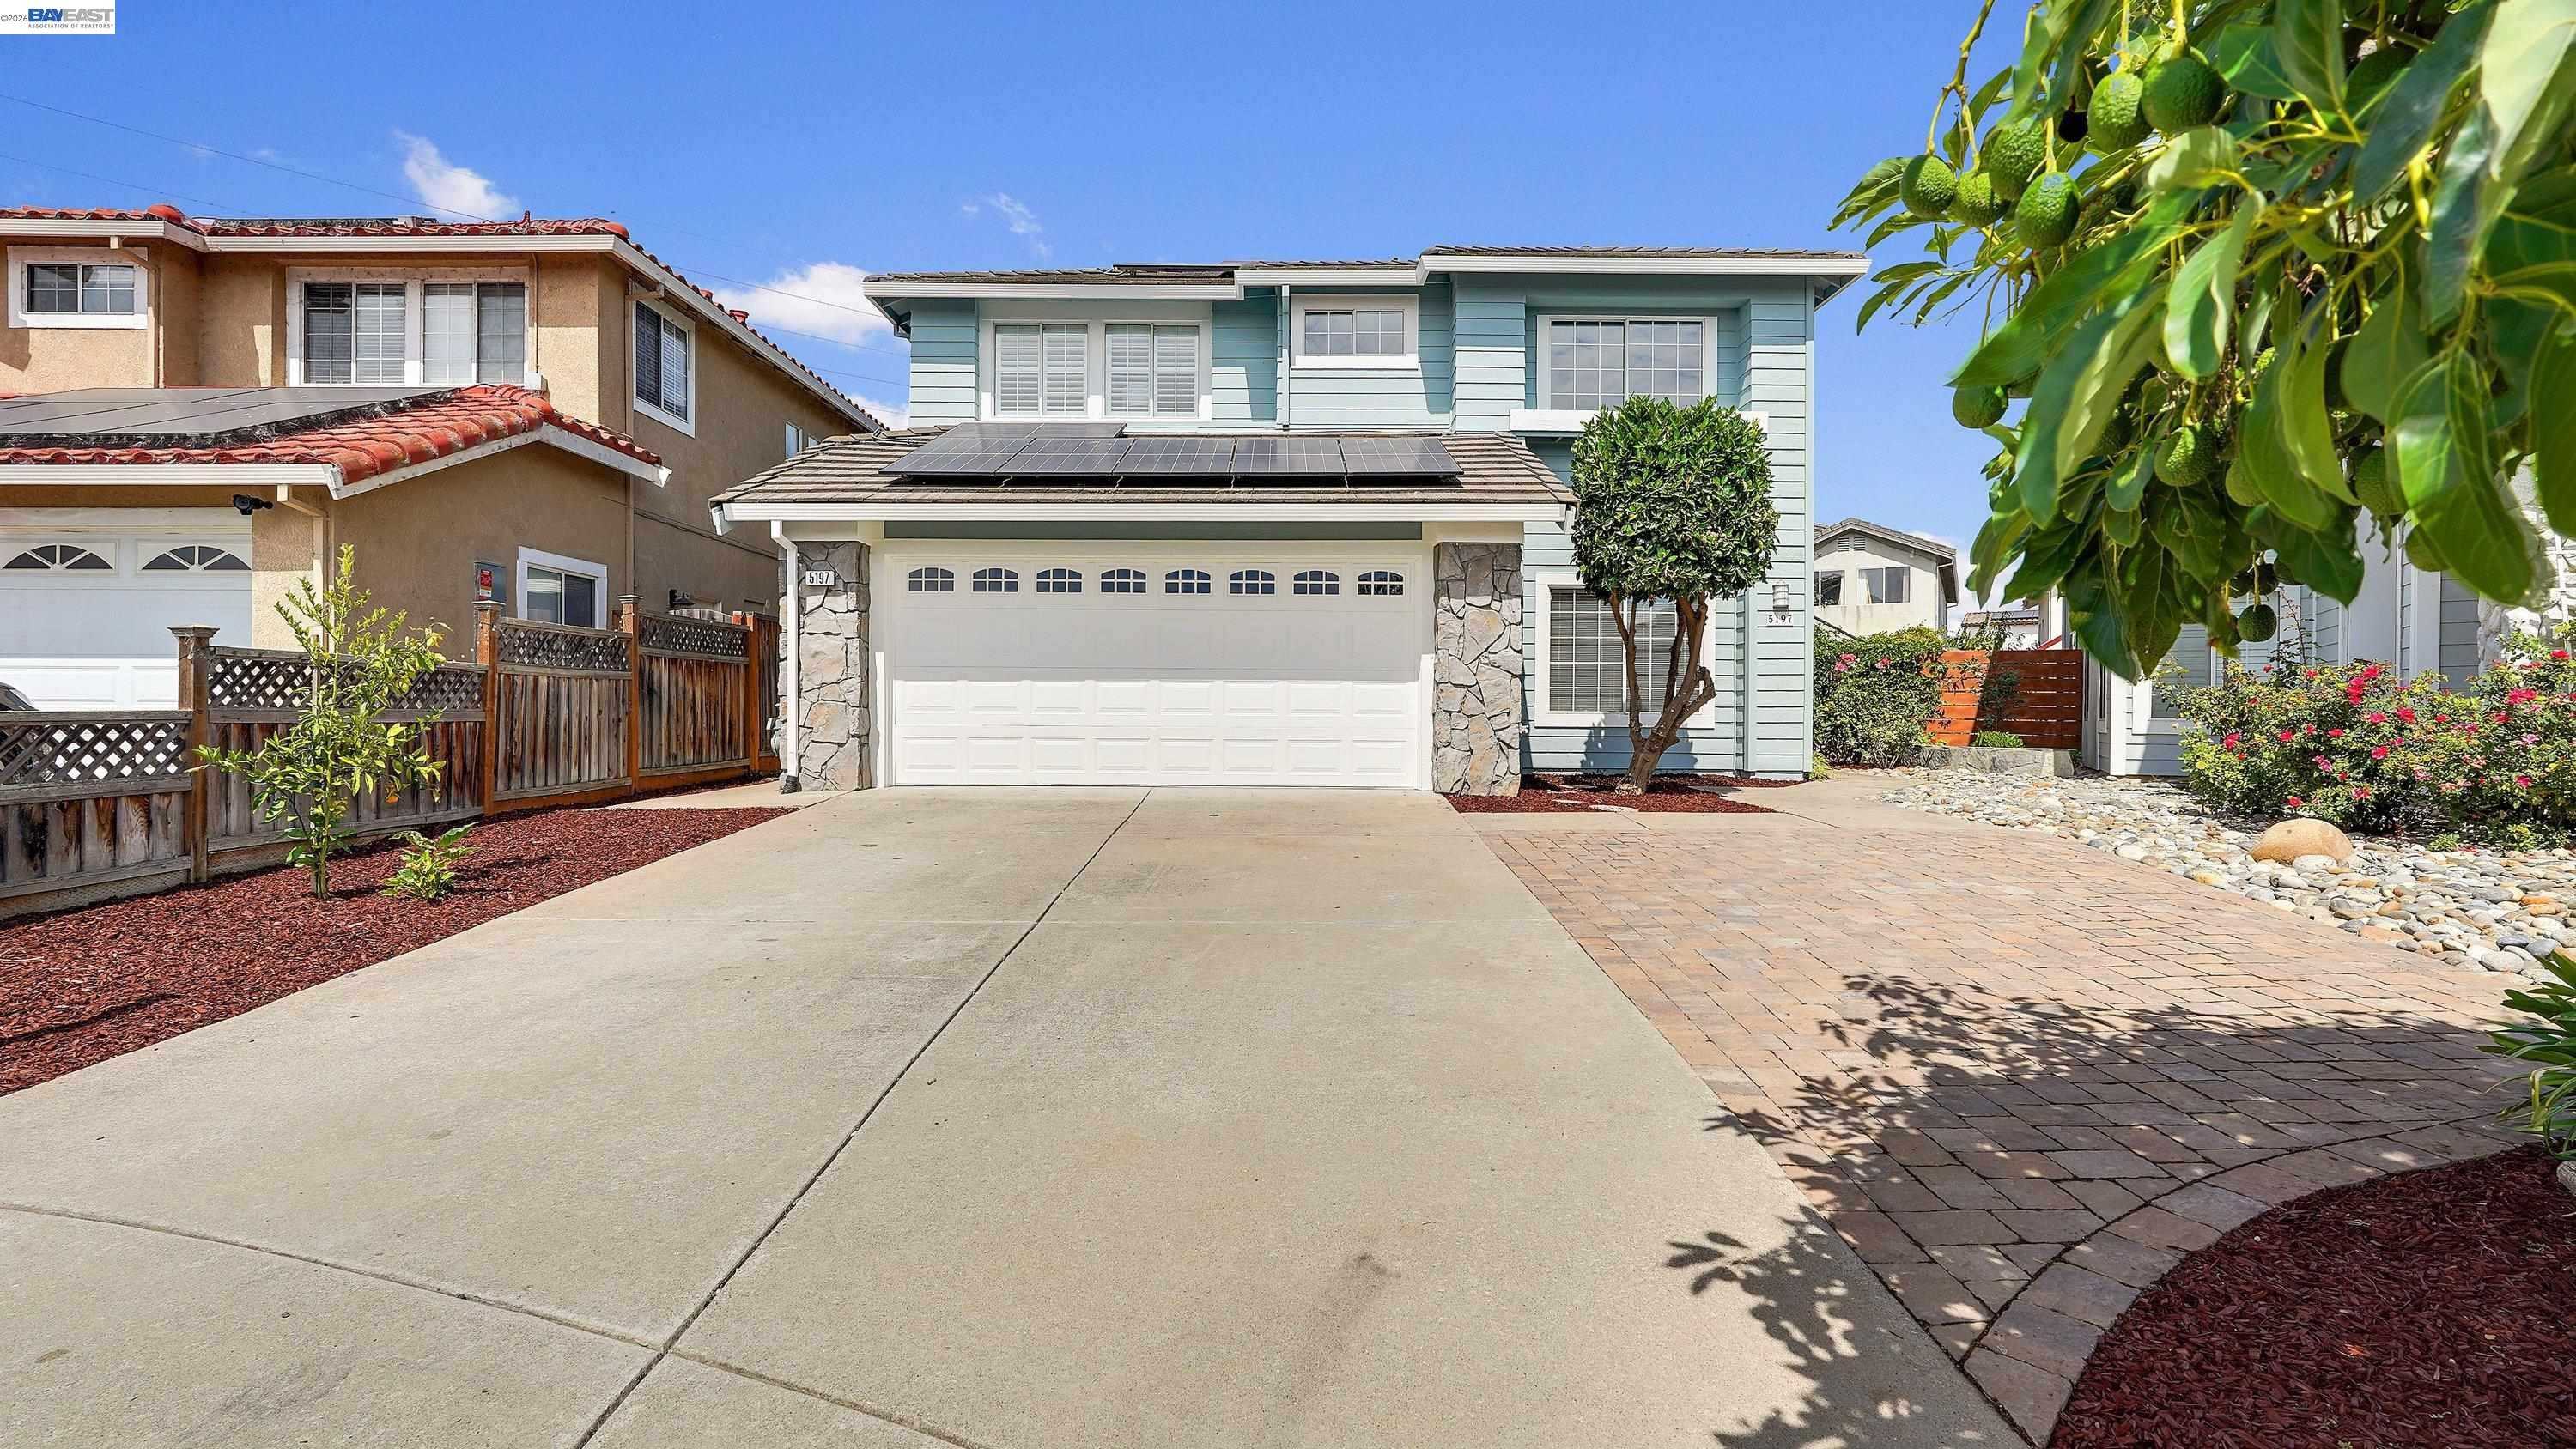
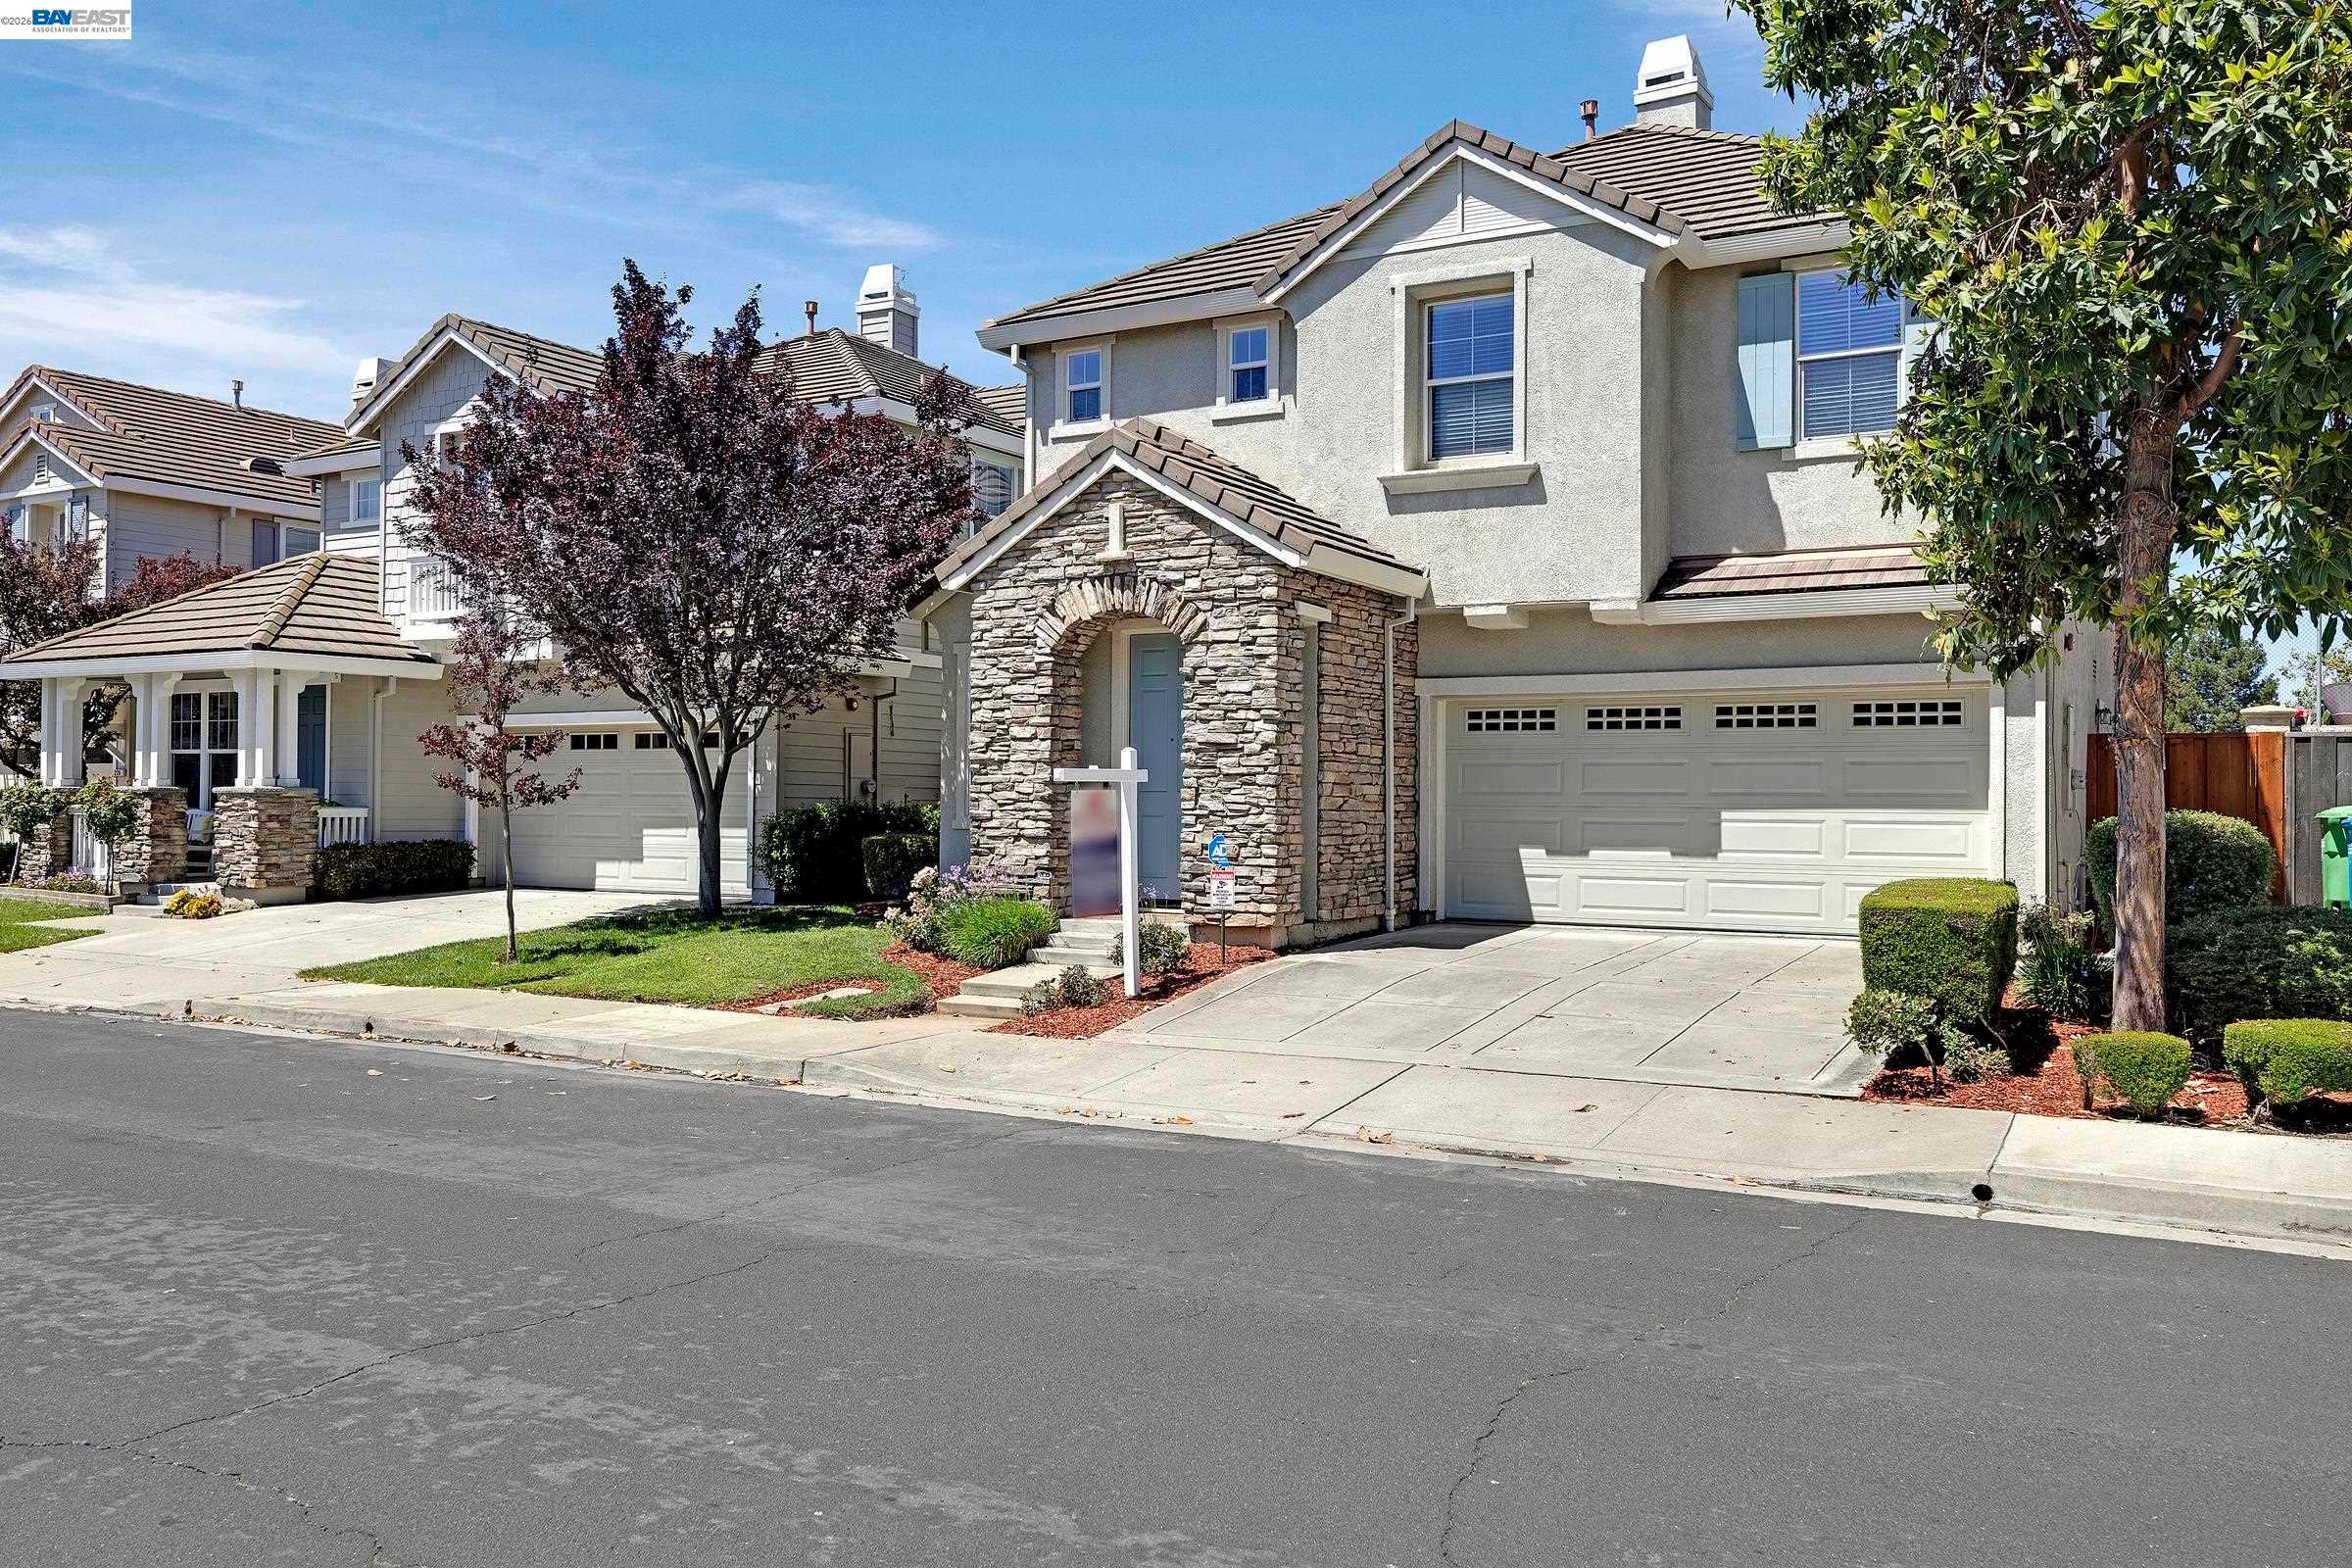
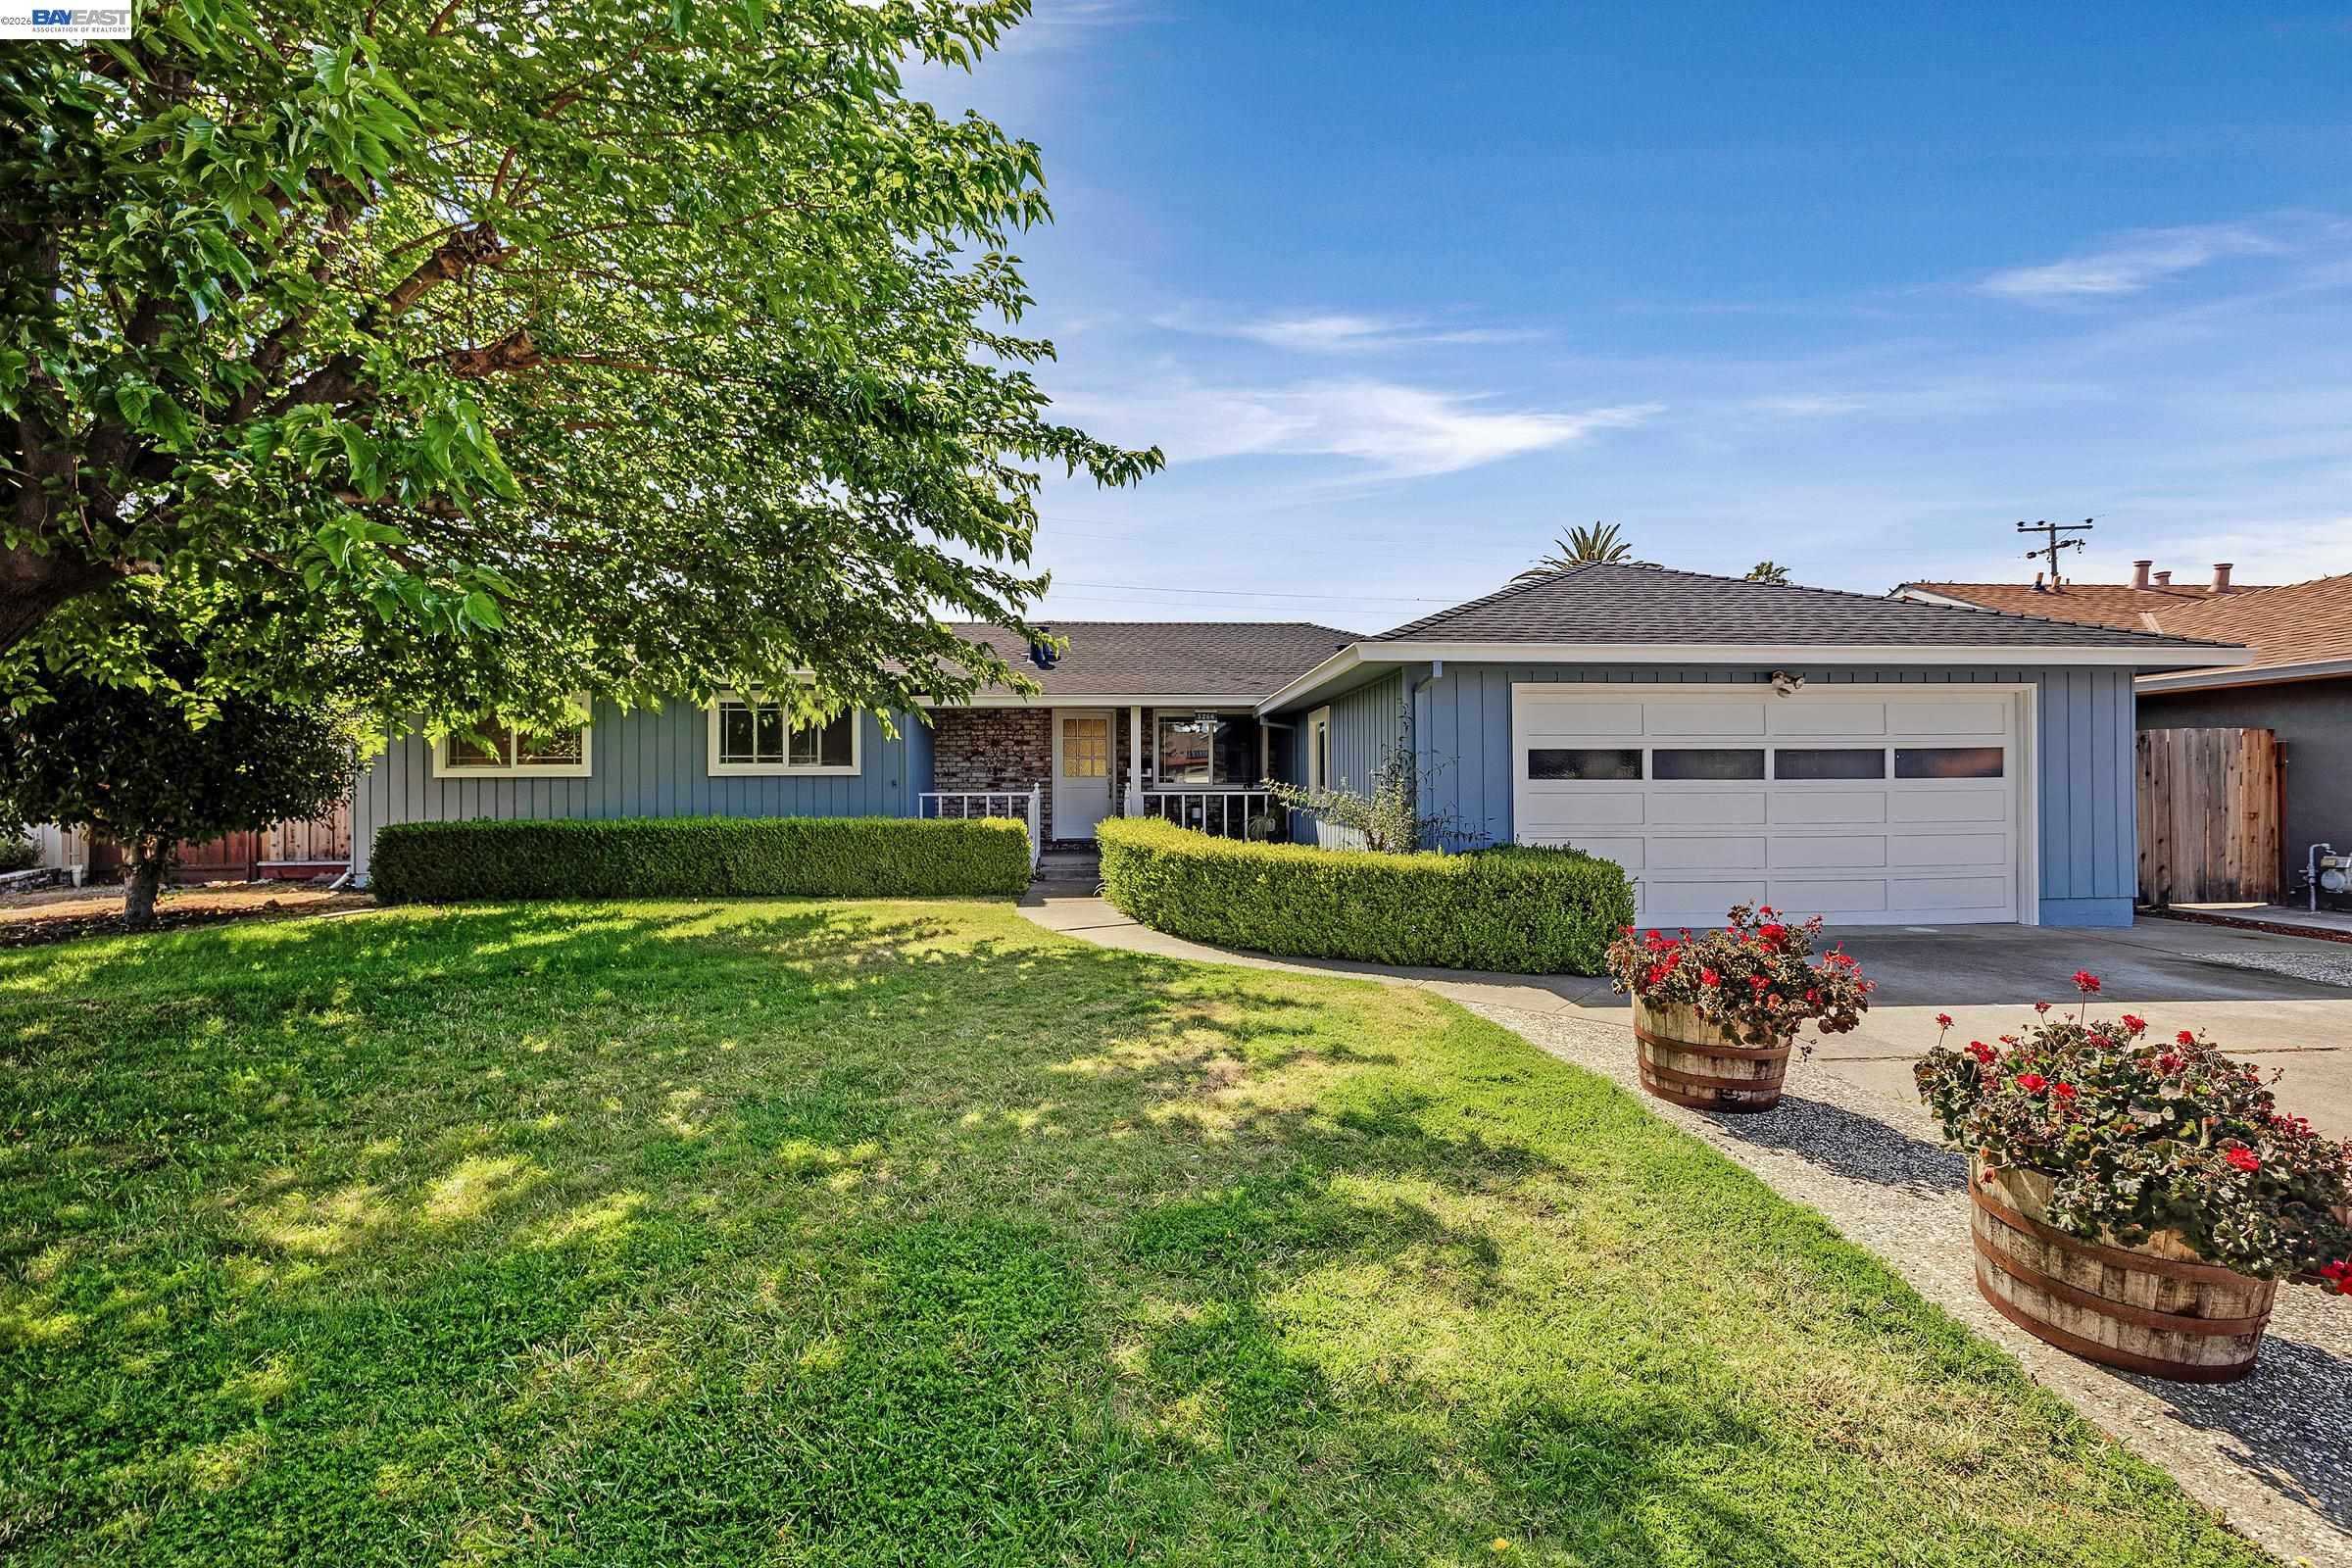
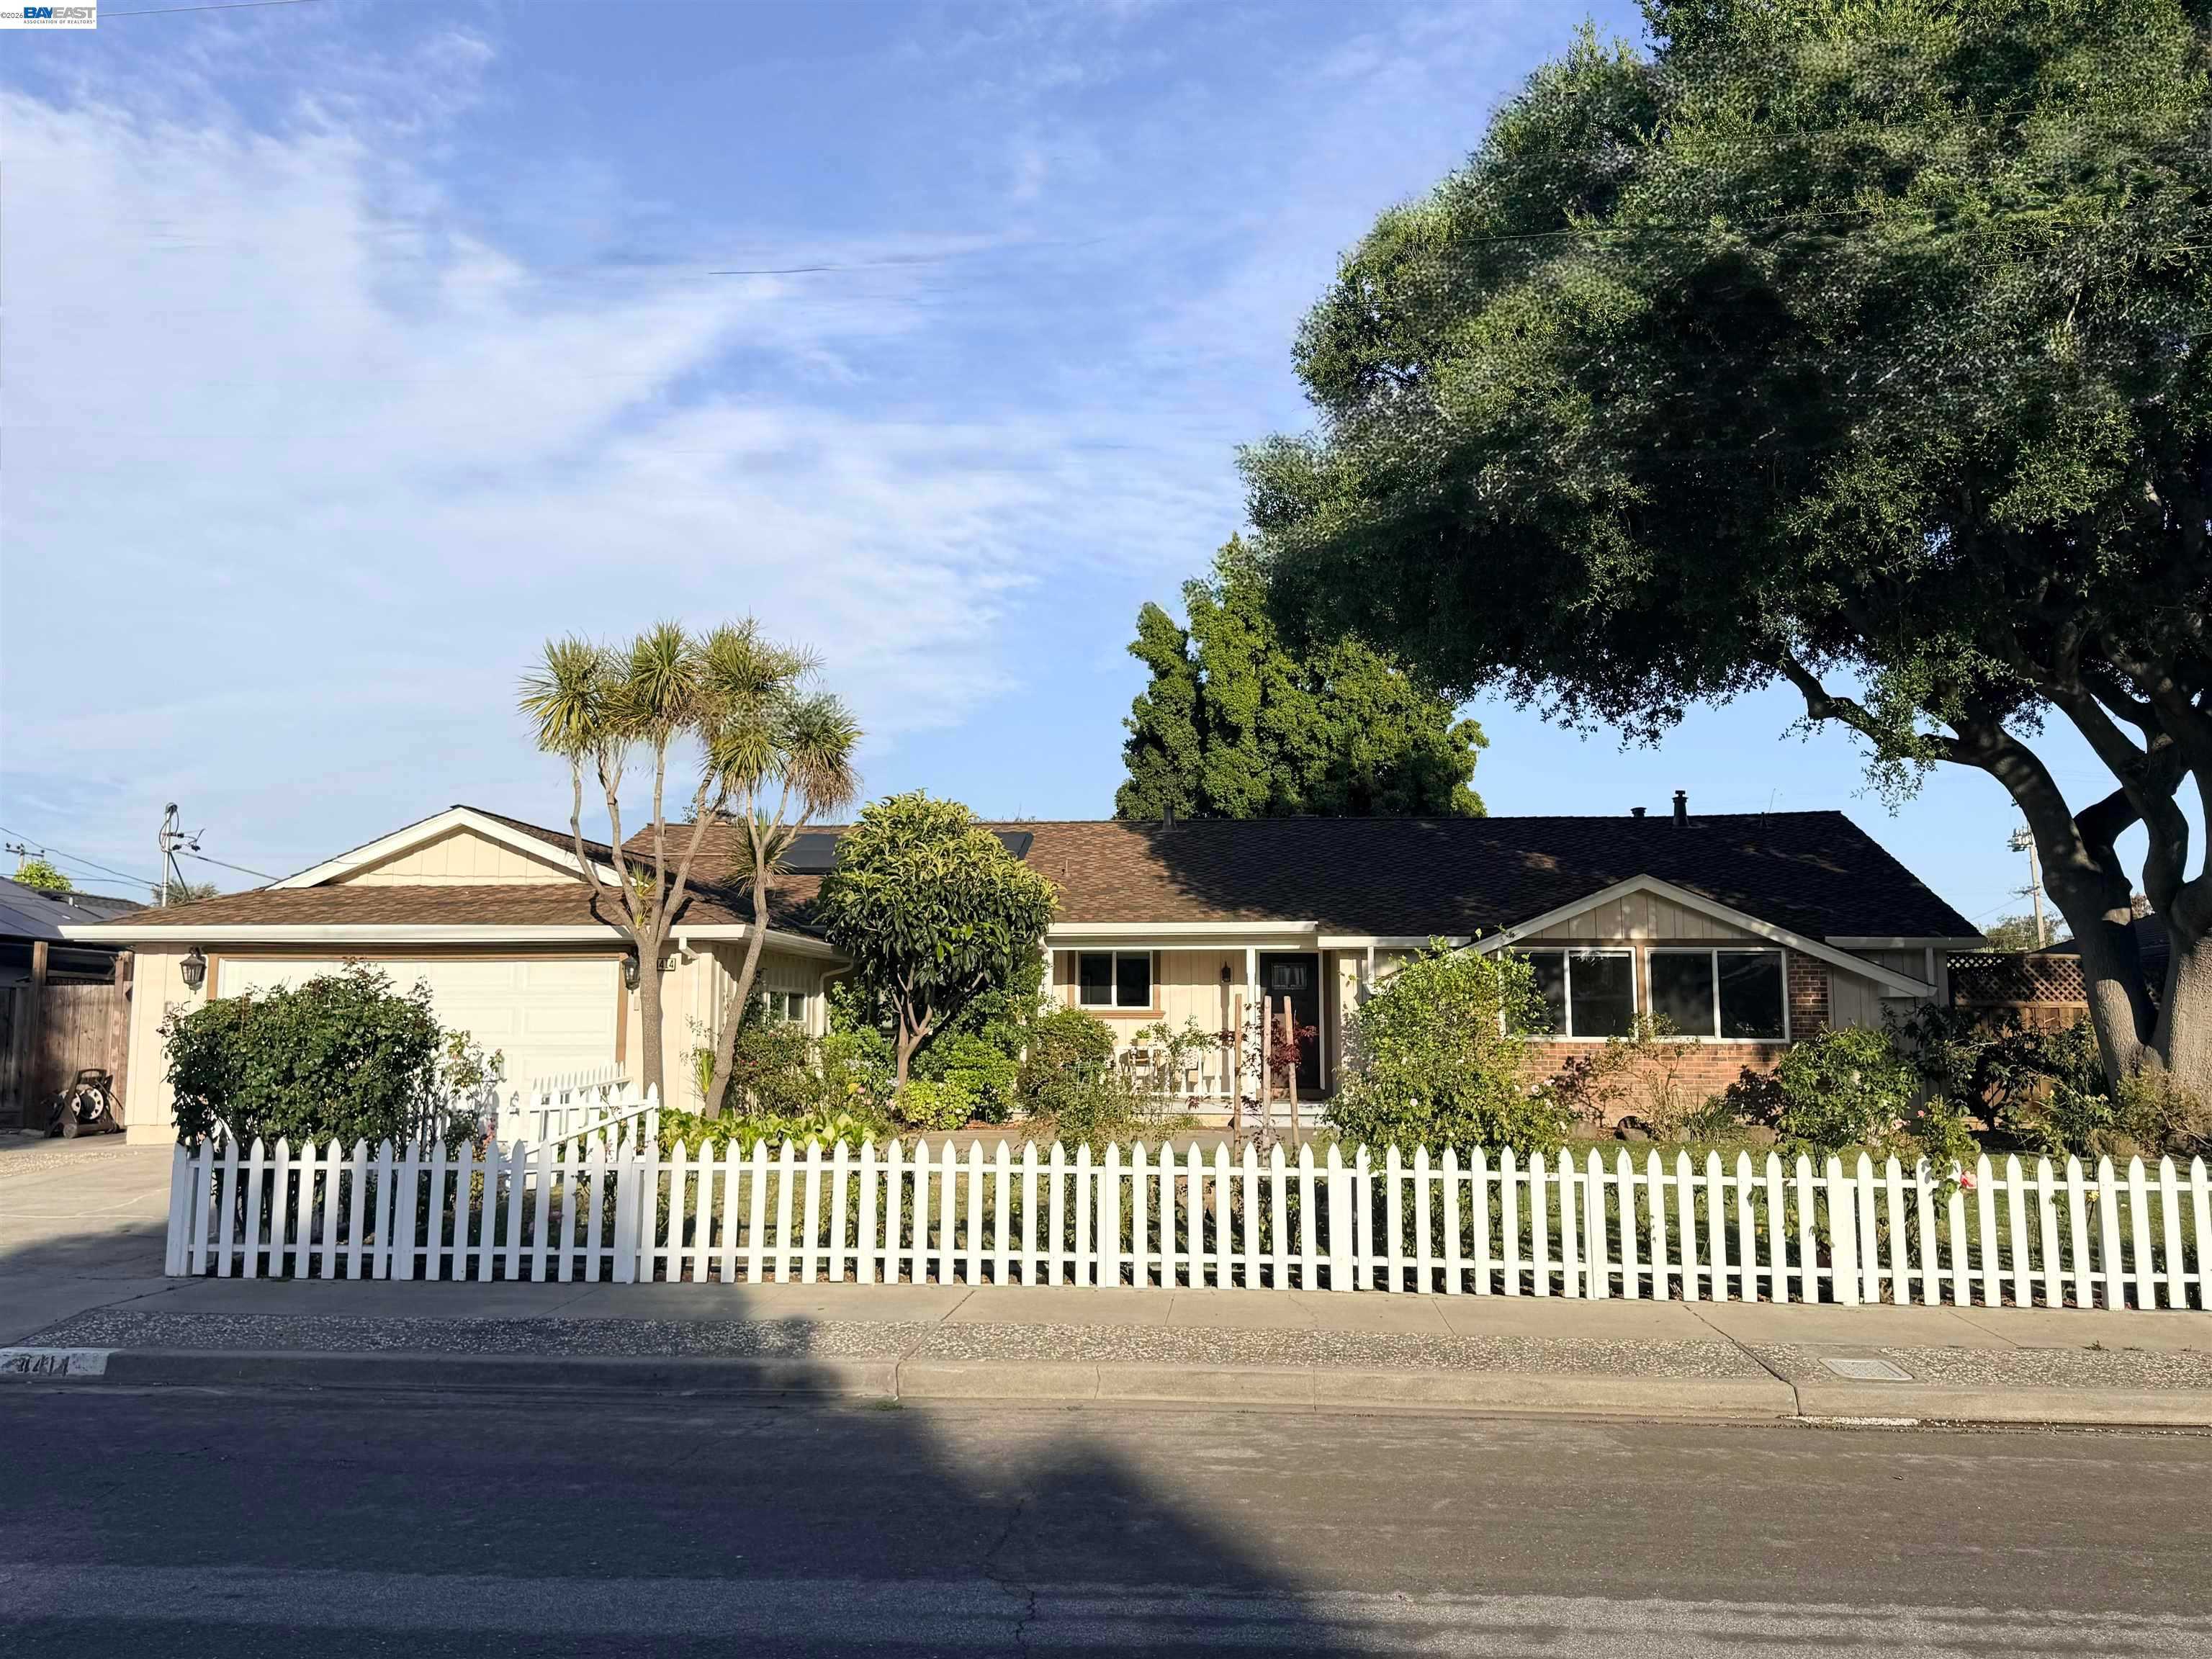
Behind these county totals: hundreds of homes still for sale in Fremont, Hayward, Union City, Newark and Milpitas, one live ledger with prices, sizes and a market read, refreshed each morning from the same MLS export.
30-Year Fixed: 6.75% ▲ 0.01% | 15-Year Fixed: 6.32% ▲ 0.01%
The 15-year flag comes down, and the reason matters. For three sessions we carried the 15-year at 6.62% and said plainly that it did not add up, because it left just 16 basis points between the 15-year and the 30-year where the normal gap is nearer 70. Mortgage News Daily has now revised its own history. Its board today reads 6.27%, 6.30%, 6.31%, 6.32%, 6.31% and 6.32% across the last six sessions, so Friday's 31 basis point jump has been erased from the record. Today's 6.32% is not a collapse in the 15-year, it is the correction of a bad print, and the spread to the 30-year is back to a normal 43 basis points. You can quote the 15-year again.
Cash is loosening its grip. All cash purchases fell to 31.4% of sales from 32.3% a year ago. Every point that leaves the cash column is a point where a financed buyer competes on more even footing.
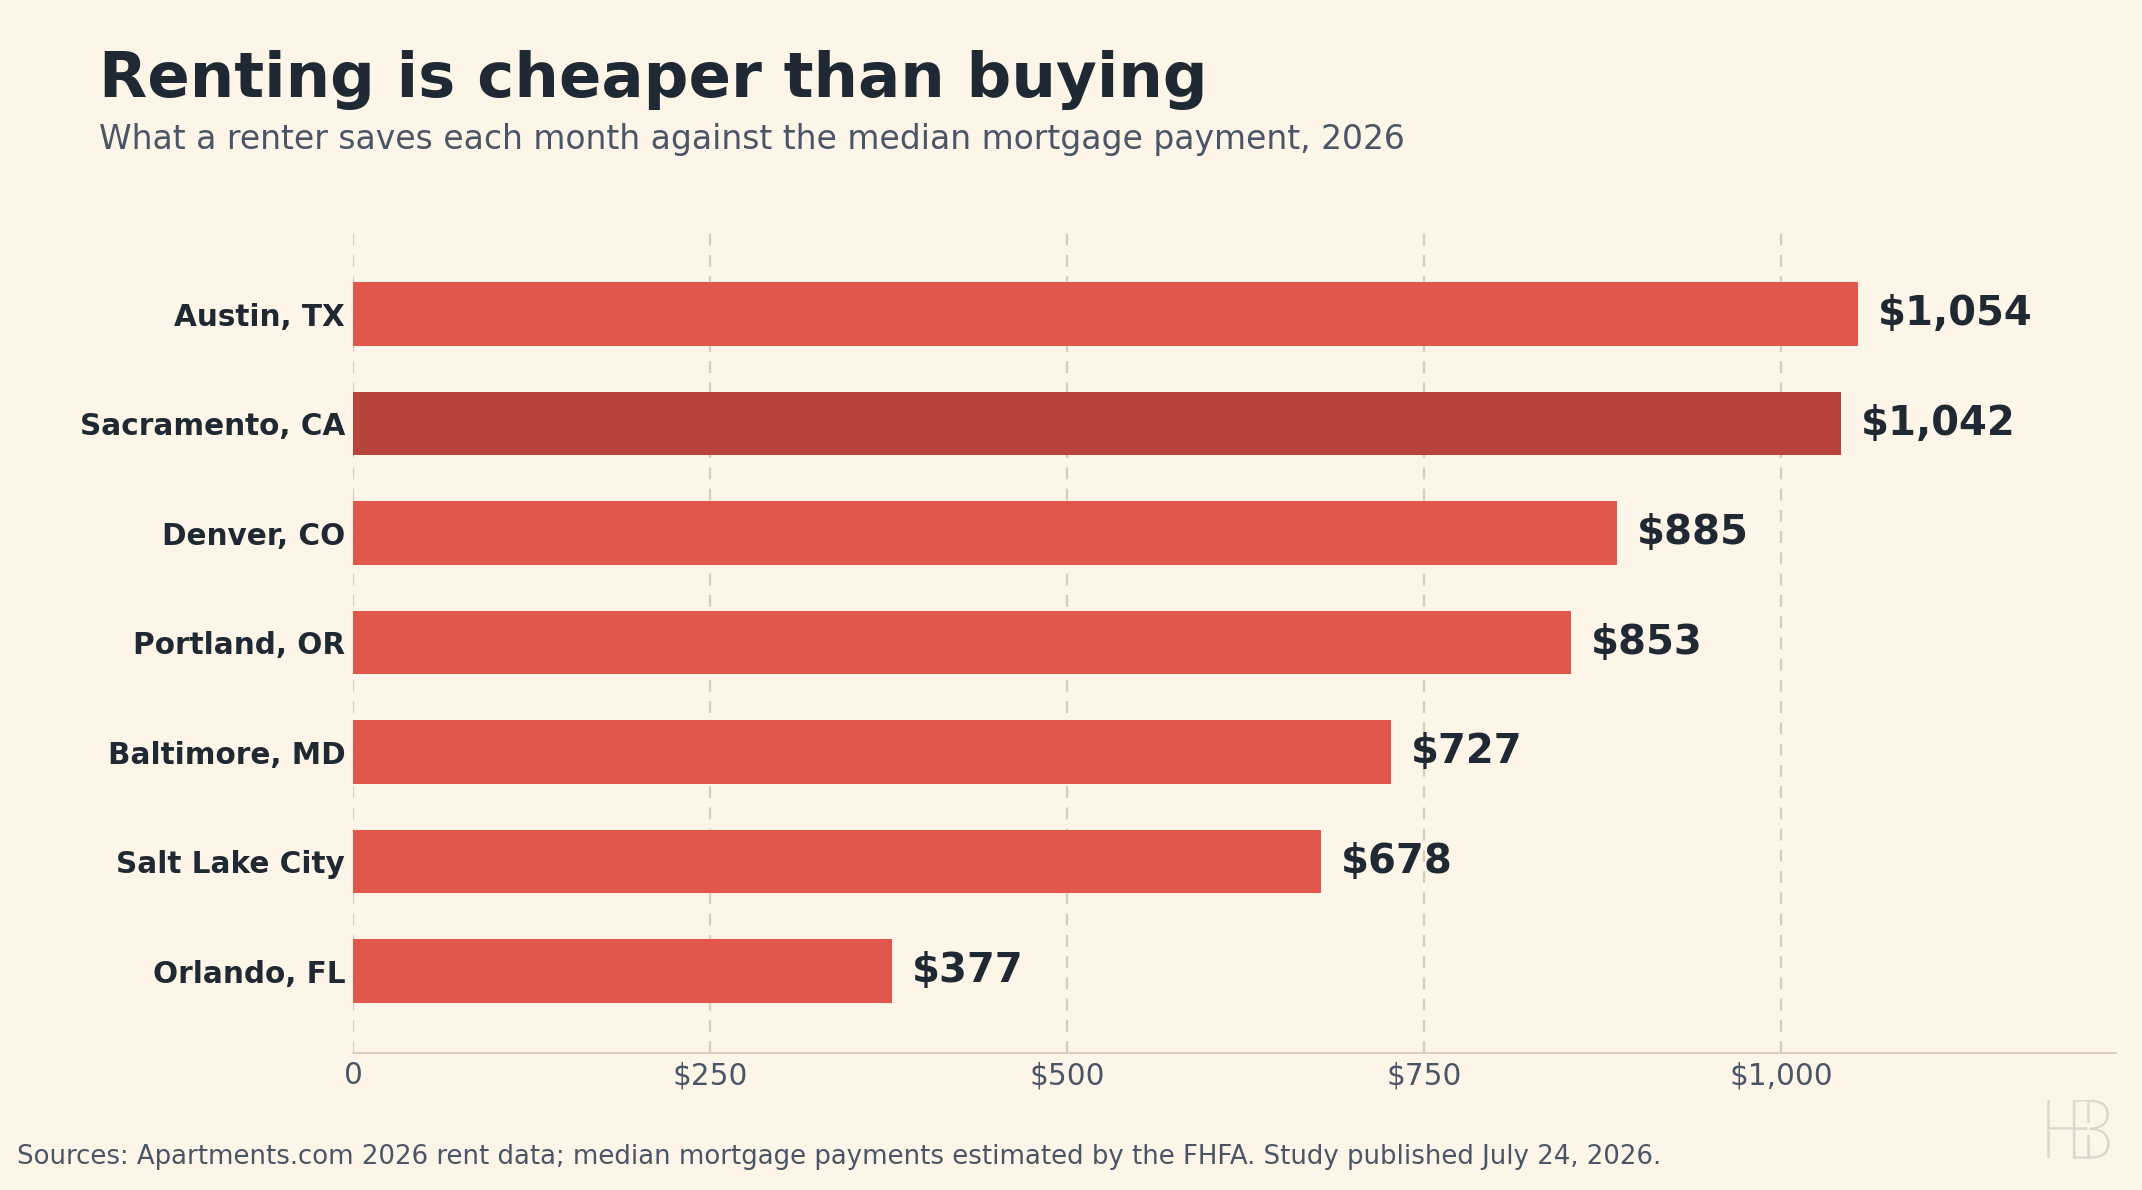
A rent versus buy study made the rounds this morning, and no Bay Area market was in it. Apartments.com ranked seven metros where renting costs less each month, led by Austin at $1,054 and Sacramento at $1,042. Two cautions before anyone repeats those figures. The study compares an average apartment rent against a median mortgage payment on a house, so it measures monthly cash out the door rather than the same roof, and it is dated July 24, so it is a month old.
So we ran the same question on our own market, and the answer is not close. Pricing each city off Zillow's typical home value and typical rent for July, with a payment of 20% down on a 30-year fixed at 6.75%, principal and interest only, Fremont's monthly gap is $4,280. That is roughly four times Austin's, and even Hayward, the smallest of our five at $1,680, beats the metro the study ranked first. To prove the method we ran Austin through the same math and got $1,006 against the published $1,054, a difference explained entirely by the price source. Every figure here is the conservative one, because property taxes, insurance and any HOA sit on top of every payment shown.
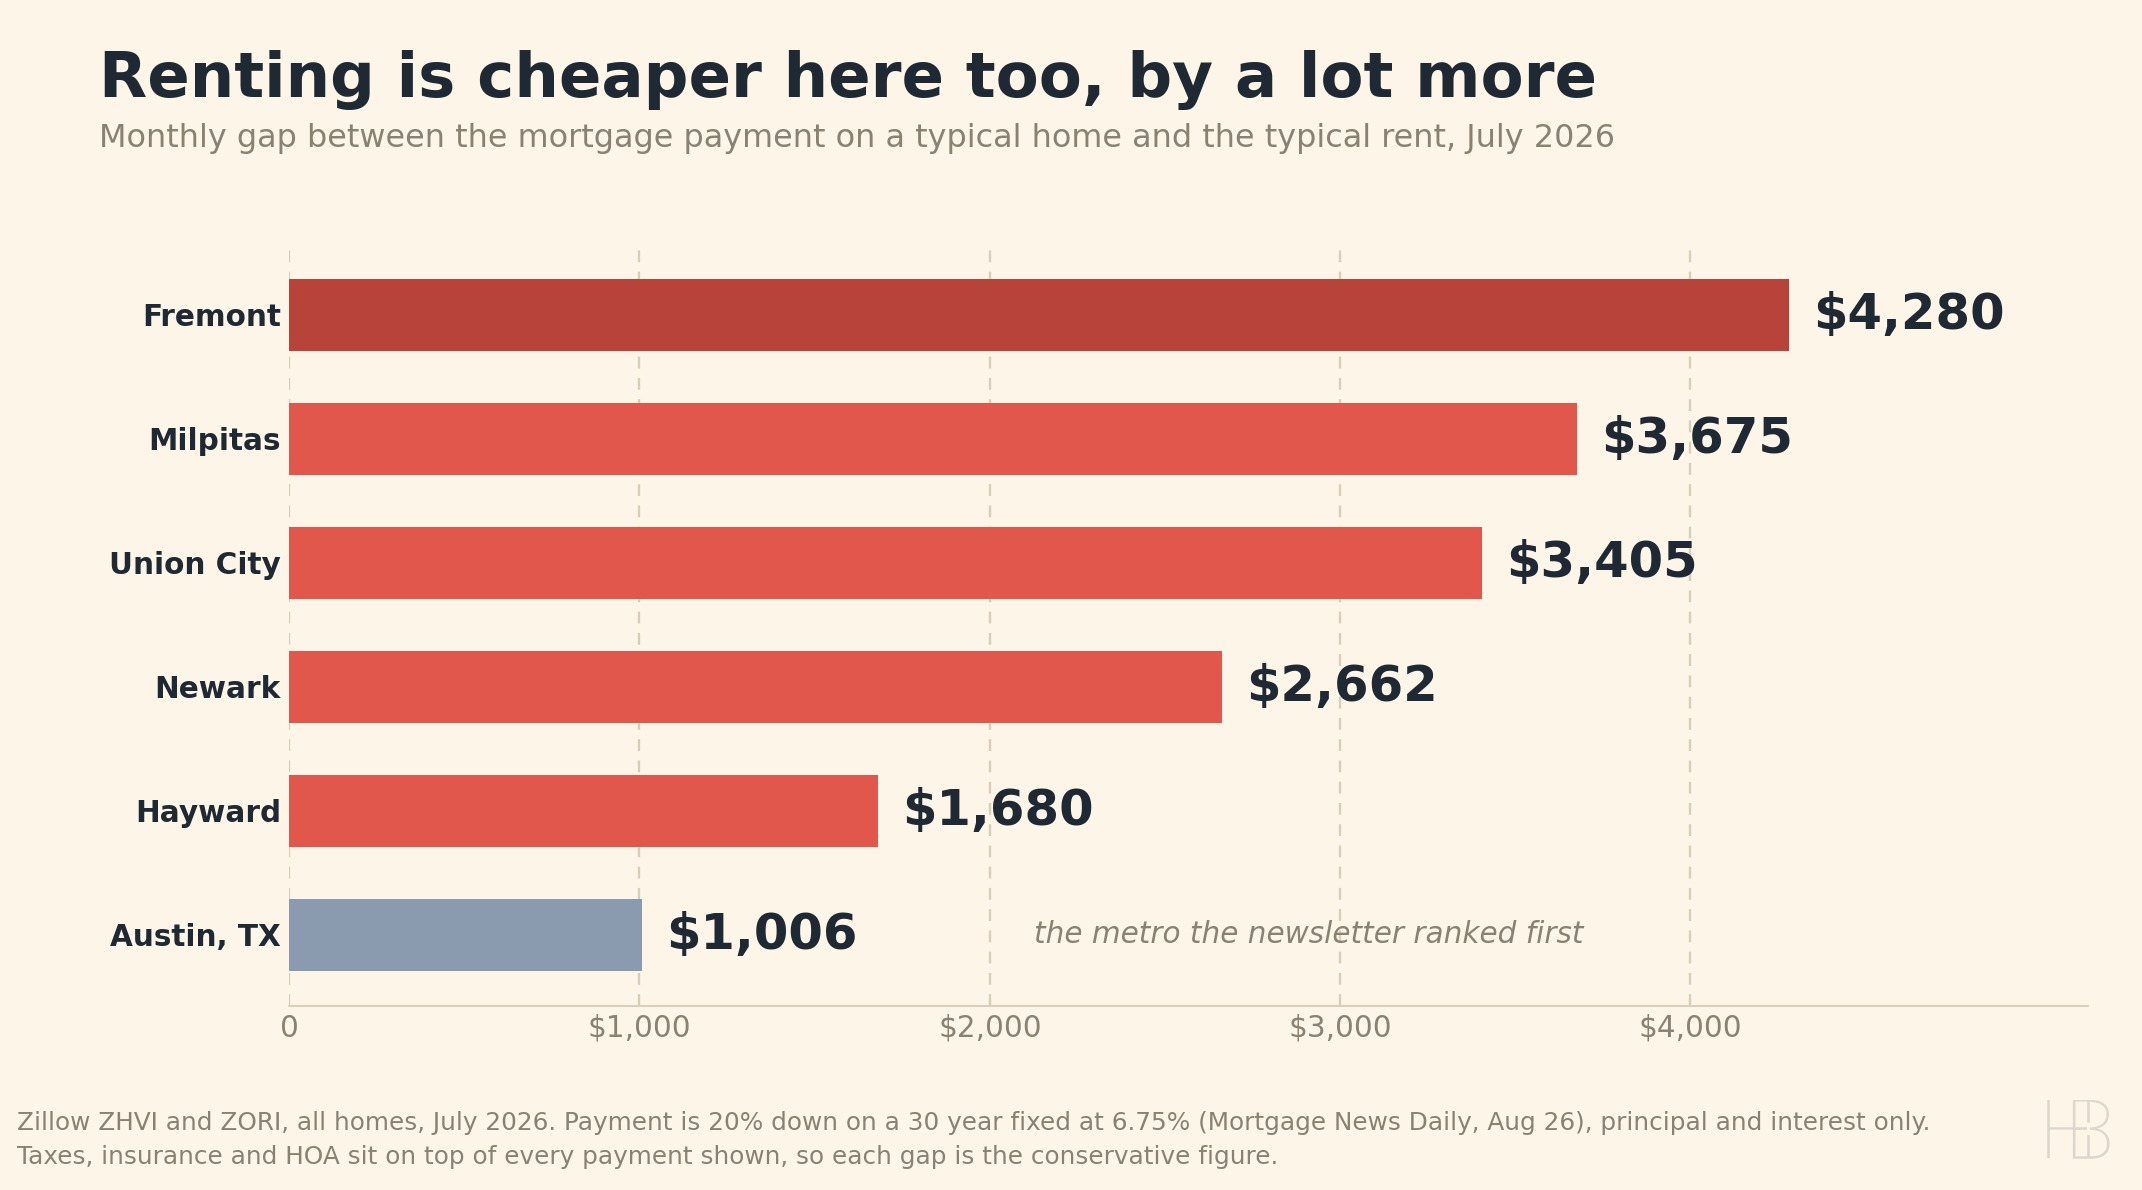
Two honest footnotes. On this like for like basis Sacramento's gap works out to about $429 rather than the $1,042 in the study, because their figure prices an apartment rent against a house sized mortgage. And using our own board rather than Zillow, the median list price of today's 240 active Fremont listings is $1,260,912, which at the same terms is $6,543 of principal and interest and a $3,185 gap. So call Fremont's true range $3,200 to $4,300 a month.
What to do with it. This is not an argument against owning, and it should not be used as one. It is the arithmetic behind why buyers hesitate. In this market buying is a bet on equity and on staying put, not on beating rent from month one. Someone who plans to move in three years is better off renting. Someone who plans to stay ten is not.
Locally the board is carrying 2,697 listings across the 15 city board, counting everything active alongside everything in contract, with 203 coming soon and 186 brand new today. Our own 5 city ledger shows 696 homes a buyer can pursue right now, including 34 brand new listings and 103 more coming soon. The full, always-updating ledger lives at harvrealtor.net/live-inventory.
Today’s Live Inventory (buyable now)
- Fremont: 275 available (213 active, 16 new, 46 coming soon)
- Hayward: 186 available (162 active, 9 new, 15 coming soon)
- Milpitas: 112 available (83 active, 2 new, 27 coming soon)
- Newark: 70 available (57 active, 4 new, 9 coming soon)
- Union City: 53 available (44 active, 3 new, 6 coming soon)
The ledger eased to 696 from 697, which is flat. The number worth watching is Fremont, where 102 listings have now stayed in contract for three straight days while the active count drifted from 241 to 240. Steady demand against thinning supply is the quiet version of a tightening market. Median asking runs from $848,500 in Hayward to $1,299,888 in Fremont, and Newark is the quickest at 26 median days on market. Note too that 46 of Fremont's listings are coming soon rather than live, the largest such block on the board and the window where a prepared buyer gets a look before the portals light up.
US 10-Year: 4.64% ▼ 0.06% | Gold: $4,615 ▼ 0.32% | Silver: $68.55 ▲ 0.55% | Brent: $88.58 ▼ 3.89%
The ten year eased to 4.64%, six basis points below Monday. The morning newsletter printed that same level but called the day's change zero. Treasury's own daily curve has Monday at 4.70%, so the yield fell rather than sat still, and a falling ten year is what eventually pulls mortgage rates down.
Brent settled at $88.58, down 3.89%. The newsletter reported $86.23, which does not match the front month contract's settlement. Oil giving back nearly four percent while Iran and Oman negotiate a shared safe corridor through the Strait of Hormuz is the market pricing a little less risk into every barrel.
Metals barely moved on the day and enormously on the month. Gold slipped $15 to $4,615 and silver added 38 cents to $68.55. Both of Fortune's day over day comparisons reconcile exactly against the figures we published yesterday. Look past the daily noise, though: gold is up 14.6% in August and silver 19.2%.
That is the debasement trade. With federal debt past $40 trillion and the Treasury stepping up buybacks, money moves toward assets that cannot be printed. The flow is real, and August makes the case better than any argument.
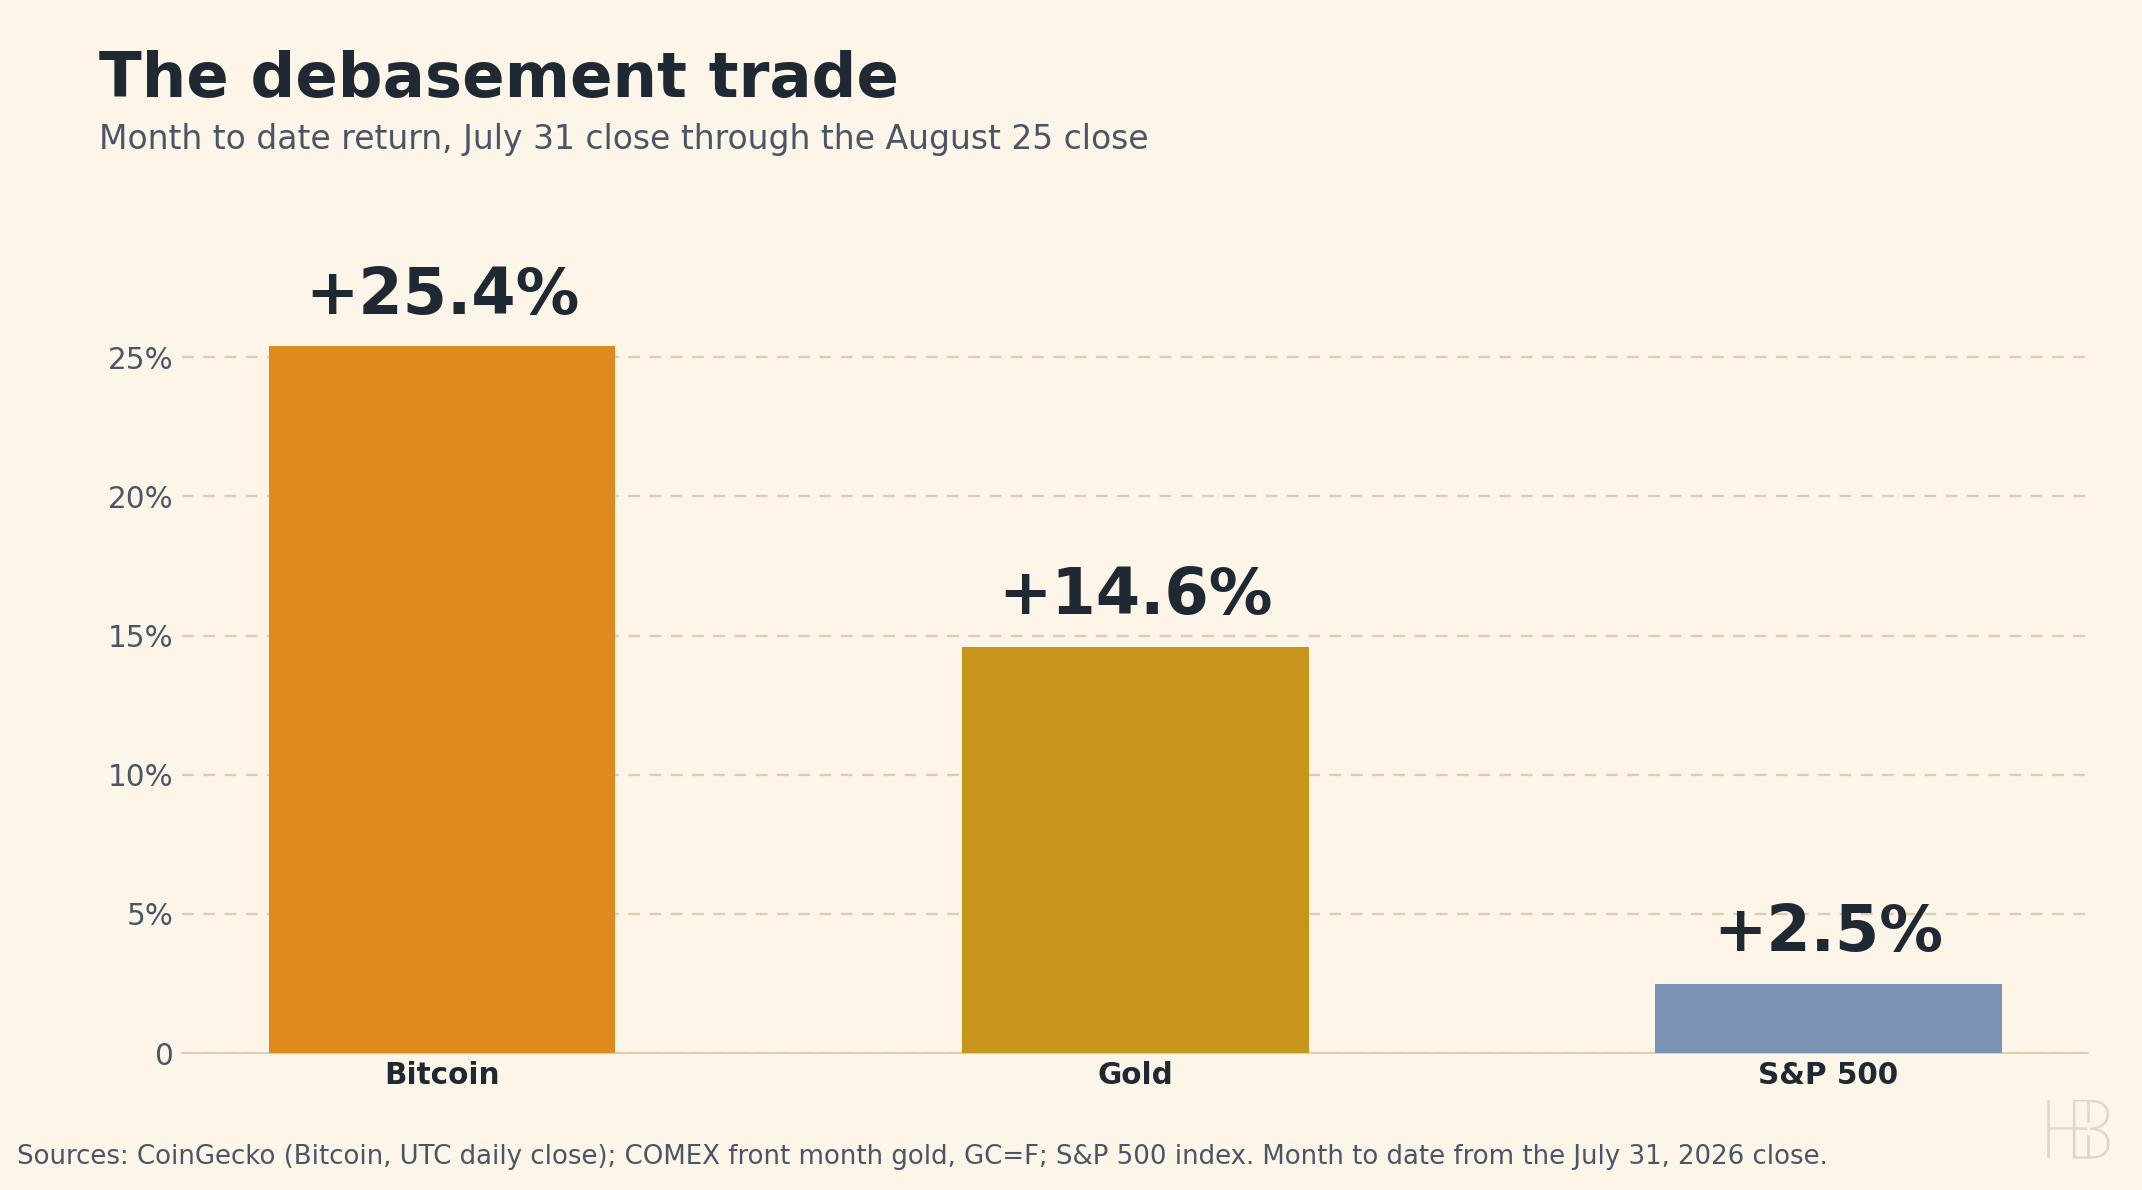
One correction to the version doing the rounds. The chart above is recomputed from primary series rather than reprinted, and Bitcoin's August gain is 25.4%, not the 23% being quoted. The newsletter also claimed Bitcoin touched $81,000 yesterday. It peaked near $79,540.
Why a housing letter cares. A debasement trade is a vote against the currency, and the same worry that pushes money into gold keeps a floor under long term yields. That floor is the reason mortgage rates have refused to break lower all summer.
S&P 500: 7,677 ▲ 0.32% | DOW: 53,577 ▲ 0.30% | NASDAQ: 26,151 ▲ 0.66%
A quiet, broad advance. All three indexes finished higher, with the NASDAQ doing most of the work. Every stock figure in the morning newsletter reconciled against the tape, which is more than can be said for the rest of it today. The S&P is up 2.5% for the month.
The moves were company specific rather than macro. Dick's Sporting Goods fell hard on a weak quarter, Northrop Grumman picked up roughly $3 billion in Golden Dome defense work, and Apple confirmed a pricier Mac mini built around its fastest AI chip. Lego, still private, posted its best first half ever with sales up 21%, a useful reminder that consumer spending is not weak everywhere, it is selective.
And SpaceX is heading to Louisiana, with plans to spend up to $100 billion on a new launch site. Coastal geography and a state legislature willing to move quickly won it. For anyone who watches how regions grow, that is the whole formula in one sentence.
BTC: $78,391 ▲ 0.11% | ETH: $2,469 ▲ 1.19% | XRP: $1.38 ▼ 5.03%
Bitcoin is flat, ether firmer, and XRP is the outlier with a five percent slide over 24 hours. These are live quotes taken this afternoon. Worth knowing: the crypto figures in this morning's newsletter were stamped Monday afternoon, two days stale by the time they landed, and its XRP line showed a gain where the live market shows a loss.
Meanwhile a Kalshi market puts the odds of the Clarity Act becoming law this year below 25%, with most bets now pointing past July 2027. Crypto's regulatory calendar keeps slipping to the right.
Sources
- Mortgage News Daily (mortgage rates, 30-year and 15-year history)
- Market Briefs (market data)
- U.S. Treasury (daily yield curve)
- Apartments.com (rent versus buy study, July 24, 2026)
- Zillow Research (ZHVI and ZORI, July 2026)
- Yahoo Finance (Brent front-month futures, gold and silver futures)
- Fortune (gold spot)
- Fortune (silver spot)
- CoinGecko (crypto quotes and Bitcoin daily closes)
- Live Inventory (5-city MLS board)
Disclaimer: The market data, rates, and information provided are for informational purposes only and should not be considered financial advice. Always verify rates and data with your lender or financial advisor before making any decisions.