



"At a Glance" Local Housing STATS and News 08/25/26
August 25, 2026 · Alameda County Market Dashboard
TODAY'S LIVE INVENTORY
Behind these county totals: hundreds of homes still for sale in Fremont, Hayward, Union City, Newark and Milpitas, one live ledger with prices, sizes and a market read, refreshed each morning from the same MLS export.
30-Year Fixed: 6.78% ▬ unchanged | 15-Year Fixed: 6.62% ▬ unchanged
Rates sat still. The 30-year fixed is 6.78% and the 15-year is 6.62%, both unchanged, per Mortgage News Daily, whose board has not posted a Tuesday print yet. So these are Monday's closing figures.
The 15-year flag stays up for a third session. Mortgage News Daily has the 15-year at 6.62%, Freddie Mac's weekly survey has it at 5.95%, and the Mortgage Bankers Association has it at 6.08%. All three agree on the 30-year within 13 basis points, so the disagreement is confined to one number. At 6.62% there are only 16 basis points between the 15-year and the 30-year on the same board, where the normal gap is closer to 70. Nothing has moved since Friday's 31 basis point jump, which makes this a settled disagreement rather than a one day spike. Quote the 30-year freely. Do not put the 15-year in front of anyone without a live lender quote behind it.
Two housing headlines landed together, pointing opposite directions. JPMorgan committed $750 billion over ten years to build or preserve 1 million homes. Read the incentive honestly: mortgage lending is at a low and banks earn when people borrow, so the bank is buying itself a future pipeline. That does not make it bad news, because capital at that scale aimed at supply is exactly what this market has lacked. Working the other way, material costs rose 9.1% for builders with five or fewer starts against just 1.8% for the large firms, because scale buys discounts. The builders most likely to put a single house on an infill lot face the worst cost inflation, which is part of why new supply keeps arriving as large tract product instead of scattered homes.
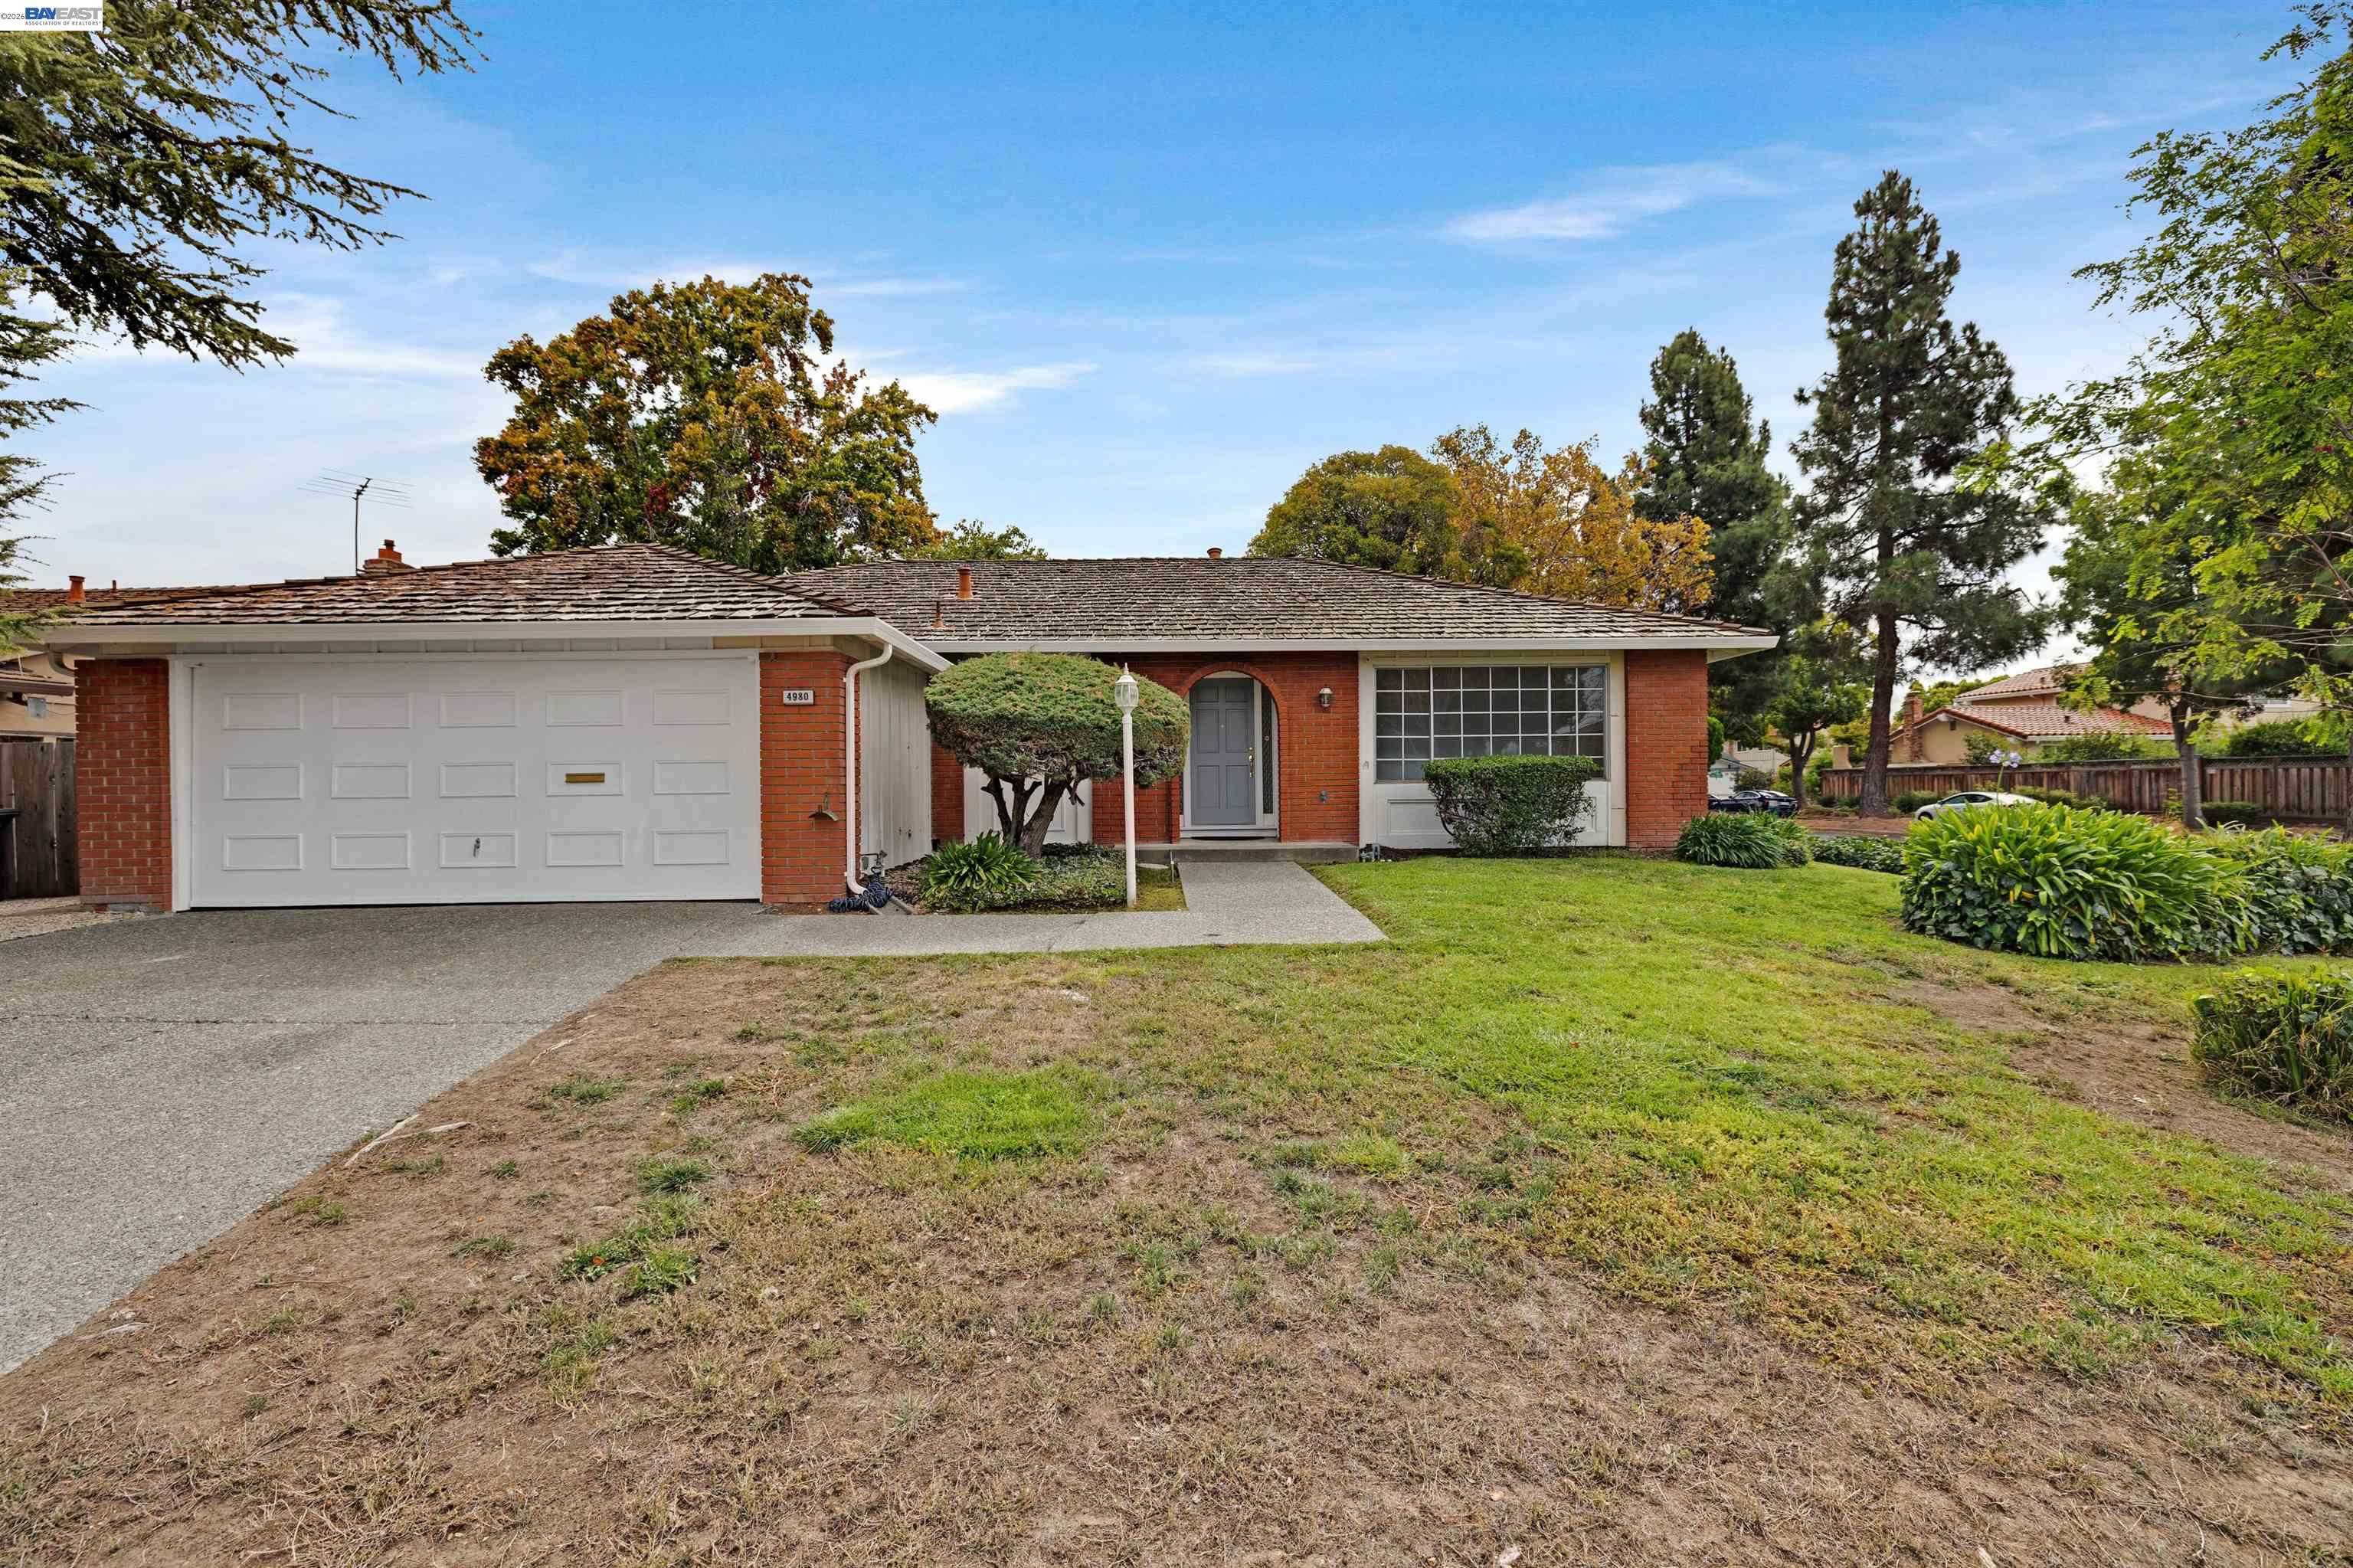
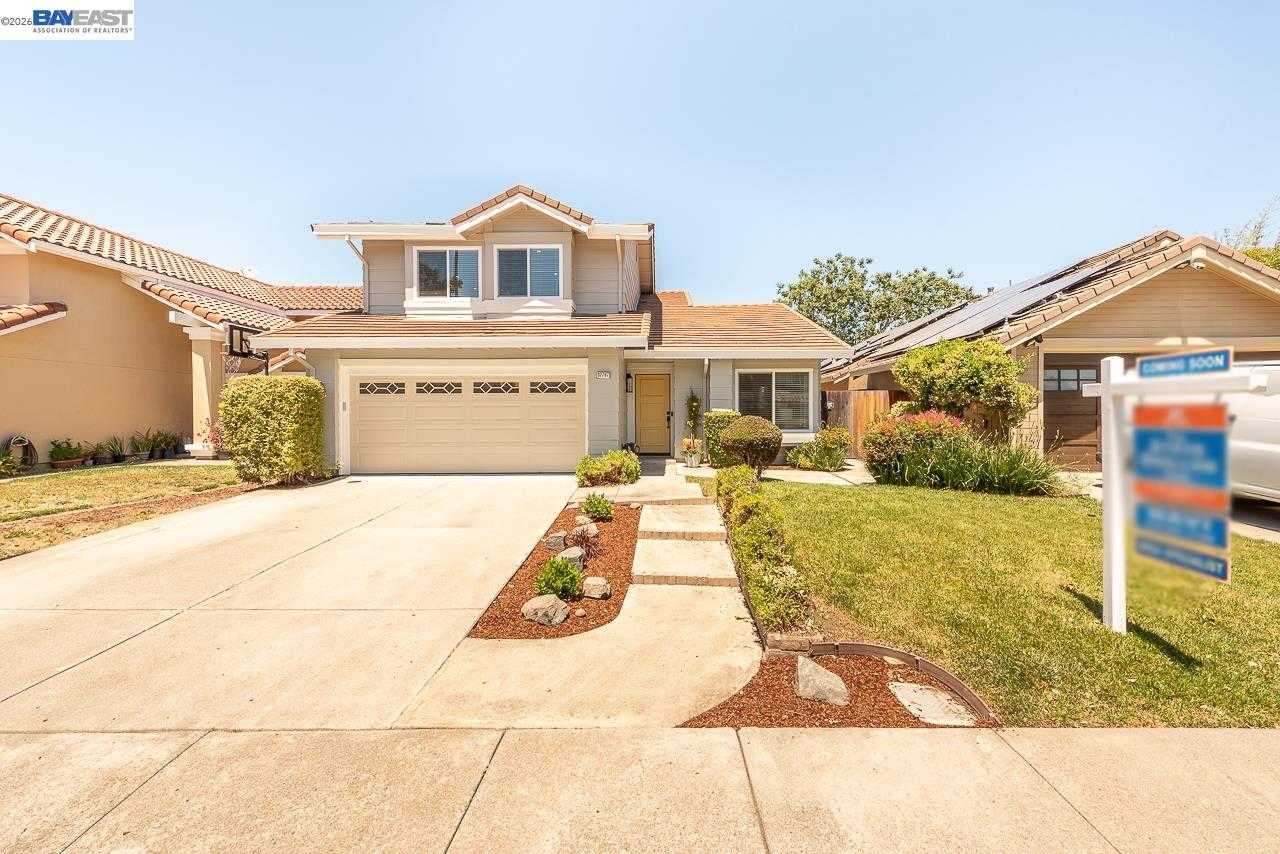
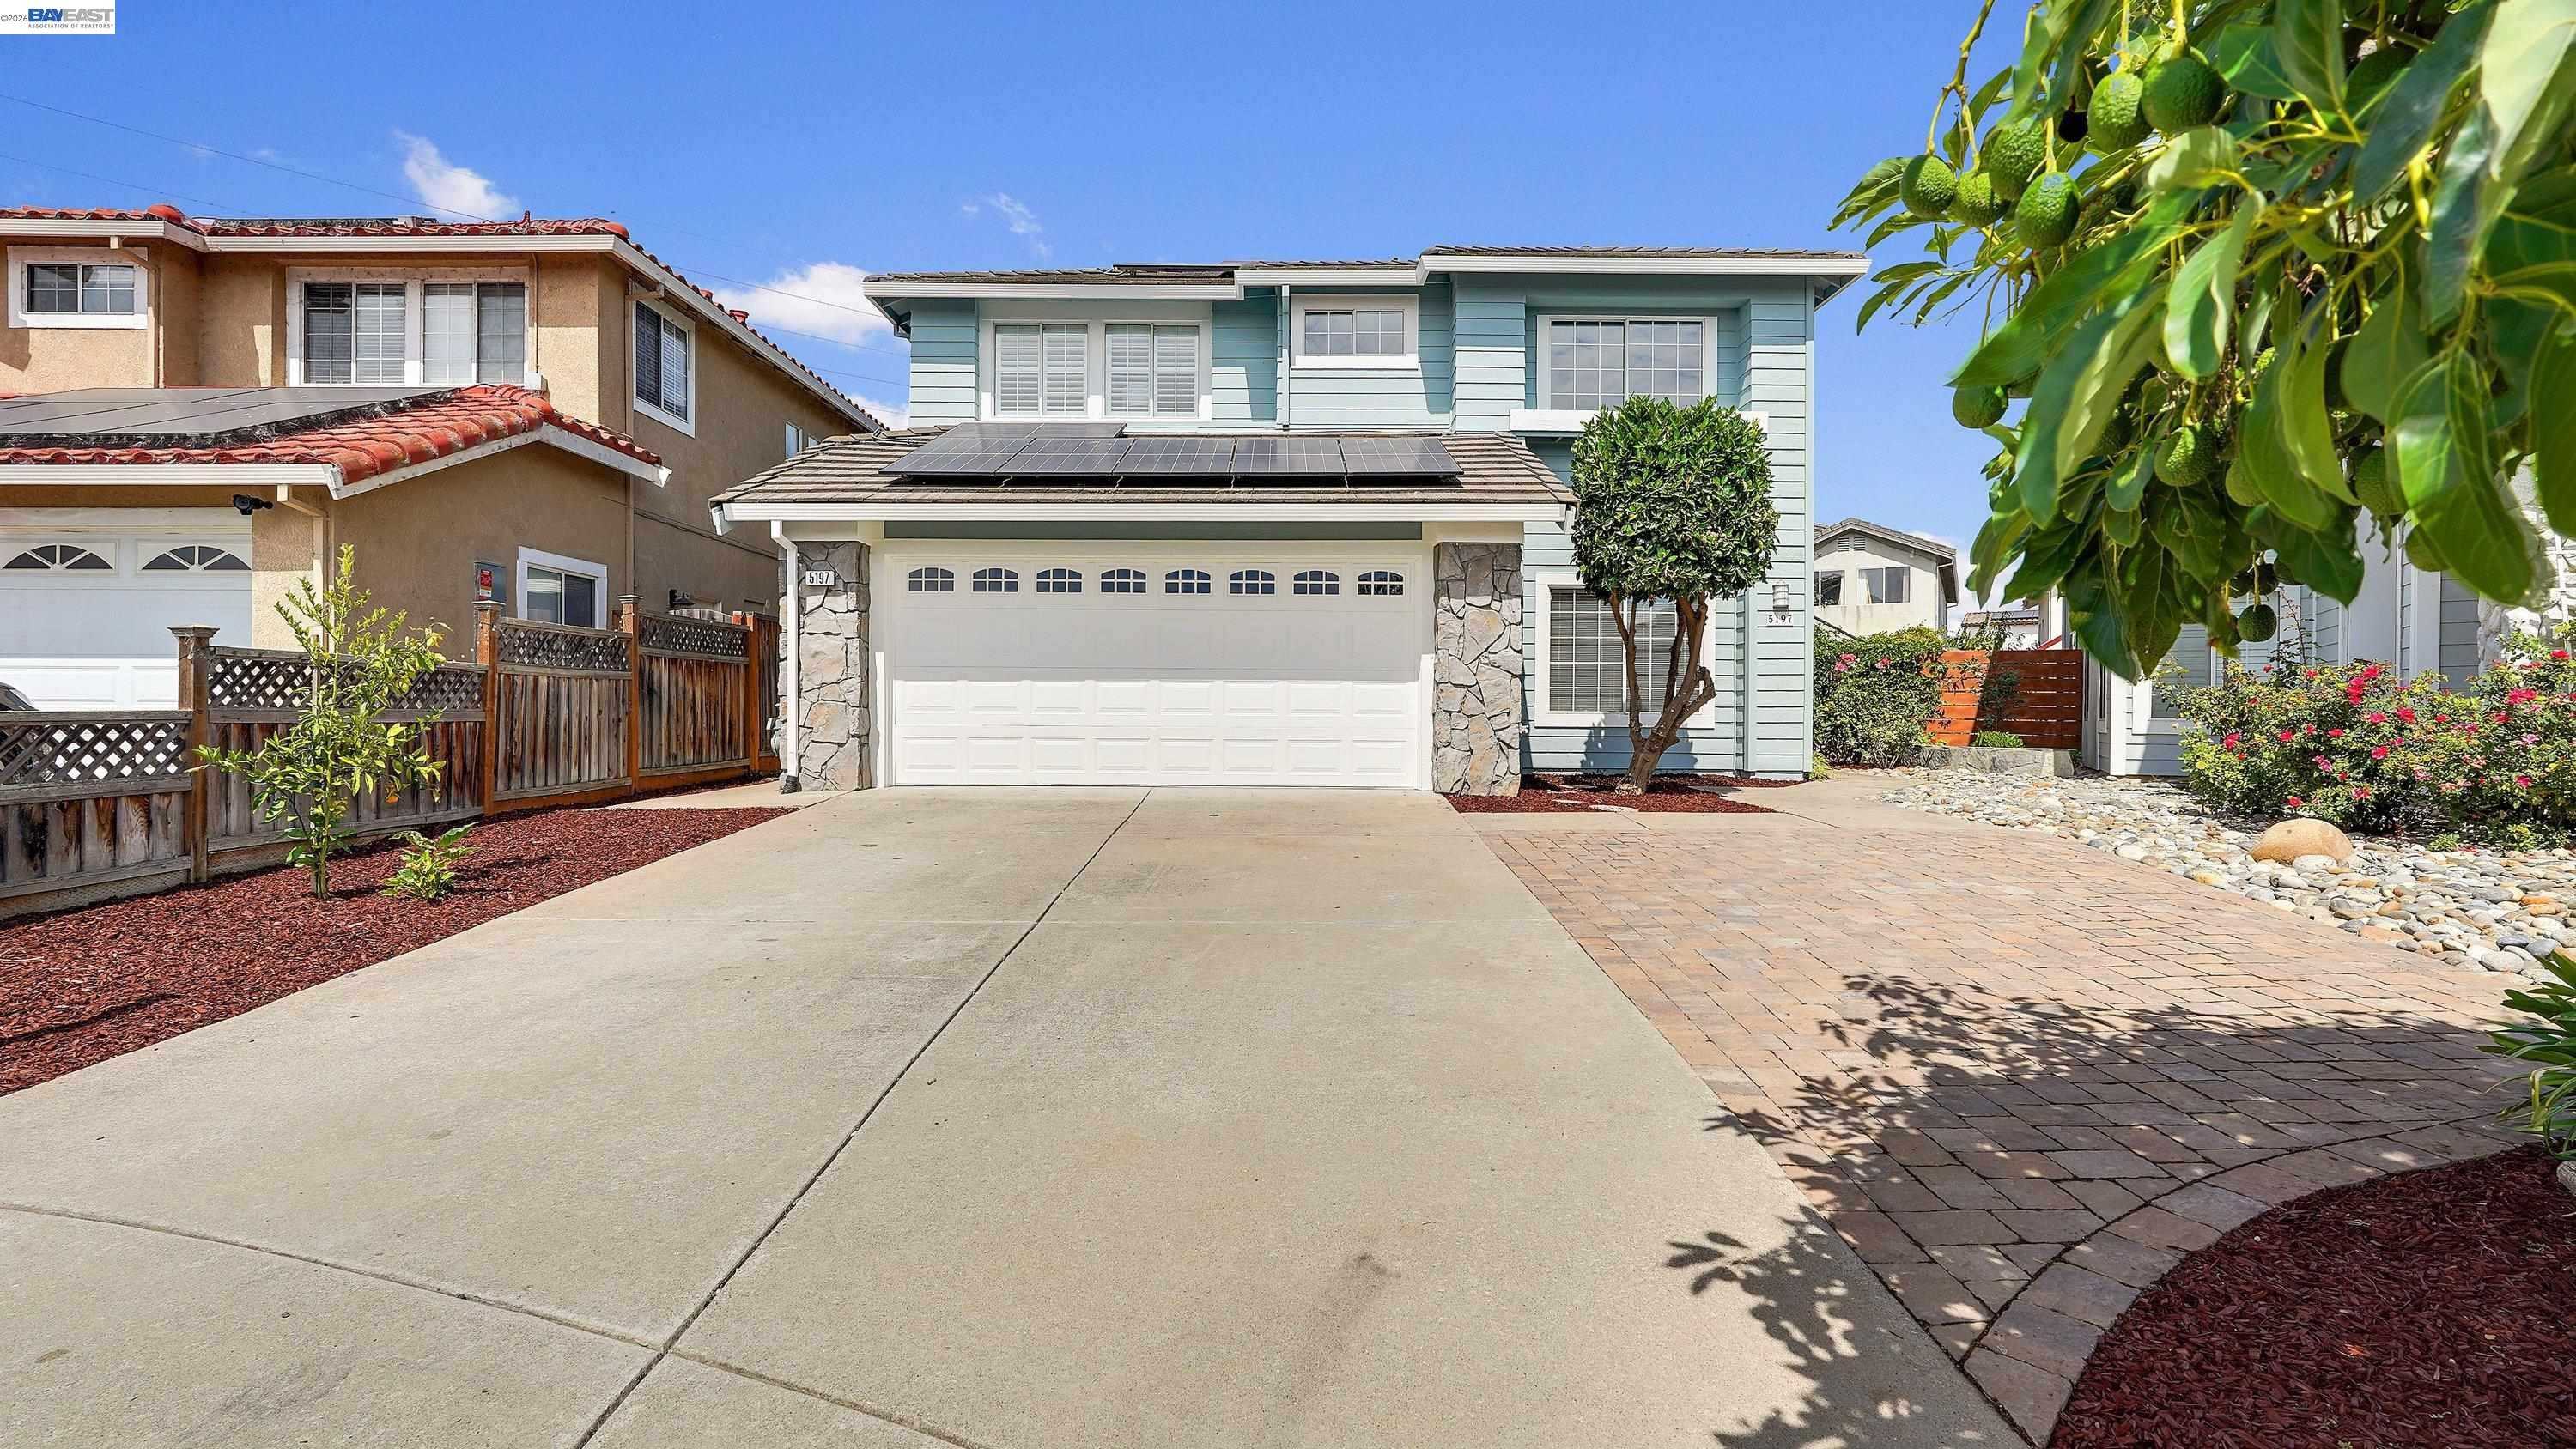
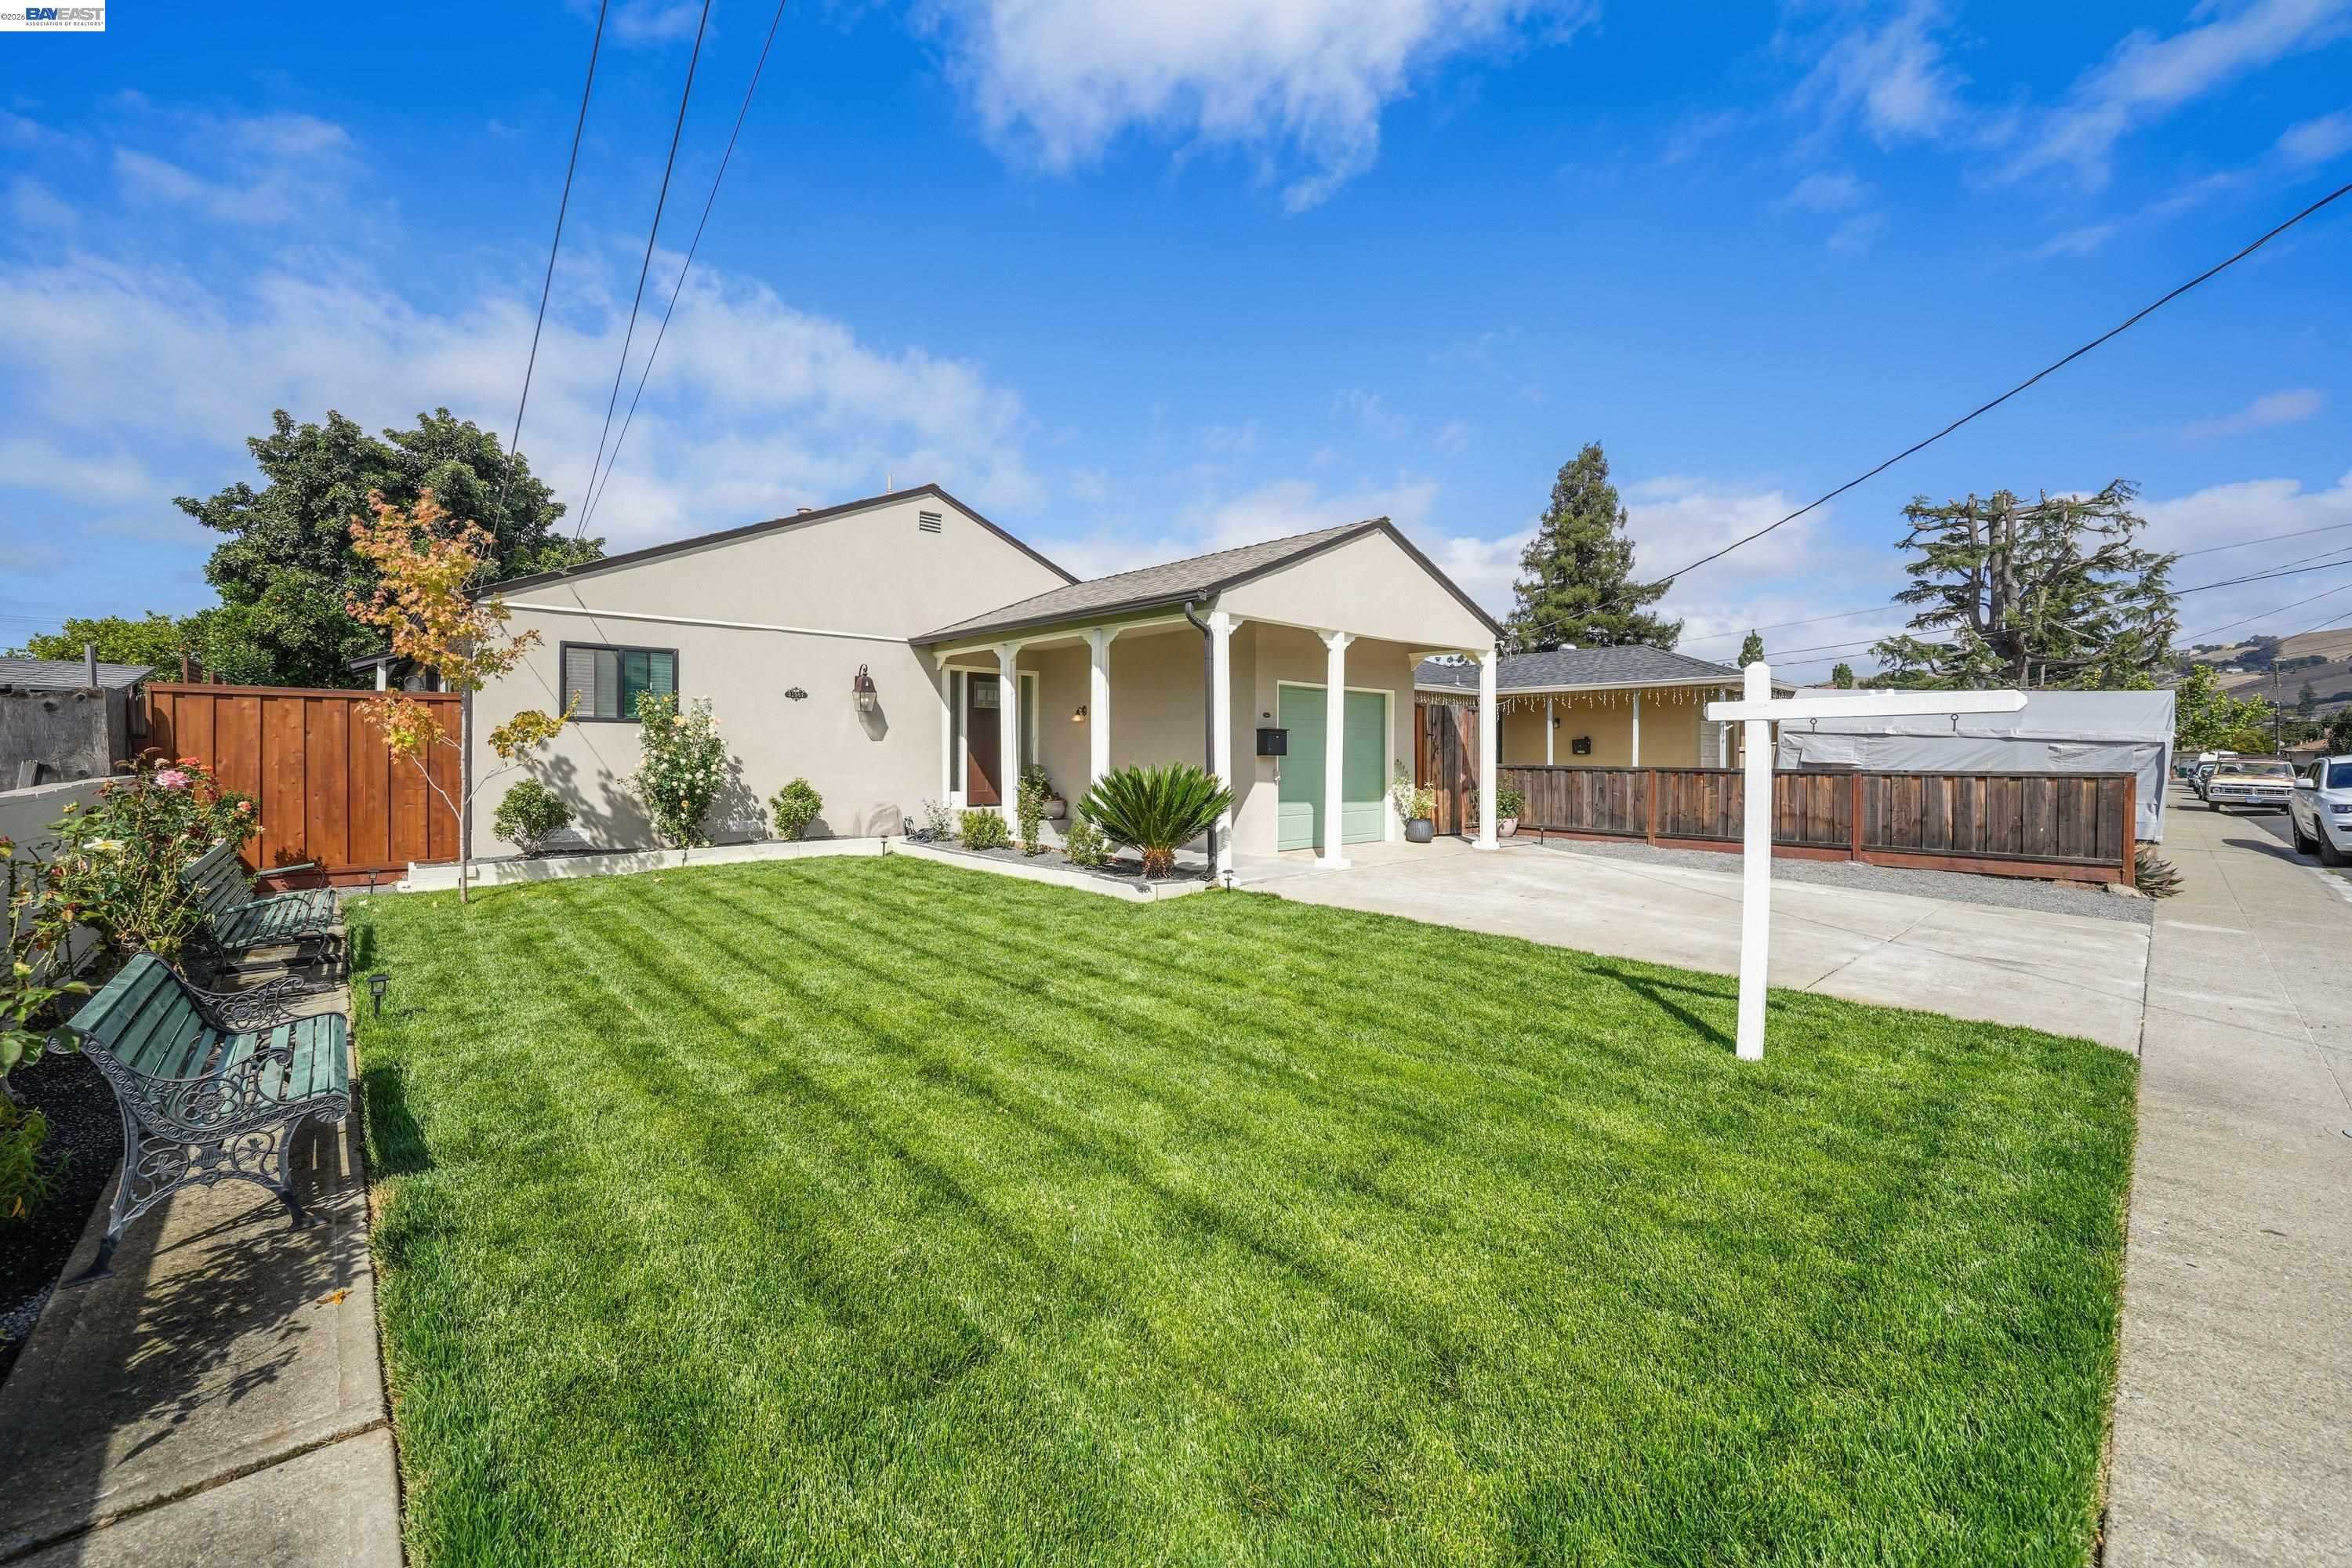
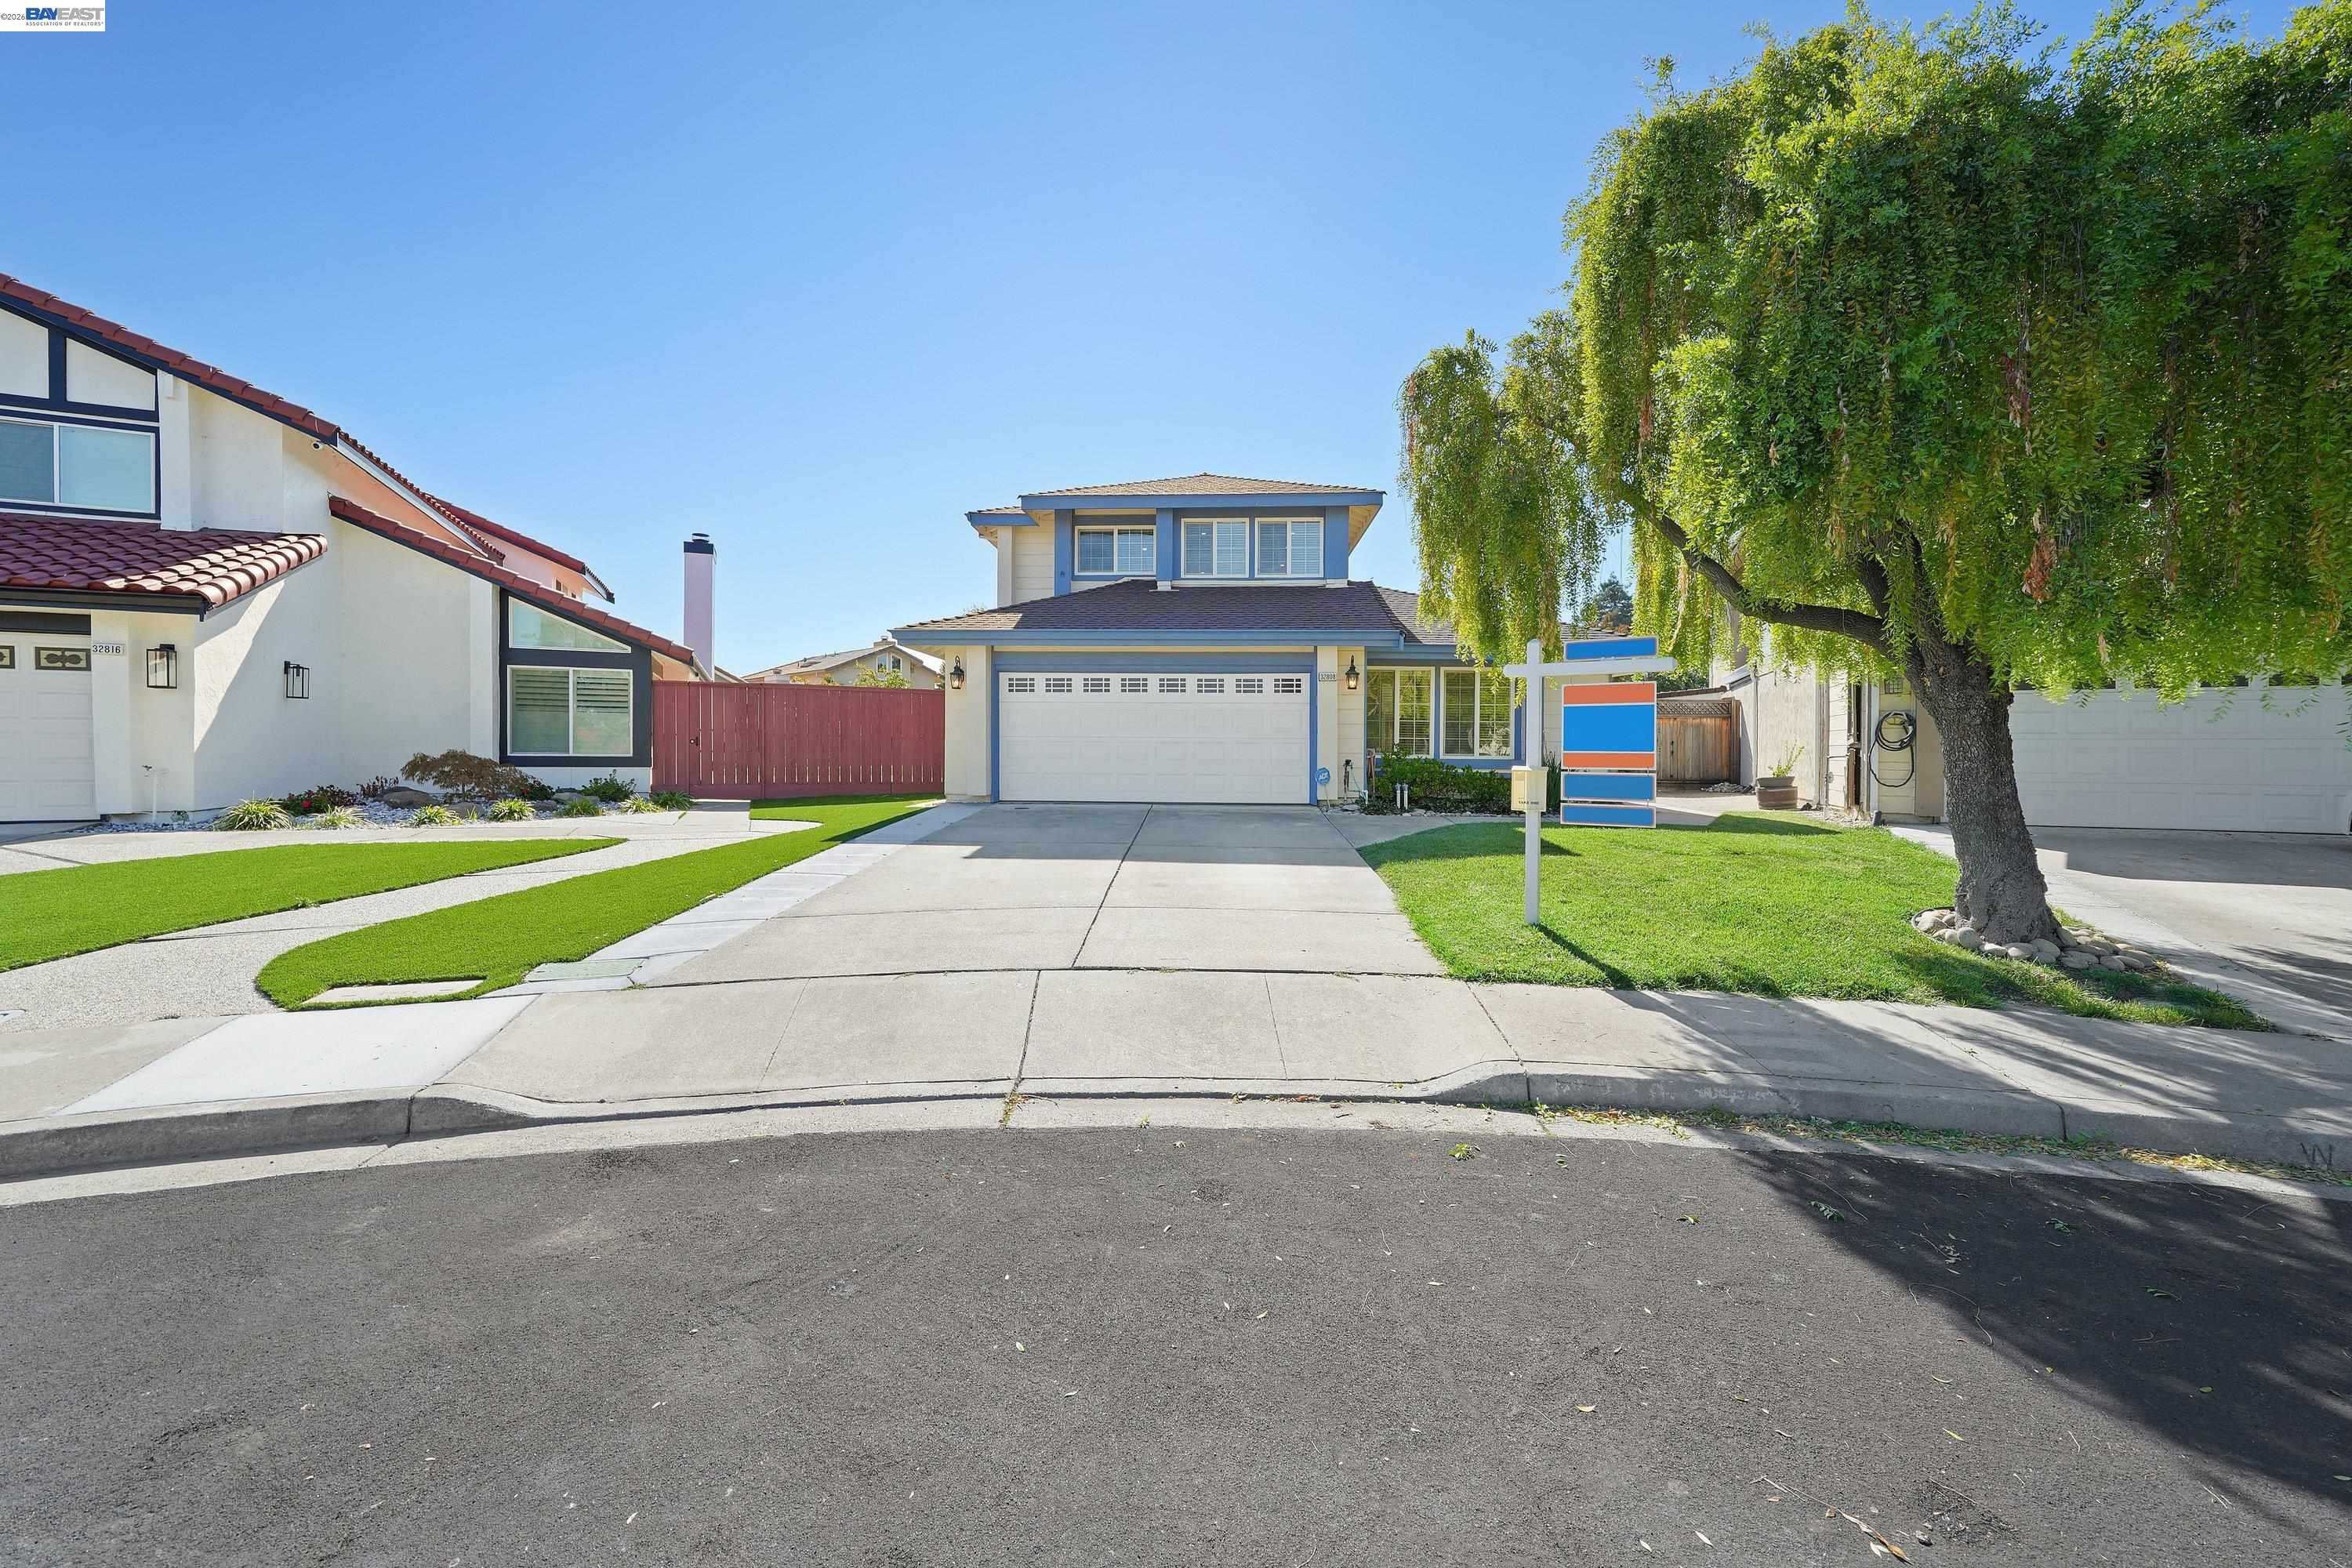
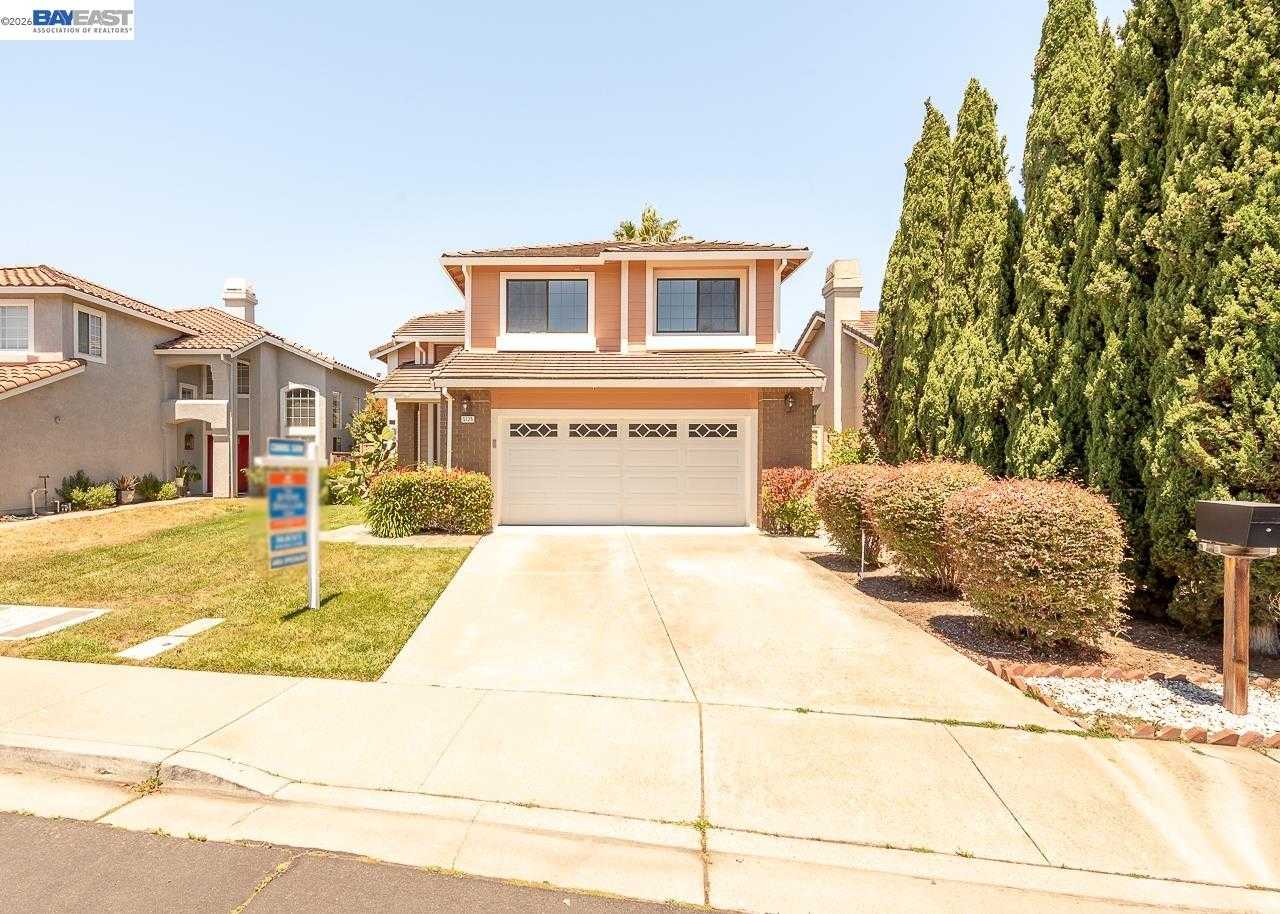
Locally the board is carrying 2,701 active, BOMK, PCH and new listings across the 15 city board, with 193 coming soon and 213 brand new today. Our own 5 city ledger shows 697 homes a buyer can pursue right now, including 43 brand new listings and 103 more coming soon. The full, always-updating ledger lives at harvrealtor.net/live-inventory.
Today’s Live Inventory (buyable now)
- Fremont: 273 available (210 active, 19 new, 44 coming soon)
- Hayward: 188 available (158 active, 12 new, 18 coming soon)
- Milpitas: 111 available (82 active, 3 new, 26 coming soon)
- Newark: 72 available (59 active, 4 new, 9 coming soon)
- Union City: 53 available (42 active, 5 new, 6 coming soon)
The ledger eased to 697 from 703, a sixth of a percent, so call it flat. The number worth watching is Fremont, where 102 listings have stayed in contract for two days running while the active count slipped from 248 to 241. Steady demand against thinning supply is the quiet version of a tightening market. Median asking runs from $848,500 in Hayward to $1,299,990 in Fremont, and Fremont and Newark are tied as the quickest at 26 median days on market. Note too that 44 of Fremont's listings are coming soon rather than live, the largest such block on the board and the window where a prepared buyer gets a look before the portals light up.
US 10-Year: 4.70% ▼ 0.04% | Gold: $4,630 ▼ 0.94% | Silver: $68.17 ▼ 1.45% | Brent: $92.17 ▼ 2.35%
Oil is the story to watch this week. Washington unveiled its largest ever financial penalties on Iran, and Tehran is threatening to close the Strait of Hormuz and seize ships. Roughly a fifth of the world's seaborne oil moves through that strait. Brent settled Monday at $92.17, down 2.35%, and the front month contract is trading near $87 as this is written, though that session has not settled. The market is reading sanctions as less demand rather than less supply, which is exactly the kind of position that reverses on a single headline. Mortgage pricing feels oil through inflation expectations, so this is not as far from housing as it looks.
The morning newsletter got two numbers wrong here. It printed Brent at $92.31 and called it a 0.15% gain, when Brent fell 2.35%, so both the level and the direction were off. It also showed the 10-Year at 4.70% and unchanged, when Treasury's own daily curve has Monday at 4.70%, down four basis points from Friday's 4.74%. The level was right, the change was not.
Metals gave back ground. Gold is $4,630 an ounce, down 0.94%, and silver is $68.17, down 1.45%. Both of Fortune's day over day comparisons reconcile exactly with the figures we published yesterday, which is worth saying after their gold article contradicted its own prior edition on Monday.
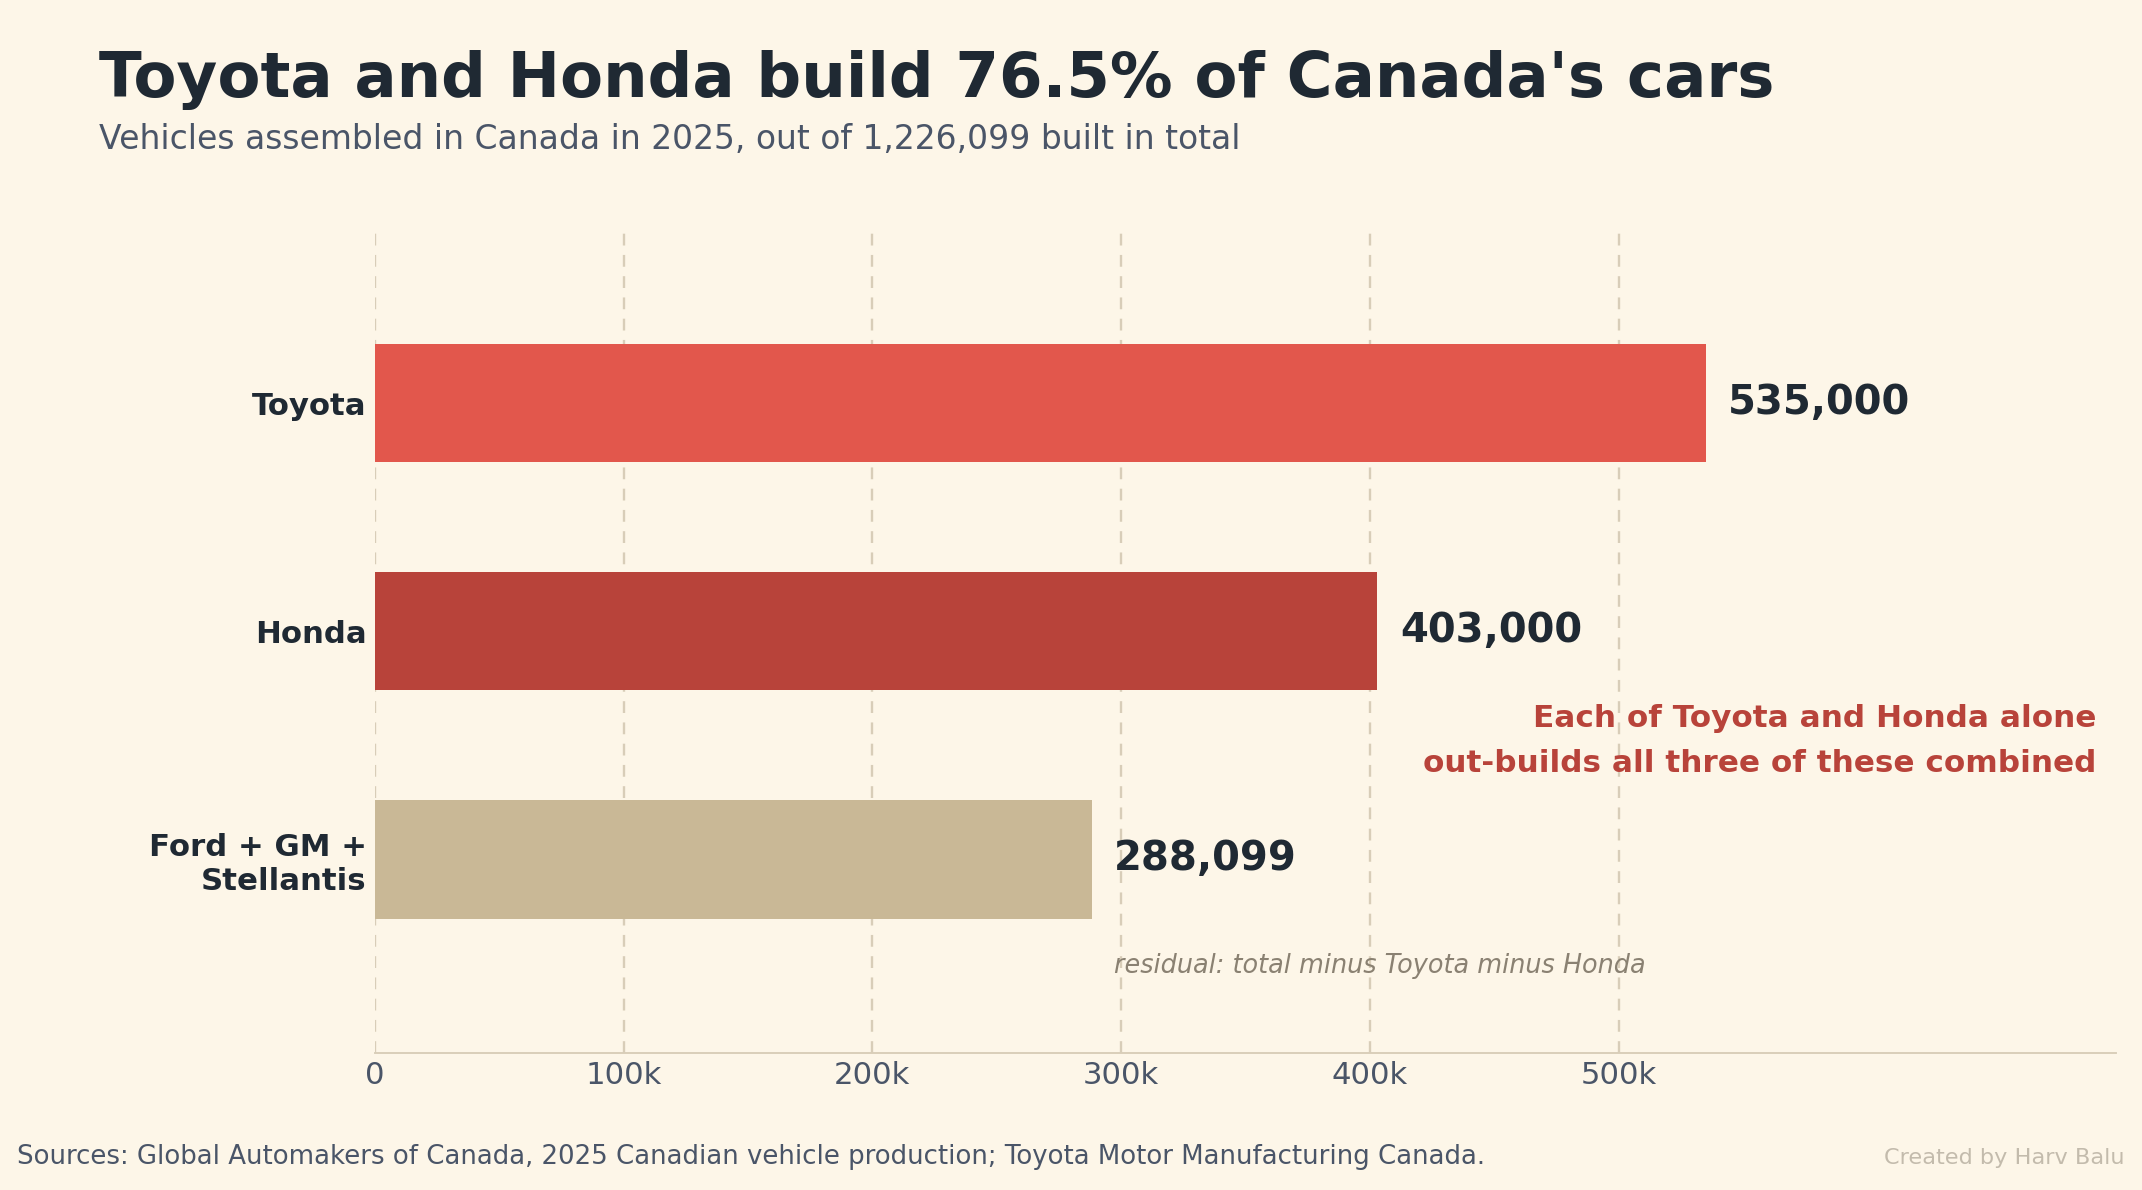
The tariff on Canadian built vehicles is doubling to 50%, and the claim that Toyota and Honda build 76.5% of Canada's cars checks out precisely. Those two assembled 938,000 of the 1,226,099 vehicles Canada built in 2025, and each of them individually out-built Ford, General Motors and Stellantis combined. A tariff aimed at Canada therefore lands hardest on two Japanese automakers and the Ontario towns their plants support.
One more from the Treasury desk. The government may tap its $950 billion cash balance to double bond buybacks to $4 billion per operation, which Secretary Bessent argues would calm a jumpy bond market without issuing new debt. Goldman Sachs and Citadel Securities both say it will not work. Watch it anyway, because a calmer long end is the shortest path to a lower mortgage rate.
S&P 500: 7,653 ▼ 0.28% | DOW: 53,417 ▲ 0.26% | NASDAQ: 25,980 ▼ 0.77%
A soft Monday under the surface. The S&P 500 closed at 7,653, down 0.28%, the NASDAQ fell 0.77% to 25,980, and only the Dow finished green. Every stock figure in the morning newsletter reconciled against the tape, which does not happen every day.
Nvidia is the name to watch. It bought Groq for $20 billion last year and says the first chips from that deal come online this year. Groq builds language processing units, the chips that answer questions rather than train models, so this is Nvidia buying into the part of AI that runs every day rather than the part that gets built once.
And then there is the moon. Elon Musk floated sending rockets there late next year to set up data centers, on the logic that space is cold and power is free. Before anyone gets carried away with orbital server farms, it is worth seeing where the ones on Earth actually sit.
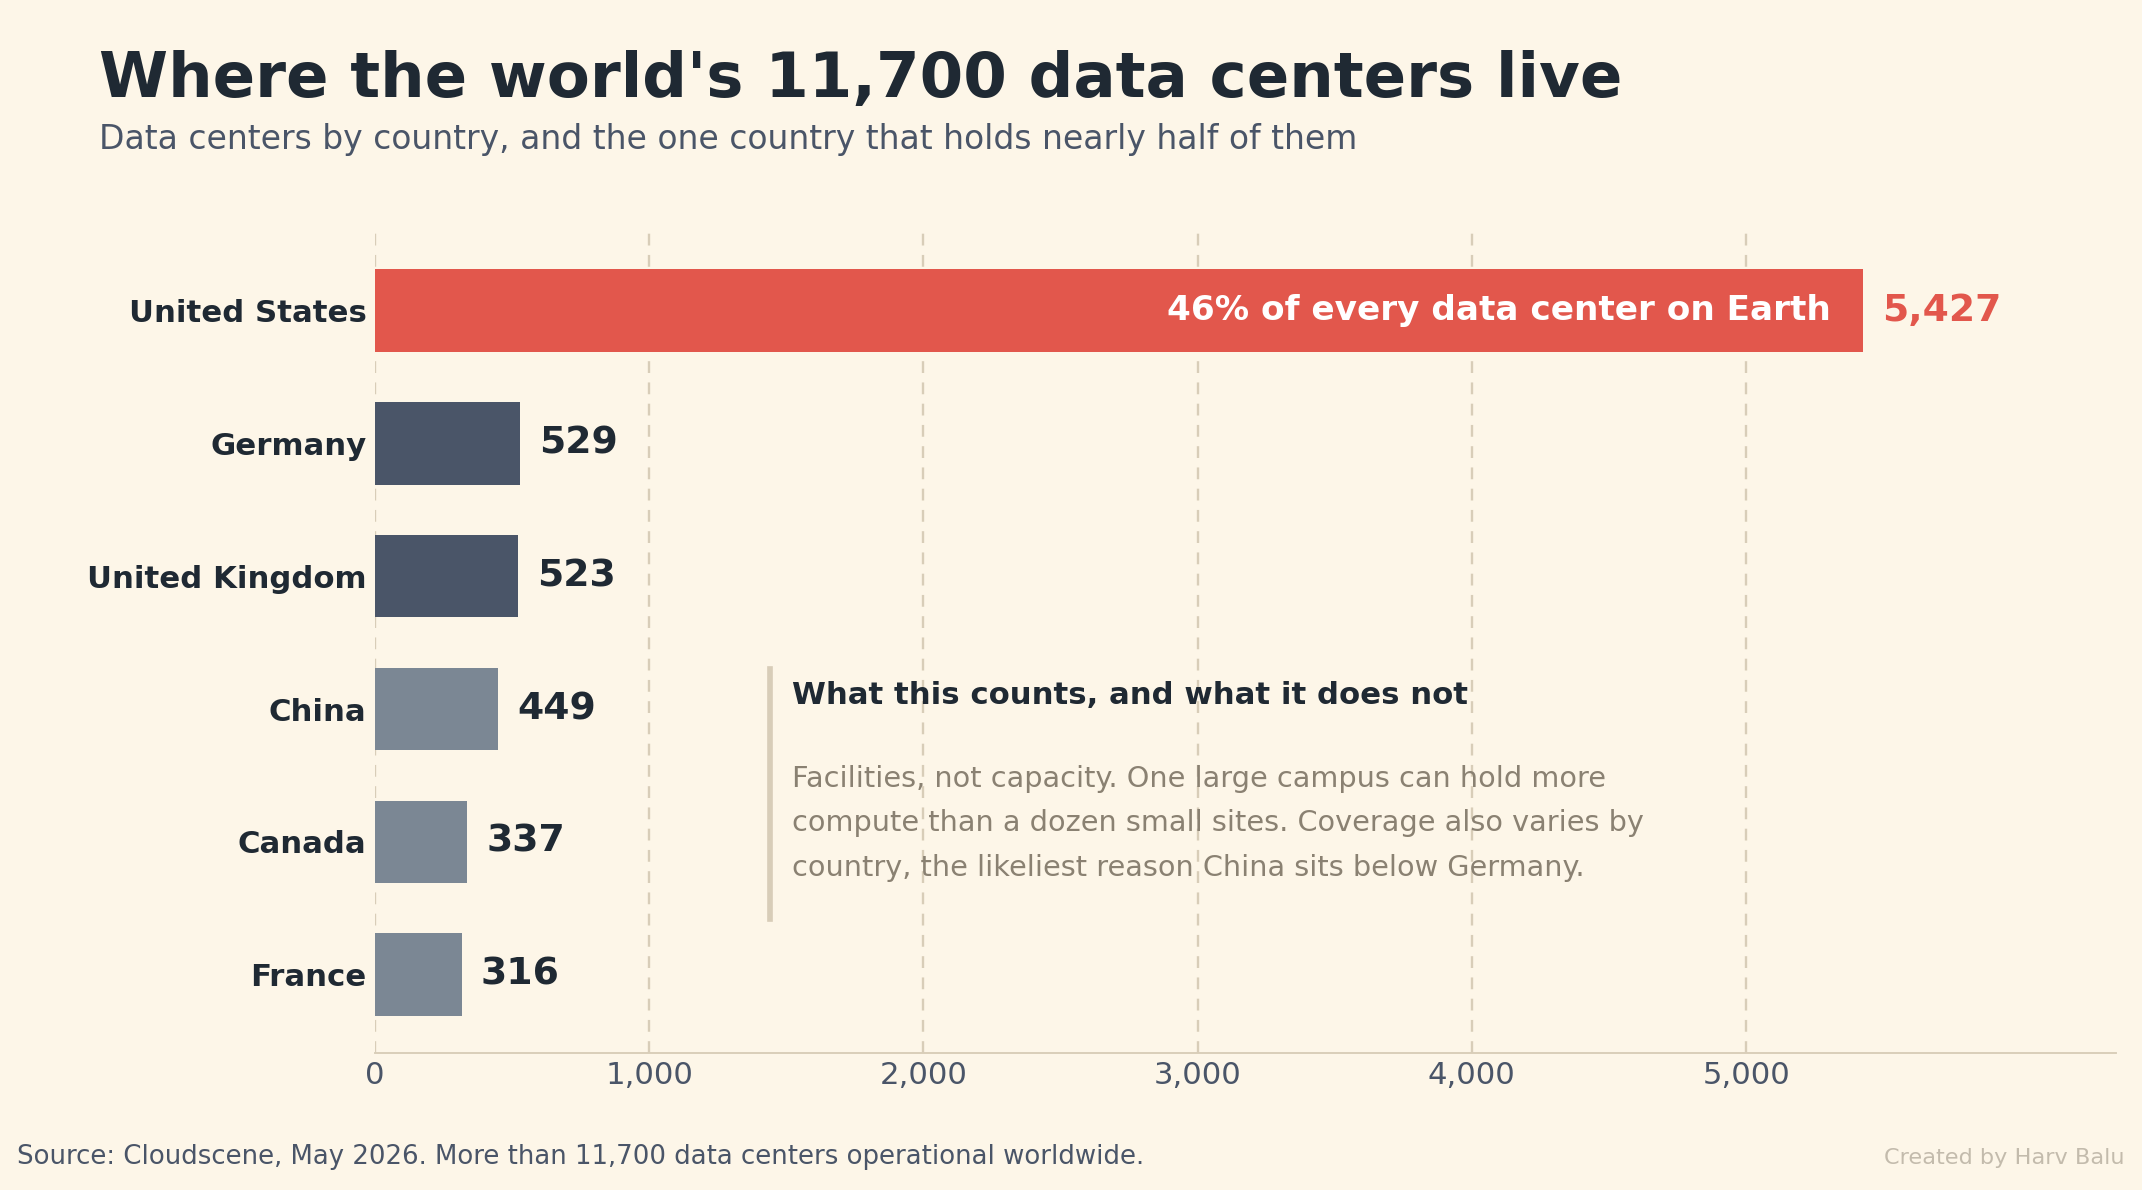
Why a housing letter is showing you a data center chart. Those buildings are the reason construction crews are being bid away from home building, and they are increasingly the reason local power costs rise. The concentration above is also a concentration of demand for land, electricity and labor, and all three of those are inputs to the price of a house.
BTC: $79,384 ▲ 0.07% | ETH: $2,478 ▼ 0.76% | XRP: $1.47 ▼ 1.85%
The rally has stalled rather than reversed. Bitcoin is essentially flat at $79,384 over 24 hours, with Ether at $2,478 and XRP at $1.47, both slightly lower. These are live quotes taken this morning rather than Monday's close.
Two items about money organizing itself. Strategy set up a separate $1.59 billion reserve called USD Cash, walling its dividend and debt obligations off from its Bitcoin buying, and it has not bought Bitcoin since June. When the largest corporate holder starts ring fencing cash, it is managing risk rather than adding it. Meanwhile the industry has committed close to $200 million to the midterms and endorsed 32 House incumbents who backed the Clarity Act. Crypto has stopped waiting for rules and started buying the people who write them.
Sources
- Mortgage News Daily (mortgage rates)
- Freddie Mac (Primary Mortgage Market Survey)
- Market Briefs (market data)
- U.S. Treasury (daily yield curve)
- Cloudscene (data centers by country, May 2026)
- Global Automakers of Canada (2025 Canadian vehicle production)
- Toyota Motor Manufacturing Canada (2025 output)
- Yahoo Finance (Brent front-month futures)
- Fortune (gold spot)
- Fortune (silver spot)
- CoinGecko (crypto quotes)
- Live Inventory (5-city MLS board)
Disclaimer: The market data, rates, and information provided are for informational purposes only and should not be considered financial advice. Always verify rates and data with your lender or financial advisor before making any decisions.