



"At a Glance" Local Housing STATS and News 08/06/26
August 6, 2026 · Alameda County Market Dashboard
TODAY'S LIVE INVENTORY
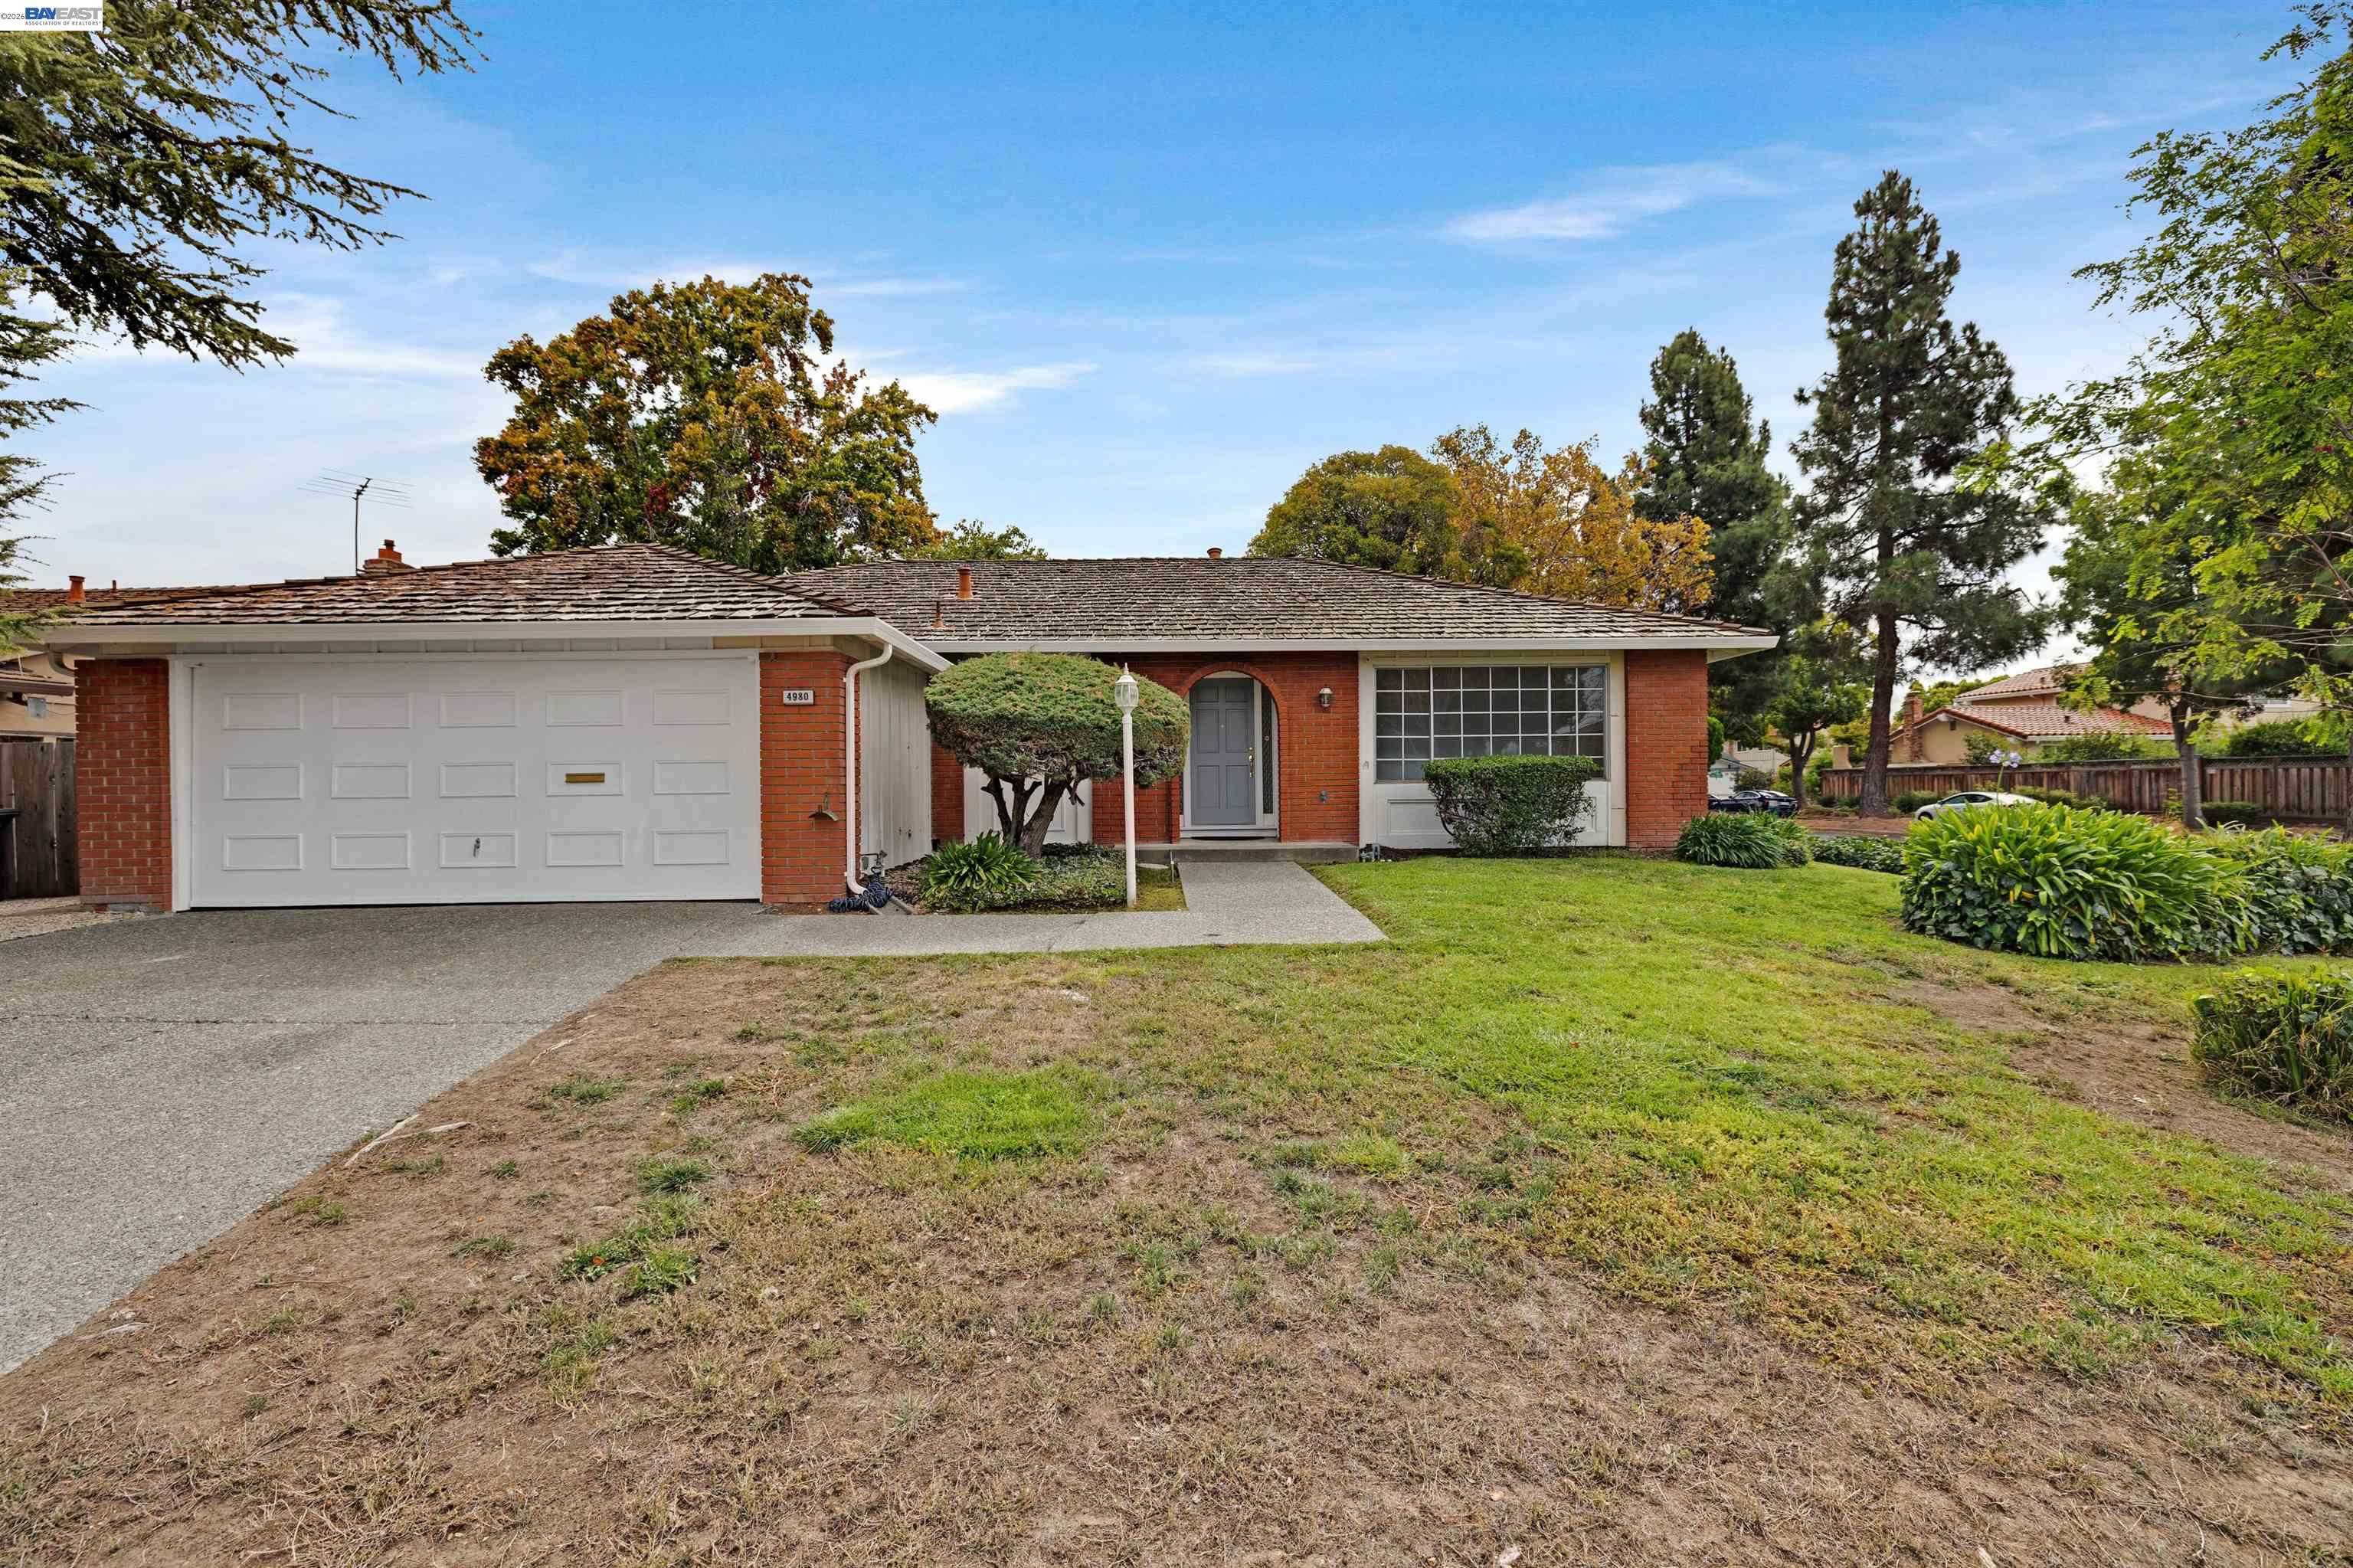
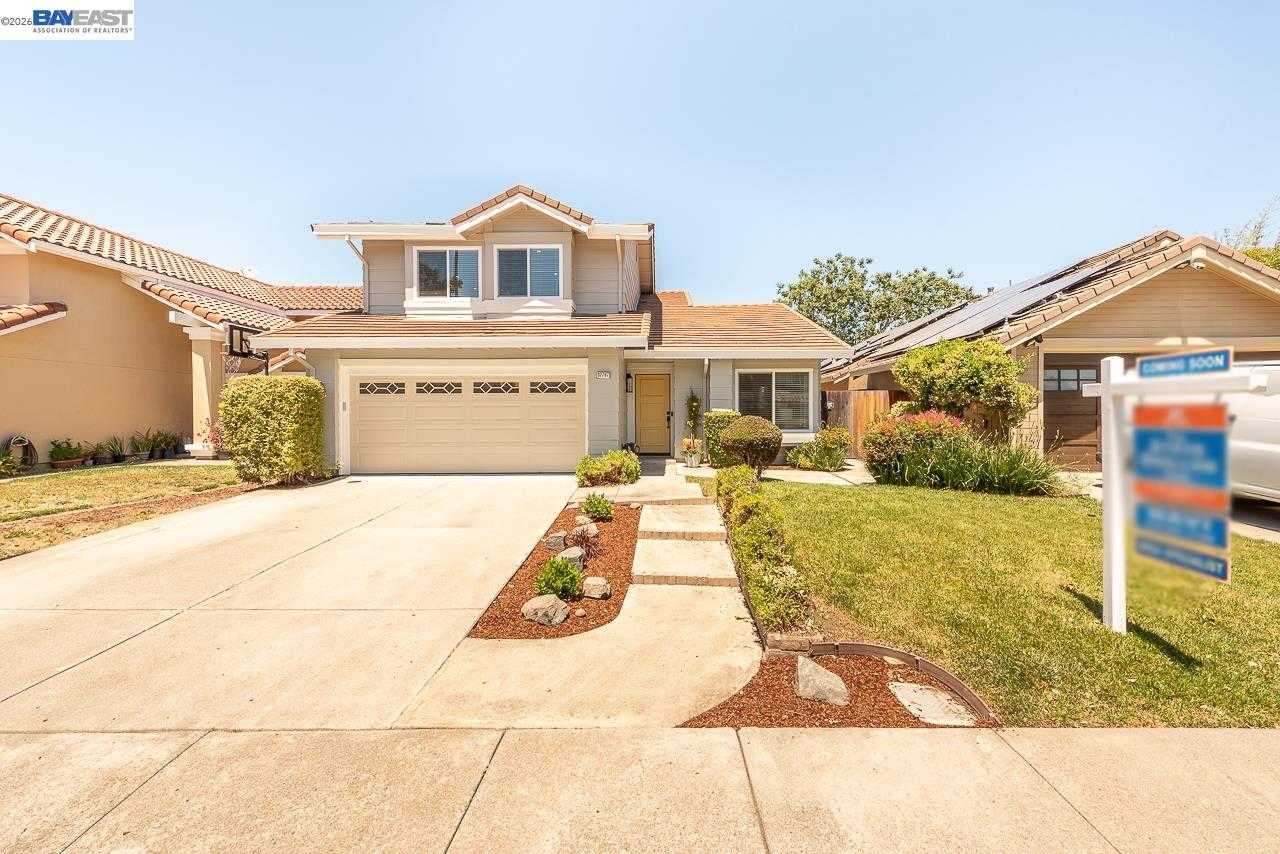
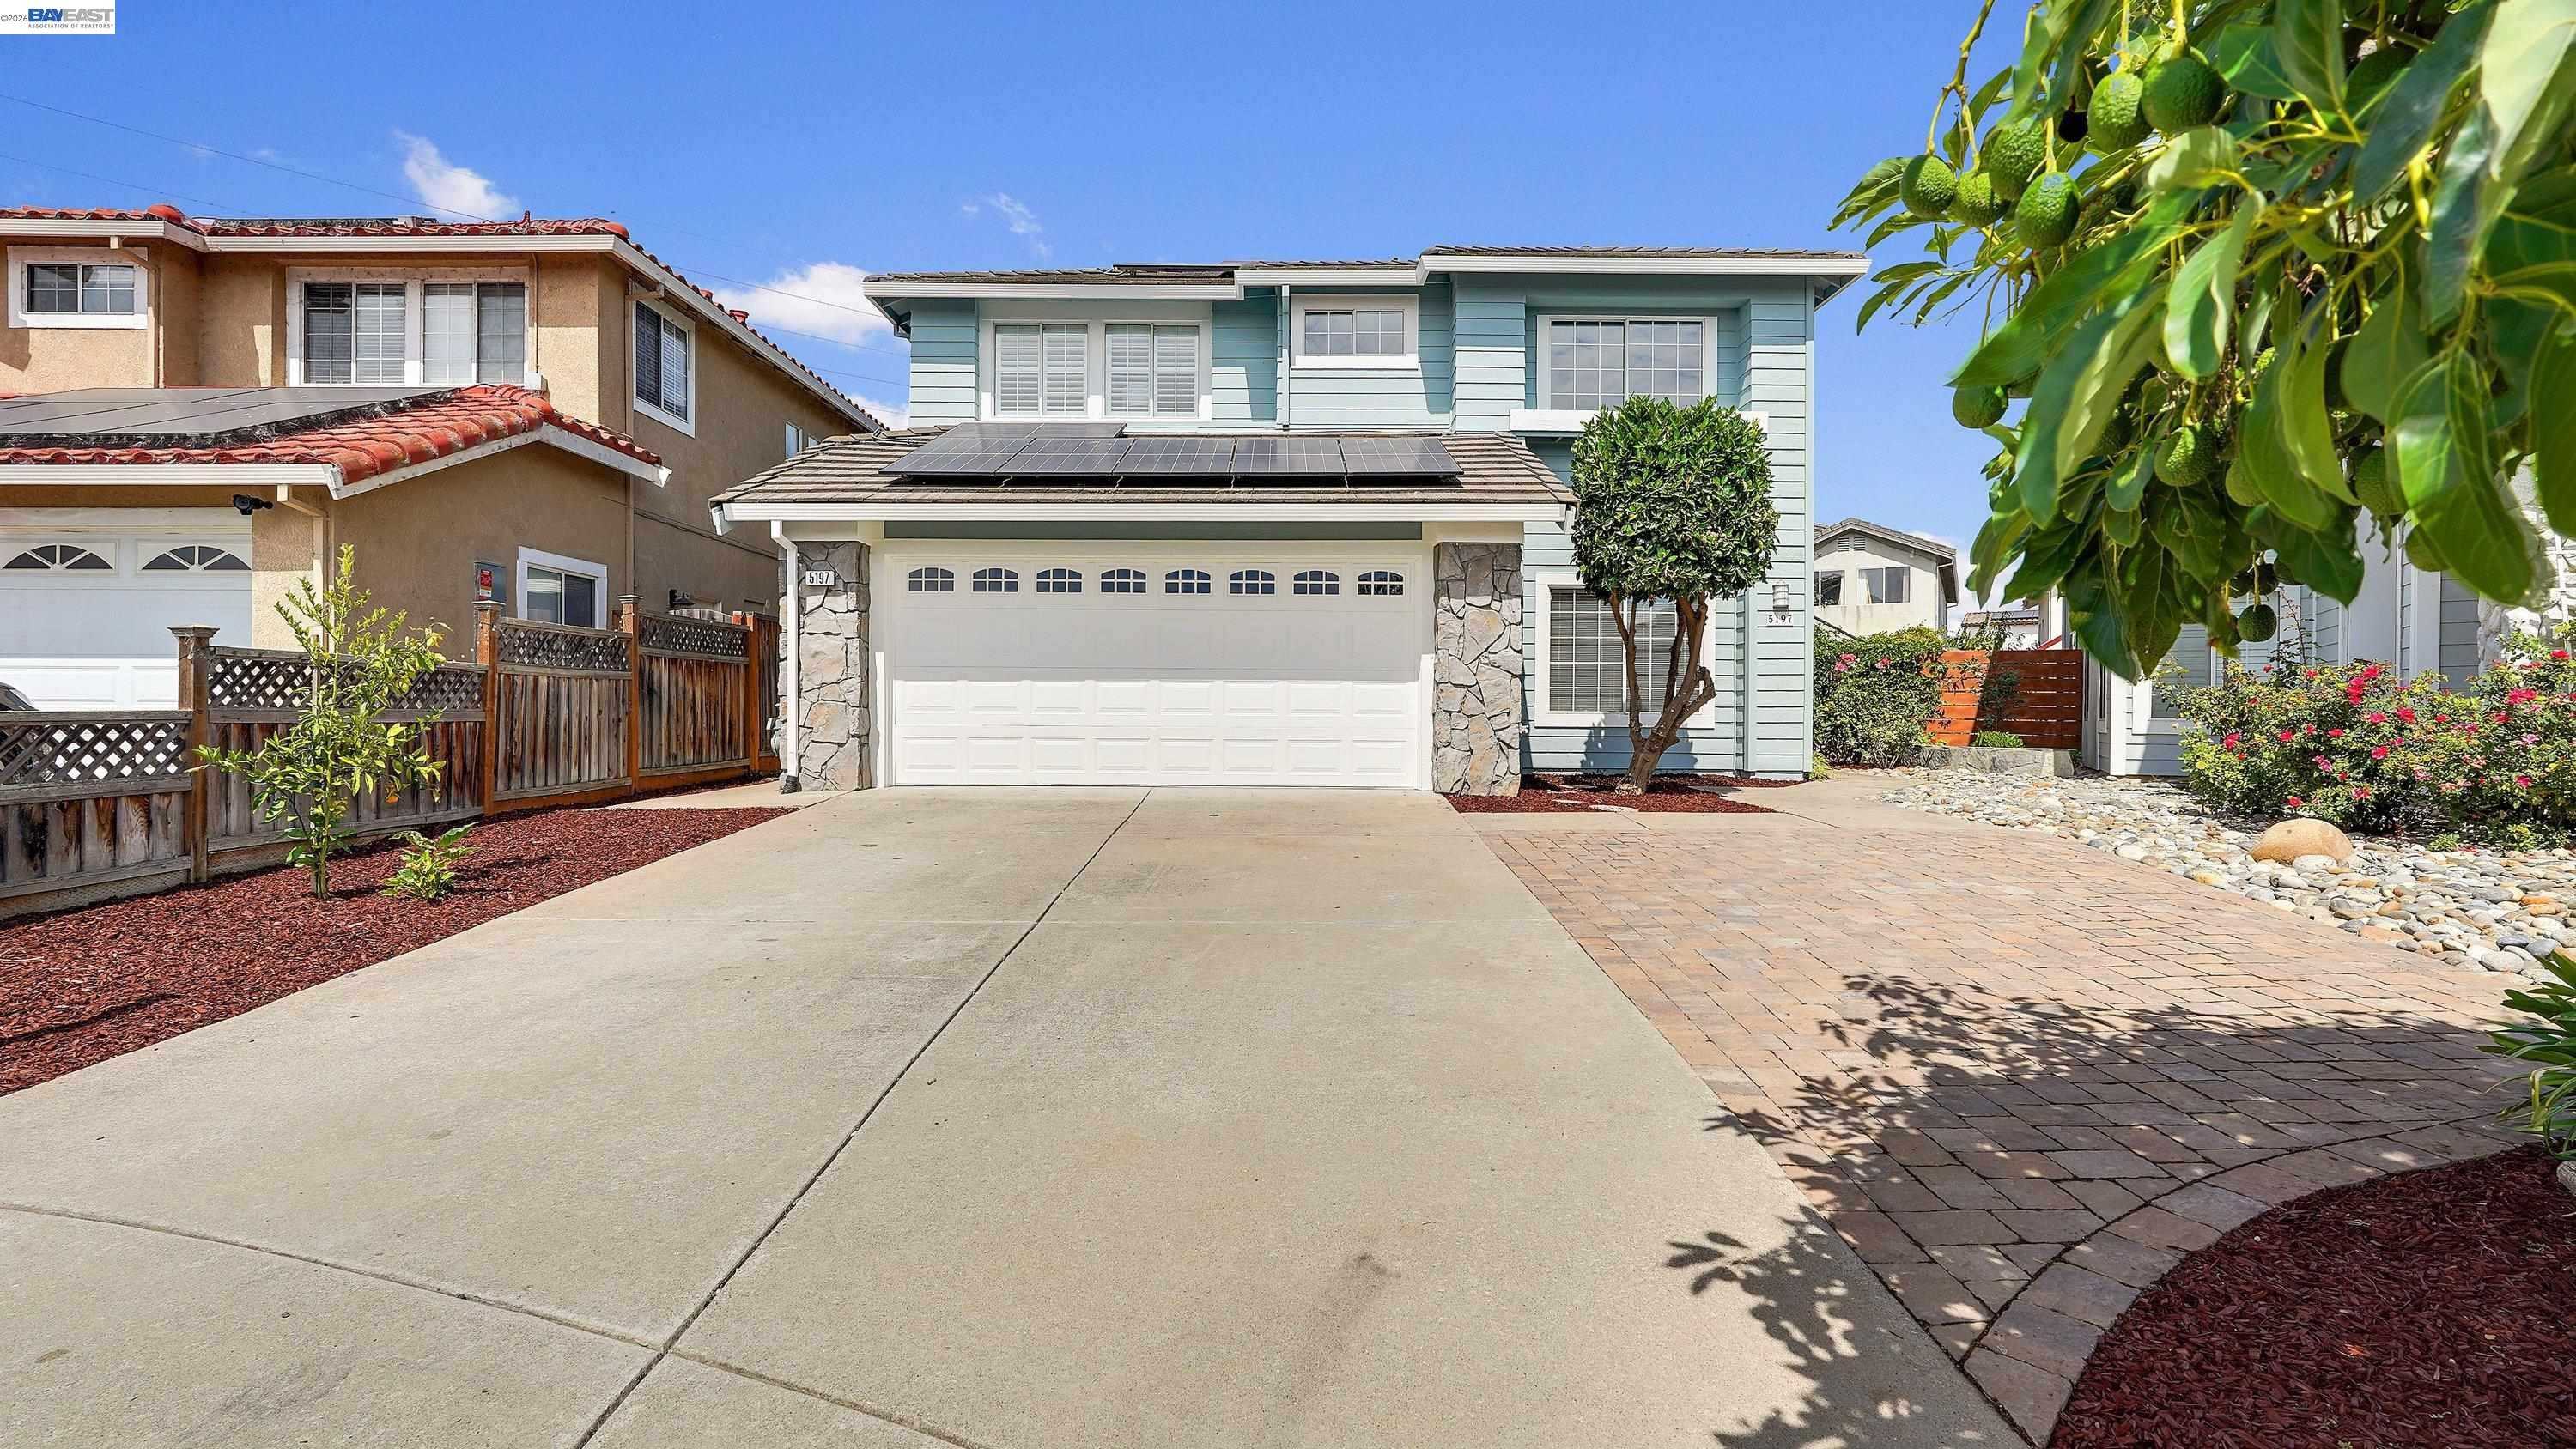
Behind these county totals: hundreds of homes still for sale in Fremont, Hayward, Union City, Newark and Milpitas, one live ledger with prices, sizes and a market read, refreshed each morning from the same MLS export.
30-Year Fixed: 6.77% ▲ 0.02% | 15-Year Fixed: 6.30% ▲ 0.01%
Rates went the wrong way. The daily 30-year fixed rose 2 basis points to 6.77% and the 15-year added 1 to 6.30%, with mortgage backed securities moderately weaker through the morning. Today’s newsletter printed 6.75% and 6.29%, which were yesterday’s numbers. We use Mortgage News Daily’s live index, so this reflects where rates actually are as of this morning.
That is the frustrating part of this week. A soft jobs report is supposed to be good news for borrowing costs. Instead the 10-Year sat still and mortgage rates rose anyway. The gap between the 10-Year and the 30-year mortgage is wider than normal right now, and until that spread narrows, good economic news for rates keeps getting absorbed before it reaches your buyer.
Home solar is worth flagging because it touches listings directly. SolarEdge fell more than 30% after its CEO said the residential market is stuck, and his reason was paperwork, not demand. Treasury still has not finalized the tax-credit rules, so buyers are waiting to see what the credit is actually worth before committing. Panel sales growth had already slowed 2% year over year in 2025. If you have a seller weighing solar before listing, or a buyer looking at a home with a leased system, that credit uncertainty is a live issue in the transaction right now.
Overseas, Norway just had its worst housing month since the pandemic began, with prices down 1.1% in July after adjusting for seasonal swings. Their central bank is now in the same spot ours is, weighing cuts against a slowing market.
Why a REALTOR® cares: this is a week to manage expectations rather than make predictions. Hiring stalled, which historically points toward lower rates, and rates still went up. If you have a buyer waiting for a number, do not attach a date to it. Show them what today’s payment looks like and what a half point of relief would change, then let them decide on the house rather than on the forecast.
Today’s live board across our five focus cities shows 706 homes a buyer can actually pursue right now, up 6 on the day, including 40 brand new listings and 96 more coming soon. The full, always-updating ledger lives at harvrealtor.net/live-inventory.
Today’s Live Inventory (buyable now)
- Fremont: 281 available (217 active, 17 new, 46 coming soon)
- Hayward: 196 available
- Milpitas: 104 available
- Newark: 77 available
- Union City: 48 available
Median asking prices: Union City at $1,298,944, Fremont at $1,289,000, Newark at $1,238,000, Milpitas at $1,161,500, and Hayward at $850,000. Median days on market runs from 23 in Fremont to 37 in Hayward. Board-wide the 15-city table carries 2,704 listings, up 19 from yesterday.
Fremont’s 46 coming soon is the number to watch. That is the largest pipeline of the five cities by a wide margin, and it lands on a market where the typical home is already moving in 23 days. Fremont added 5 listings on the day and Milpitas and Hayward each added 3, while Newark and Union City both shed a few.
S&P 500: 7,723 ▼ 0.17% | DOW: 54,349 ▲ 0.49% | NASDAQ: 26,363 ▼ 0.83%
The record run paused and the market split. The Dow added 0.49% to 54,349, but the S&P 500 slipped 0.17% to 7,723 and the NASDAQ gave back 0.83% to 26,363. After two straight sessions of everything going up together, money rotated out of technology and into the older, steadier names. That is a healthier tape than it looks on the surface.
Disney was the standout, up 3.85% after beating expectations, with parks, cruises, and streaming all bringing in more than analysts modeled. It also said it plans to buy back more of its own shares in the coming months, which is management telling you it thinks the stock is cheap.
Wall Street bonuses are heading up 10% to 15% this year as deals that stalled during the M&A drought finally close. That is a real signal about the economy: bankers get paid when companies feel confident enough to buy each other. The catch is that the same banks are cutting headcount as AI takes over the junior work, so the pool grows while the number of people sharing it shrinks. Separately, private investors put $8.8 billion into AI projects across emerging markets in the first half of 2026, building data centers and power in India, Mexico, and across Africa. The AI buildout is no longer a Silicon Valley story.
US 10-Year: 4.63% ● 0.00% | Gold: $4,271 ▲ 2.38% | Silver: $61.83 ▲ 0.60% | Brent: $79.45 ▲ 0.11%
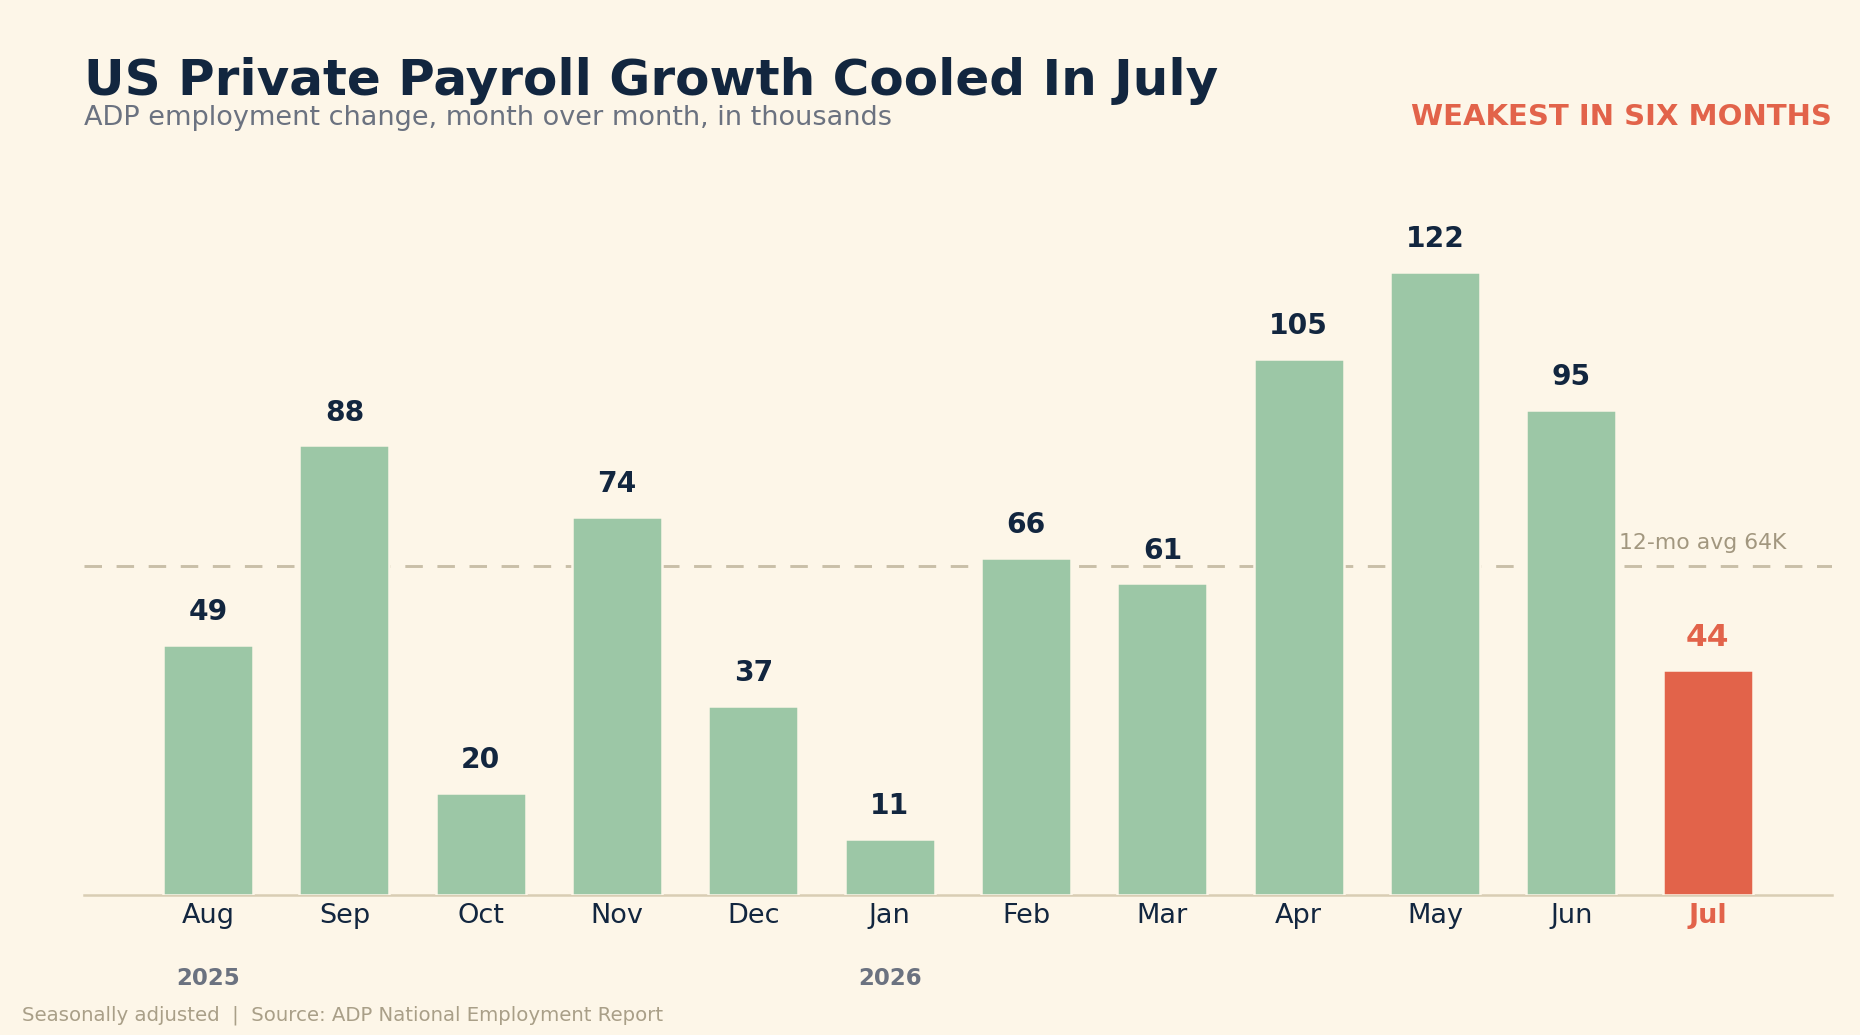
Hiring nearly stopped last month, and that is today’s most important number. ADP said private employers added just 44,000 jobs in July. Economists were looking for something closer to 70,000 to 75,000. It is the weakest month since January and it lands well under the 64,000 average of the past year. Goods-producing businesses actually cut 3,000 jobs while services added 47,000, with education and health care doing most of the lifting.
The detail underneath is more interesting than the headline. Pay for people who stayed in their jobs held at 4.4%, but pay for people who switched jobs jumped to 7.0%, the biggest year-over-year raise since August 2025. Fewer jobs are being created, yet the ones being filled are paying up. That is a labor market getting choosier, not one collapsing.
The 10-Year held perfectly still at 4.63% on Tuesday’s close, unchanged from the day before. After last week’s move down, a flat day is fine. What matters is that it has not gone back up. Metals kept climbing: gold rose 2.38% to $4,271 an ounce, its fourth straight gain, and silver added 0.60% to $61.83. Brent settled at $79.45 as a deal to partially reopen the Strait of Hormuz pulled crude back down. Cheaper oil is what let gold rally without an inflation scare attached to it.
One more with real dollars behind it: the government is refunding roughly $100 billion in tariffs the Supreme Court ruled illegal, about 60% of everything those tariffs collected. Apple, Ford, and Nike are each in line for more than $1 billion back.
Why a REALTOR® cares: a weak jobs print is the kind of news that pushes the Fed toward cutting and pulls mortgage rates down with it. That is the mechanism to watch. But notice what happened today, because it is the whole lesson: jobs came in soft, the 10-Year did not move, and mortgage rates went UP two basis points anyway. Rate relief is coming from the direction of a cooling labor market, not on any schedule you can promise a client.
BTC: $64,610 ▼ 0.04% | ETH: $1,910 ▲ 0.93% | XRP: $1.04 ▼ 2.14%
Flat to mixed, with Bitcoin sitting almost exactly where it was yesterday and XRP the weak spot. The theme this week is that crypto companies are being graded on earnings like any other business. Circle made more money overall last quarter but still missed on revenue, $701 million against the $712 million analysts wanted; it earns most of its money on the reserves backing its USDC stablecoin, so when USDC in circulation falls, revenue falls with it. Galaxy Digital had it worse, falling as much as 14% after missing forecasts, with its CEO pointing at Washington: the Clarity Act, which would finally set the rules for digital money, is not expected to pass before the August recess. Both stories say the same thing. The easy money in this sector is over and the operators now have to show real numbers.
Sources
- Mortgage News Daily (mortgage rates)
- Market Briefs (market data)
- U.S. Treasury (10-year yield, daily curve)
- ADP National Employment Report (July private payrolls)
- FRED (ADP monthly series)
- Fortune (gold spot)
- Fortune (silver spot)
- ICE Brent front-month (crude settlement)
- CoinGecko (crypto quotes)
- REALTY EXPERTS Live Inventory (5-city MLS board)
Disclaimer: The market data, rates, and information provided are for informational purposes only and should not be considered financial advice. Always verify rates and data with your lender or financial advisor before making any decisions.